



New Zealand Dollar Forecast: US rates recalibration leaves NZD/USD clinging to 200DMA
Rising US yields, surging Treasury volatility and a hawkish repricing in Fed expectations have combined to hammer NZD/USD in recent sessions. With weak domestic data also piling up, the Kiwi is losing support from both offshore and local drivers.
Share this:
- NZD/USD correlations with US rates volatility surged last week
- Treasury-led selloff leaves kiwi testing 200DMA support
- PSI and labour data point to ongoing domestic weakness
- Markets still aggressively priced for RBNZ rate hikes
Bond market volatility hammers kiwi
NZD/USD is increasingly behaving less like a traditional commodity currency and more like a direct expression of swings in US rates and implied Treasury volatility. That relationship intensified sharply over the past week, with correlations to Treasury futures and MOVE index strengthening materially across much of the US curve, as seen in the matrix below.

Source: TradingView
Five-day correlations between kiwi and US Treasury note futures are now sitting around 0.77 to 0.80. The inverse relationship with the MOVE index has strengthened to -0.91, the strongest reading across the monitored timeframes. Often described as the bond market’s version of the VIX, the MOVE index tracks implied 30-day volatility in US Treasury markets and now sits at its highest level since early April.
Source: TradingView
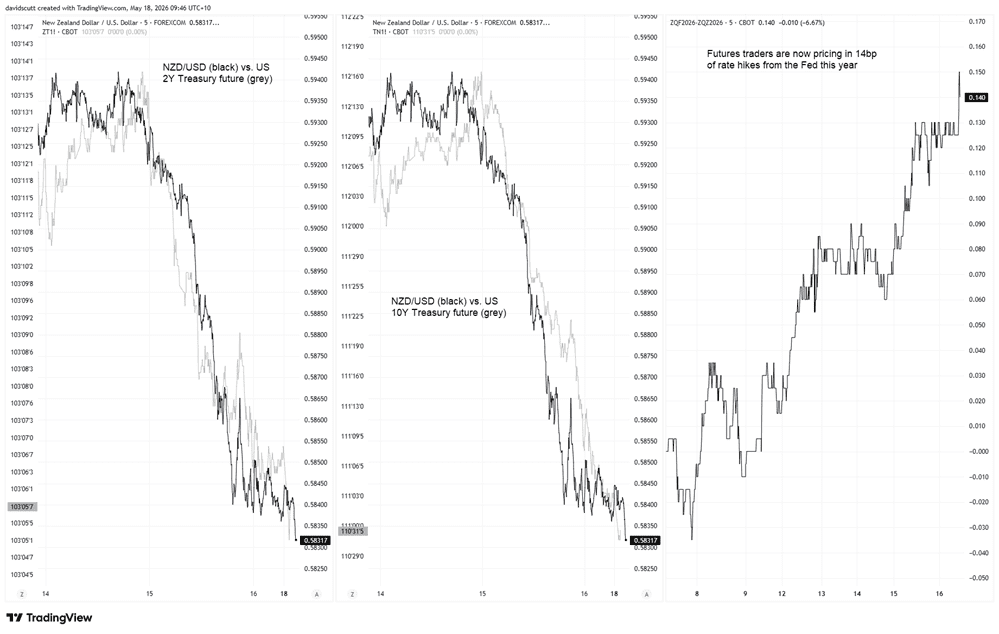
The move in Treasury futures coincided with another hawkish shift in Fed pricing. Futures markets are now pricing around 14 basis points of hikes from the Fed by year-end as traders respond to renewed inflation concerns linked to rising energy prices and developments in the Middle East.
200DMA becomes key battleground
Source: TradingView
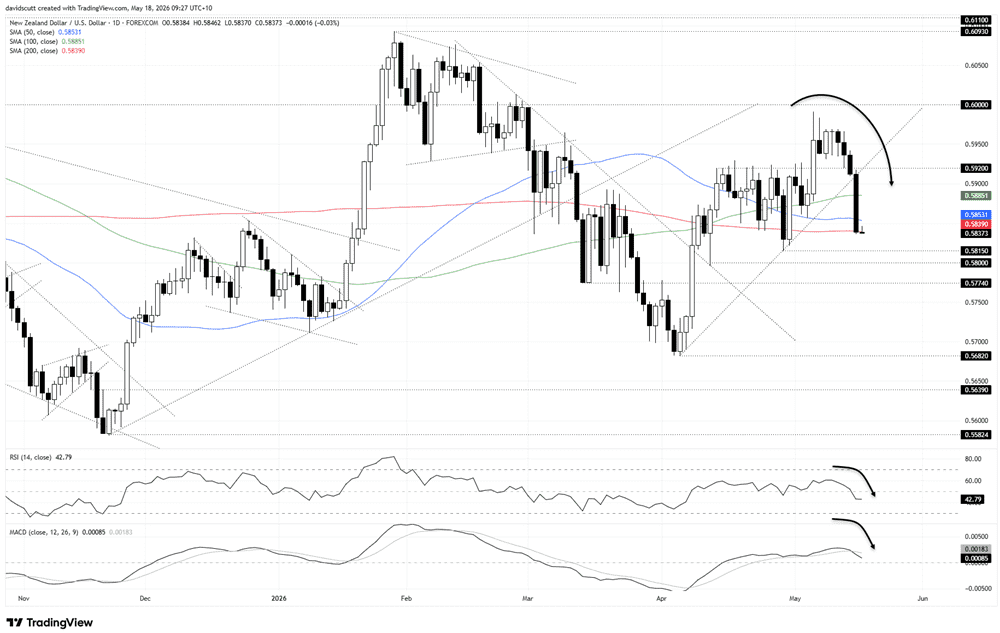
The slide in Treasury futures which saw underlying yields surge higher helped spark a violent breakdown in NZD/USD late last week, seeing the pair slice through uptrend support dating back to early April before running through the 100 and 50-day moving averages like they weren't even there.
It now opens the week teetering on the important 200-day moving average, a level that is often probed but far less frequently crossed on a sustainable basis. That puts the price action and closing level front-and-centre for anyone looking at the Kiwi right now.
Even with the violence of Friday's move, RSI (14) is not even close to entering oversold territory yet, sitting just beneath the neutral 50 level. MACD has also rolled over, crossing the signal line while remaining positive for now. Overall, it's more a cautionary message rather than an outright bearish one when it comes to directional risks, but on current trends it favours selling into strength rather than attempting to buy dips.
Beneath the 200-day moving average, we have a series of minor swing lows at .5815 and .5800 before more meaningful support emerges at .5774. If that were to buckle, there's little in the way of visible support until the April swing low at .5682.
Should bids around the 200DMA manage to keep the bears at bay, the 50-day moving average has been respected far more often than the 100 over recent months, making it the first meaningful level overhead to watch should we see a bounce. If the price can reclaim it, attention would then shift towards resistance at .5920.
Stagflation risks complicate the RBNZ outlook
While offshore developments are dominating NZD/USD price action right now, the domestic backdrop is hardly offering much support either.
The latest BNZ Performance of Services Index reinforced the picture of an economy still struggling to gain meaningful momentum. While the headline reading improved in April, it remained below the breakeven 50 level, indicating activity continues to contract. More concerningly, the employment component remained below 50 for a 29th consecutive month, reinforcing the message from the disappointing Q1 labour market report released earlier this month that labour market slack remains elevated.
Forward-looking details were hardly encouraging either. BNZ noted signs discretionary spending is weakening sharply, particularly across accommodation, cafes and restaurants, while combined services and manufacturing indicators point to little if any employment growth and an economy potentially stalling in Q2.

Source: Bloomberg
That soft domestic backdrop suggests markets may be getting a little ambitious with RBNZ pricing. Swaps are now fully priced for a hike in August with a second move around 90% priced by September, despite little evidence the labour market is tightening sufficiently to generate the kind of sustained second-round inflation pressures likely to genuinely worry the RBNZ.
While the RBNZ has only one mandate which is to keep inflation low and stable, without the threat of second-round effects, hiking aggressively in this environment risks exacerbating what already looks increasingly like a stagflationary backdrop, adding to the risk of another deep recession similar to that seen coming out of the pandemic.
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar, GBP/USD, USD/CAD, USD/CHF, Gold Weekly Technical Outlook 11 2 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

US Midterm Forecast: The Key Risks for Traders to Watch Through the US Elections
Prediction markets are pricing in nearly 75% odds of a Democratic sweep in this week’s US midterm elections, a development that would result in a split from the single party Republican rule of the past two years - what will it mean for markets?

Gold forecast: XAU/USD stabilised after recent falls – for now
Gold has started the first week of the new month trying to recover some ground after another bruising week. Oil prices have taken a sharp drop and that has allowed risk assets to bounce back, which has clearly helped the precious metal too. However, with sentiment remaining bearish towards the metals, and with $4000 level having been taken out last week, the path of least resistance is to the downside for gold.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.