





Q4 US Dollar Outlook: US Economic Exceptionalism to End?
The US dollar has surged on US economic exceptionalism so far this year, but that trend may change in Q4...
Share this:
US Dollar Takeaways
- The US dollar has surged on US economic exceptionalism so far this year, while economies in the Eurozone have underperformed.
- The Fed is either done or nearly done raising interest rates, but the full impact of rate hikes on the financial sector may still be coming in Q4.
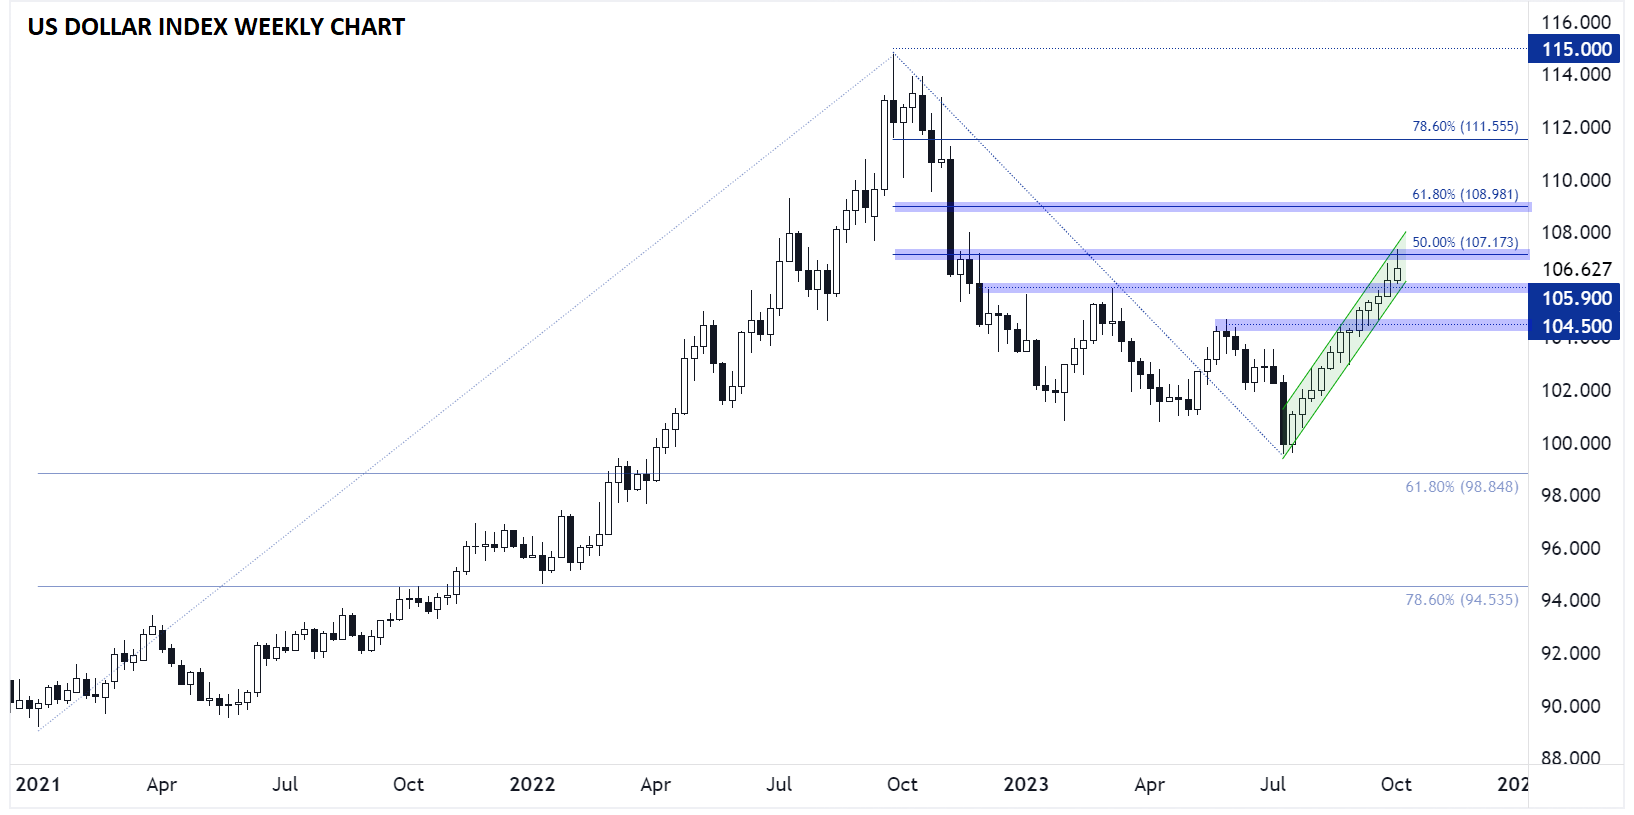
- As long as the US Dollar Index remains above 105.90, the path of least resistance remains to the upside from a technical perspective.
US Dollar Fundamental Analysis
Heading into 2023, the big debate about the US economy was whether it would experience a “hard landing” (read: deep recession) or a “soft landing” (read: growth slowdown/mild recession) as a result of all monetary and fiscal tightening over the previous 18 months. Now, three quarters of the way through the year, the market has seemingly decided that the hard landing scenario is entirely off the table, and, based on strong US data of late, even the soft landing scenario may be too pessimistic.
We’re hesitant to wave the proverbial “all clear” flag for the US economy heading into the end of the year – monetary policy acts with “long and variable” lags after all, and there still is the potential for a government shutdown in November – but it’s clear that the US economy is outperforming its major rivals. As the chart below shows, composite PMI readings in the US have turned definitively higher, at the same time that readings on the European economy have rolled over:
Source: TradingView, StoneX
Looking at monetary policy in more detail, the Federal Reserve has seemingly pushed back on fears of a sharp slowdown any time soon, leaving a potential interest rate hike on the table by the new year and removing two of its projected rate cuts from the 2024 “dot plot.”
While central bankers seemingly believe everything will be hunky dory (and are accordingly still engaging in quantitative tightening” to the tune of nearly $120B/mo), the key flashpoint to watch in the fourth quarter will be the financial sector. As the chart below shows, deposits are fleeing the banking sector at an unprecedented rate, and many small regional banks (remember those?) are facing large unrealized losses after the fastest interest rate rise in decades:
Source: Apollo
Ultimately, all modern capitalist economies run on debt and lending, so if we see another panic centered on the banks, it could pour cold water on the “US economic exceptionalism” theme…though as we saw in March, that doesn’t necessarily mean that the US dollar will fall!
Key developments to watch in Q4:
- We anticipate that the Fed will NOT hike interest rates again this year, but it’s certainly still possible if inflation or jobs data comes in elevated relative to expectations.
- Concerns over the health of the banking sector play a role in the above, with tighter credit taking a toll on growth more broadly.
- The economic exceptionalism of the US moderates as the US economy “catches down” to slowing growth in other regions
US Dollar Technical Analysis – DXY Weekly Chart
Source: TradingView, StoneX
Turning our attention to the weekly chart, the US Dollar Index (DXY) remains within a tight bullish channel as we go to press; indeed the market is in the midst of a 12-week winning streak, showing investors’ clear preference for the relatively strong growth and high yields offered by the US economy.
In terms of the levels to watch on the US Dollar Index, previous-resistance-turned-support at 105.90 could well put a floor under any near-term dips; a similar dynamic could emerge around 104.50 if that level gives way.
To the topside, there’s little in the way of nearby highs and lows, so traders will likely look to the Fibonacci retracements of the 2022-23 pullback, including 107.20 (50%), 109.00 (61.8%), or even 111.50 (78.6%) if the bulls are able to maintain the recent bullish momentum. As long prices can hold above the late-September breakout level at 105.90, the path of least resistance for the US Dollar Index will remain to the upside.
-- Written by Matt Weller, Global Head of Research
Follow Matt on Twitter: @MWellerFX
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

EUR/USD Forecast: Euro Struggles to Find Support Even After U.S. PCE Data
The euro continues to face a challenging environment in the short term. The currency has struggled to regain ground against a U.S. dollar that remains firmly supported, a dynamic reflected in EUR/USD, which has now recorded three consecutive losing sessions and a decline of roughly 0.6%.


S&P 500 Forecast: SPX rises after cooler-than-expected inflation data
U.S. stocks are rising and Treasury yields are falling after data showed that inflation increased at a cooler pace than expected, while U.S. consumer spending rose again in August.

US Core PCE Preview: Stale or Significant for the Fed
Core PCE inflation takes center stage Wednesday, with traders watching for signs of renewed price pressure and clues on whether the Fed could hike again in October.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.