



RBNZ Means Business as Hawkish Shift Launches NZD
Markets went into the meeting pricing little chance of an immediate move. They came out pricing an aggressive tightening cycle as the RBNZ signalled it’s prepared to crush inflation risks at almost any cost.
Share this:
- RBNZ shocks markets with hawkish hold
- Govenor Breman casting vote keeps rates unchanged
- RBNZ signals multiple hikes despite weak economy
- Updated track points to higher neutral cash rate
- NZD jumps as traders reprice rate path
Shock Split Decision
The Reserve Bank of New Zealand (RBNZ) left the cash rate (OCR) unchanged at 2.25% in May, as expected, but the underlying message was materially more hawkish than markets anticipated.
With only a 17% chance of a hike priced heading into the meeting, the revelation that three members voted to increase rates immediately, forcing Anna Breman to use her casting vote as chair to keep policy on hold, came as a major surprise. More importantly, all Committee members agreed that increases at upcoming meetings would likely be necessary.
The decision arrives just a day before the New Zealand government hands down its pre-election budget ahead of polling day in November.
Weak Economy vs Inflation Risk
The Committee split largely reflected differing views on whether weak domestic conditions would be enough to dampen medium-term inflation pressures.
Members favouring no change pointed to weaker confidence and spending, a soft housing market, elevated unemployment and signs firms were pulling back on hiring and investment intentions.
Those voting for an immediate hike were more concerned that higher near-term inflation could feed into higher medium-term inflation through wage and price-setting behaviour, especially if households and businesses began building expectations of higher future costs.
What was most surprising was the hawkish rhetoric came despite the RBNZ openly acknowledging recessionary-like conditions across large parts of the domestic economy. The Bank noted weaker confidence and spending, a soft housing market, squeezed profit margins and signs firms were pulling back on hiring and investment intentions, while also acknowledging elevated unemployment and significant levels of labour market slack would help dampen medium-term inflation pressures.
Yet despite that backdrop, it concluded the cash rate would most likely need to increase “sooner and by more” than envisaged in February, reinforcing the view policymakers see a meaningful risk of second-round inflationary effects becoming embedded.
Like several other inflation-targeting central banks that have turned increasingly hawkish recently, the RBNZ appears prepared to torch the domestic economy to reduce the risk of inflation expectations becoming untethered.
Neutral Rate Shifts Higher
Source: RBNZ
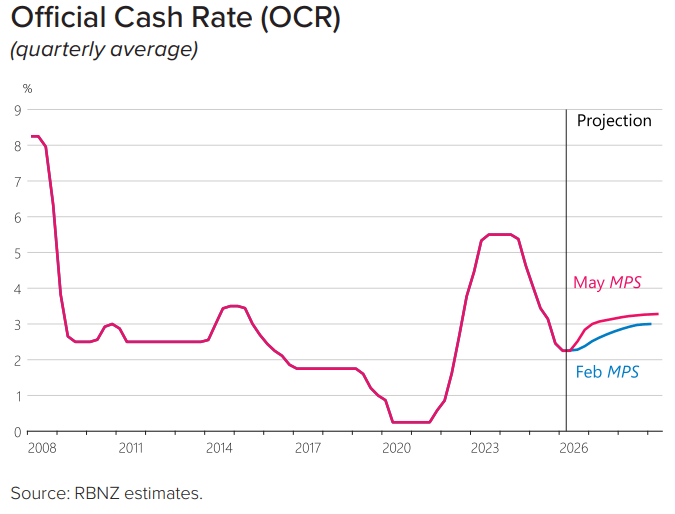
The updated OCR track reinforced the hawkish shift in guidance. While markets already had around four hikes priced by March next year, the revised projections suggest the RBNZ now sees a greater risk that rates will need to move faster and higher to contain inflation pressures. The track points to tightening beginning around the middle of this year with staggered increases until the middle of 2027.
More importantly, the longer-run profile shifted higher, with the cash rate eventually settling around 3.25%. That implies the RBNZ has effectively lifted its estimate of the nominal neutral cash rate, or the level where policy is seen as neither stimulatory nor contractionary for economic activity, reinforcing the view policymakers no longer believe inflation can sustainably return to target with policy closer to previously assessed neutral levels.
Markets Hear The Message
Source: Bloomberg
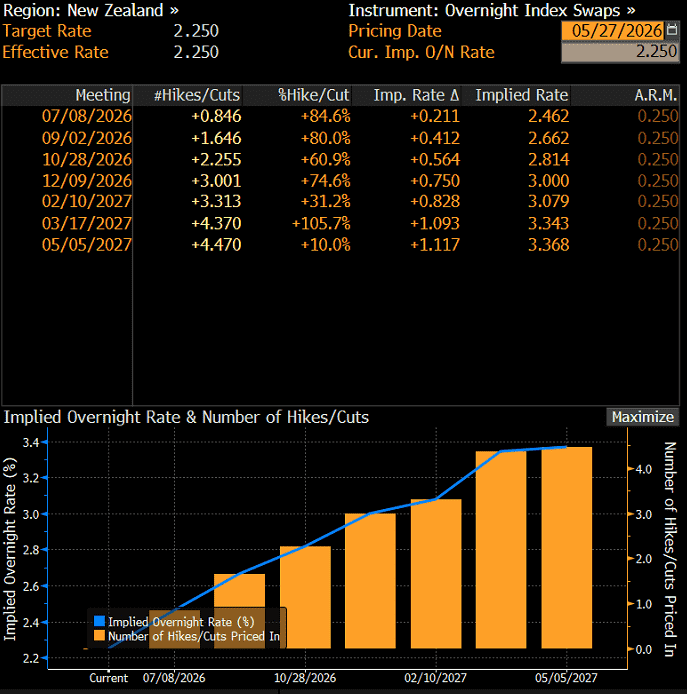
Swaps traders boosted their pricing for the RBNZ to join the global rate hiking cycle in July, pushing the implied probability up to 85% from 70% beforehand. By the time the general election is held in November, over two full hikes are now priced, with a third seen by December and a fourth by March.
While slightly more hawkish than the RBNZ’s updated cash rate track in terms of speed, it shows markets have received the RBNZ’s messaging loud and clear. They mean business, come hell or high water.
NZD/USD Breakout Risks Growing
Source: TradingView
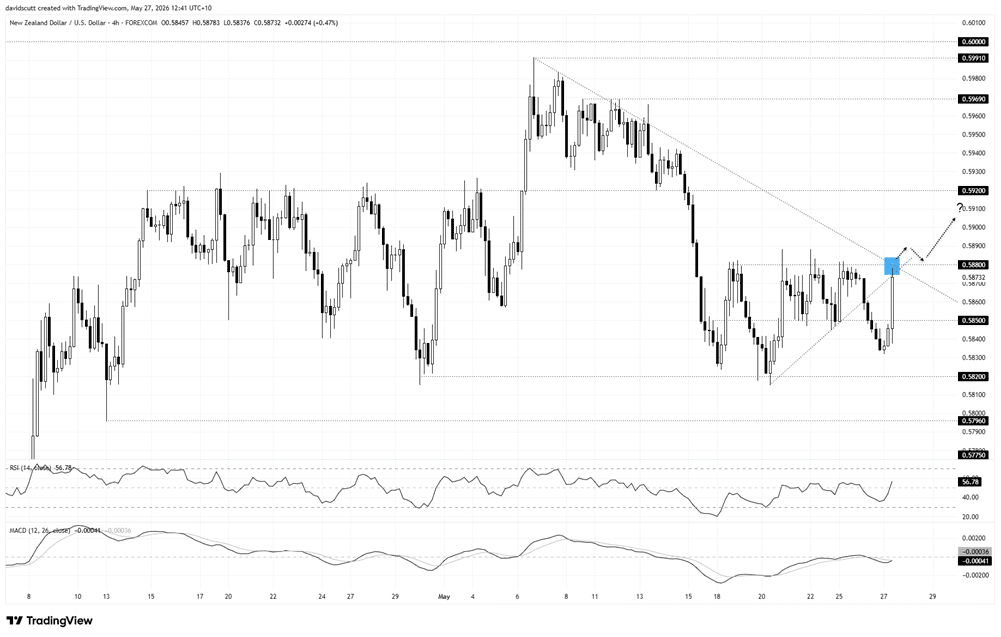
NZD/USD surged in the wake of the lineball decision, pushing higher to test the intersection of downtrend and horizontal resistance around .5880. With the oscillators flicking higher, momentum looks to be in the early stages of swinging back behind the bulls, putting traders on alert for a potential breakout attempt.
A break and close above the resistance zone may prompt additional longs to join the move, putting .5920 and .5969 resistance in play should the pair manage to overrun offers parked immediately overhead.
Should the kiwi remain capped beneath .5880, the first downside level of note is .5850 with the swing low set earlier in the session found just shy of 20 pips lower.
AUD/NZD Uptrend Under Threat
Source: TradingView
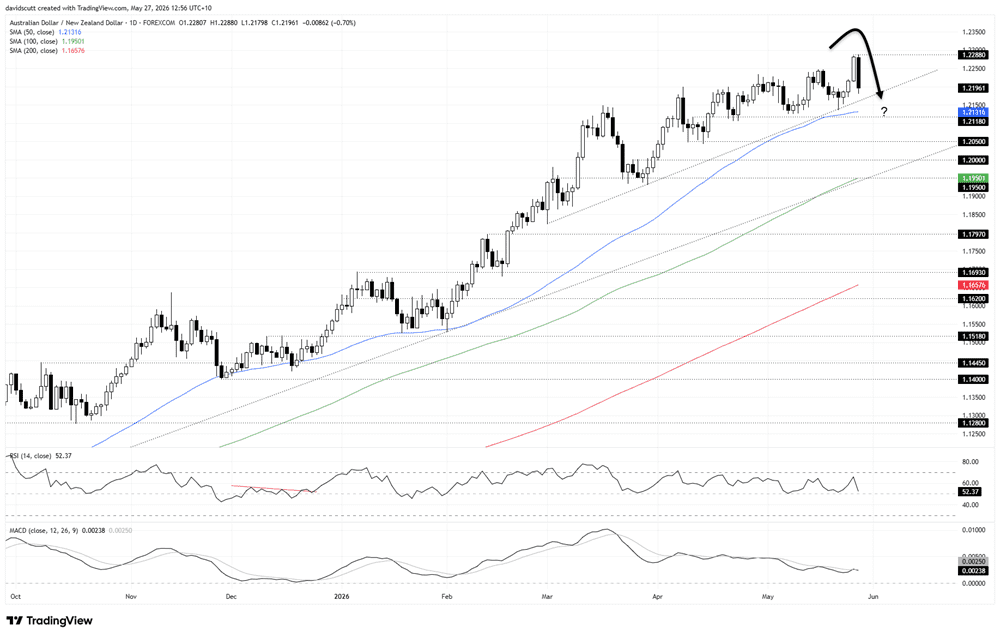
In terms of the crosses, the Kiwi is also starting to look interesting against the Aussie with the current daily candle on track to deliver a bearish key reversal. Arriving after a huge bullish trend, it warns downside risks may be growing, putting a potential retest of the early March uptrend, which essentially captures the entire Iran war period, along with the influential 50-day moving average, in play.
One look at the daily chart tells you how influential the moving average has been recently with multiple bounces from the level, making price action there potentially crucial when evaluating near and medium-term directional risks.
A break and close beneath the 50DMA puts a series of minor supports at 1.2118, 1.2050 and 1.2000 into play before a sterner test looms at the June 2025 uptrend which runs parallel to the 100DMA. If the pair cannot break lower, the immediate focal point overhead is the session high of 1.2288.
Adding to the risk of downside materialising, RSI (14) has been gradually trending lower as the price has ground higher, delivering bearish divergence. MACD is also trending lower while remaining in positive territory, reinforcing the cautionary signal.
Considering the Kiwi has underperformed during the Iran war period, you could make the case for it to outperform should hostilities continue to de-escalate.

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY forecast: US dollar strengths amid hawkish Fed despite recent oil weakness
The US dollar has extended its gains this morning, even if oil prices finished lower for the fifth consecutive day yesterday. Oil prices have bounced back in this first half of today’s session, causing a bit of pressure on currencies that rely on energy imports such as the euro, pound, Swiss franc, and Japanese yen. But it was the dollar that was exerting the most pressure, amid hawkish FedSpeak. Meanwhile, European indices and precious metals were also under a bit of pressure amid the strength of the dollar.

Why Crude Oil Slid While Middle East Tensions Kept Building
The crude oil pullback from monthly highs is running ahead of the headlines, as WTI and Brent ease while Middle East tensions stay unresolved.


EUR/AUD, GBP/AUD Outlook: Rates, risk and metals reinforce bearish technical case
EUR/AUD and GBP/AUD are coiling near support, with recent correlations suggesting the Aussie’s strength is being driven more by rates, risk and metals than energy.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.