


S&P 500 Forecast: Stocks Reverse Losses as Trump Cites Progress in Iran
US stocks opened sharply higher after President Trump said he would postpone any strikes against Iranian power plants and energy infrastructure following “productive” conversations with Iran. However, Iran has denied these comments, which could limit further upside of the TACO trade
Share this:
S&P 500 Forecast: Stocks Reverse as Trump Cites Progress in Iran
US futures
Dow futures 2%, S&P futures 1.78% & Nasdaq futures 2%
In Europe
FTSE 0.65% & DAX 2%
- US stocks jump on hopes of de-escalation
- Trump postpones attacks on Iranian energy infrastructure after productive talks
- The USD falls as treasury yields ease despite Iran’s denial
- Oil plummets over 8%
US rebound on Trump’s TACO trade
US stocks opened sharply higher after President Trump said he would postpone any strikes against Iranian power plants and energy infrastructure following “productive” conversations with Iran. However, Iran has denied these comments, which could limit further upside of the TACO trade.
Futures had fallen around 1% in overnight trade before rebounding sharply, rising as much as 4% from their lows and opening about 2% higher as sentiment recovers on signs Trump wants to do a deal.
Trump’s comments sent oil prices sharply lower — at one point down over 14% — easing fears of further escalation in the Middle East.
However, there are questions over the accuracy of Trump’s statements, which follow a tense weekend in which he gave Iran until Monday evening to reopen the Strait of Hormuz. Iran threatened to retaliate by targeting energy and infrastructure facilities across the region.
The Strait of Hormuz remains effectively closed. This key waterway, which handles around one-fifth of global oil and LNG shipments, has seen disruptions that pushed oil and gas prices sharply higher. There are also growing concerns about inflation and potential food supply issues, as fertiliser shipments could be delayed.
Trading remains highly headline-driven, leading to elevated volatility. Markets will need clearer signs of de-escalation to sustain the rally.
Treasury yields are moving lower following Trump’s announcement. The drop in oil prices has eased inflation concerns, supporting bonds. In the near term, this has opened the door to a relief rally in equities and a softer US dollar.
Investors should brace for continued volatility driven by headlines. The Federal Reserve policy outlook remains a key hurdle for equities.
Looking ahead, March PMI data will be in focus, offering a timely indication of how rising energy prices are impacting the US economy.
Corporate news
Airlines such as Delta Air Lines, United Airlines, and Southwest Airlines are rising over 4% on news that US strikes may be postponed.
Cruise operators, including Carnival and Royal Caribbean, are also gaining more than 5% amid easing geopolitical concerns, although Carnival remains down around 23% from recent highs.
Oil stocks are falling in line with crude prices, as hopes grow that the Strait of Hormuz could reopen.
S&P 500 – technical analysis
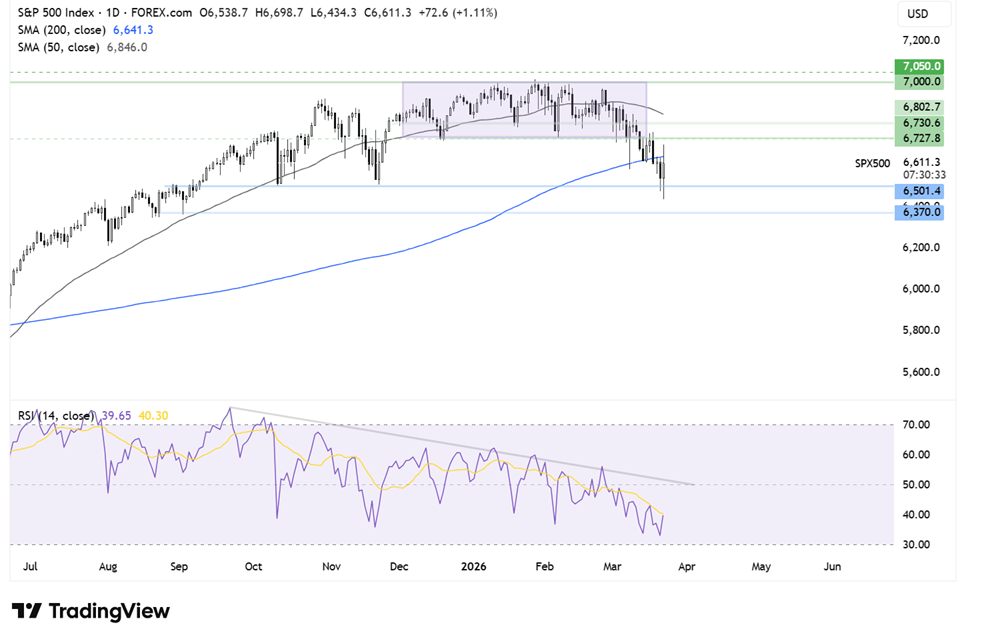
The S&P500 broke out of range, breaking below its 200 SMA to a low of 6435. The price has recovered from this low but remains below the 200 SMA. Buyers will need to settle above the 200 SMA at 6645 to bring 6730, horizontal resistance back into focus and put the price on a firmer footing. Failure to retake the 200 SMA keeps the bearish bias intact. Sellers will look to break below 6500 to head towards 6375, the September low.
FX markets – USD falls, GBP/USD rises
The US dollar is falling amid elevated volatility following Trump’s announcement.
EUR/USD is rising on USD weakness as some recent losses are unwound. The EUR had been hit hard, given Europe’s reliance on imported energy.
GBP/USD is also rising, supported by a weaker dollar and ahead of key UK data this week, including inflation and jobs figures.
Oil drops on Trump’s comments
Oil markets are falling sharply, declining around 7% ahead of the US open, after President Trump indicated progress in talks with Iran and announced he would delay potential strikes on energy infrastructure.
Trump had threatened such action over the weekend but said that, following “good and productive” discussions aimed at resolving hostilities in the Middle East, he is ready to postpone strikes for five days, depending on progress in negotiations.
Oil is declining as the risk premium fades. Whether oil can maintain these losses will largely depend on how the situation develops. The market remains highly sensitive to headlines, leading to increased volatility. Further signs of de-escalation between the US and Iran could lead to the reopening of the Strait of Hormuz — a crucial step needed to stabilise energy markets more consistently.
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DXY at Key Resistance as FX Majors Lie in Wait| Weekly Technical Outlook 10 12 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.
Dow Jones Forecast: DJIA cautious as oil jumps & earnings loom
U.S. stocks are subdued on Monday as investors weigh oil prices and geopolitical developments, while looking cautiously ahead to Q3 bank earnings and inflation data later in the week.
Oil, EUR/USD forecast: Two trades to watch 121026
Oil weighs up Russia developments against Middle Eastern tensions. EUR/USD struggles around 1.12 with US and EZ inflation data this week.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.