


S&P 500 outlook: Oil and bond yields rebound
Investor sentiment was marginally firmer early on Thursday, although optimism quickly faded as crude prices turned positive again on reports that Iran’s supreme leader has issued a directive that its uranium must stay in Iran. Whether that is a dealbreaker remains to be seen, but oil did pop higher by $4 on the news, while European markets and US index futures slipped back into the red.
Share this:
Investor sentiment was marginally firmer early on Thursday, although optimism quickly faded as crude prices turned positive again on reports that Iran’s supreme leader has issued a directive that its uranium must stay in Iran. Whether that is a dealbreaker remains to be seen, but oil did pop higher by $4 on the news, while European markets and US index futures slipped back into the red. For now, markets remain stuck in a cautious holding pattern rather than embracing a full risk-on rally. A deal would likely send stocks sharply higher in Europe and less so on Wall Street. But the longer the stalemate continues, the situation in energy markets will become a significant headwind for global growth, and stocks. At the same time, even another set of exceptional results from Nvidia failed to inject fresh momentum into equities in the way many would normally expect. All eyes are on oil prices which will determine the near term direction of risk assets and the S&P 500 outlook.
Oil markets still dictating the narrative
Crude prices fell sharply in the previous session after fresh optimism emerged surrounding a potential agreement between Washington and Tehran. That helped to ease fears over a prolonged supply disruption in the Strait of Hormuz and pointed to a potential agreement. But Reuters’ report that Iran’s supreme leader has issued a directive that its uranium must stay in Iran does complicate the picture, if true. So, the geopolitical premium on oil remains. Trump repeated that military action remained on the table if negotiations failed and suggested there was little urgency to reach an agreement quickly. That rhetoric helped stabilise prices and reminded investors that energy-driven inflation risks remain very much alive.
This is not the first time markets have attempted to price in a diplomatic breakthrough. Earlier optimism this month faded almost as quickly as it arrived, and traders now appear far less willing to aggressively chase headlines without concrete progress. The increasingly hostile tone from both sides has only reinforced that caution.
Bond markets becoming increasingly important
Attention has also been on US Treasury yields, which continue to send warning signals for risk assets. The 30-year Treasury yield briefly touched 5.20% on Wednesday — its highest level since 2007 — before easing back alongside crude prices later in the day. Today, both are bouncing back, and so stock markets are coming under a bit of pressure again.
Only a few months ago, markets were steadily moving towards a softer inflation outlook, with investors increasingly convinced that the Federal Reserve would eventually deliver additional rate cuts. But the escalation in Middle East tensions and concerns over the Strait of Hormuz triggered a sharp repricing across global bond markets.
What has been remarkable, however, is how resilient US equities — particularly technology stocks — have remained throughout the move higher in yields. The Nasdaq 100 only recently pulled back from record highs despite borrowing costs surging again.
That resilience may now face a tougher test. If yields resume their climb, pressure on the high-valuation momentum trade is likely to intensify, increasing the risk of a broader correction across equity markets. Equally, any meaningful de-escalation in the Middle East would probably trigger a rally in bonds, lower yields and provide renewed support for equities. Much still hinges on oil and developments around the Strait of Hormuz.
Technical S&P 500 outlook: Momentum is beginning to cool
From a technical standpoint, the broader trend still remains constructive despite recent volatility. However, markets are increasingly showing signs of becoming stretched in the short term, raising the probability of either consolidation or a modest pullback.
From a technical standpoint, the broader trend still remains constructive despite recent volatility. However, markets are increasingly showing signs of becoming stretched in the short term, raising the probability of either consolidation or a modest pullback.
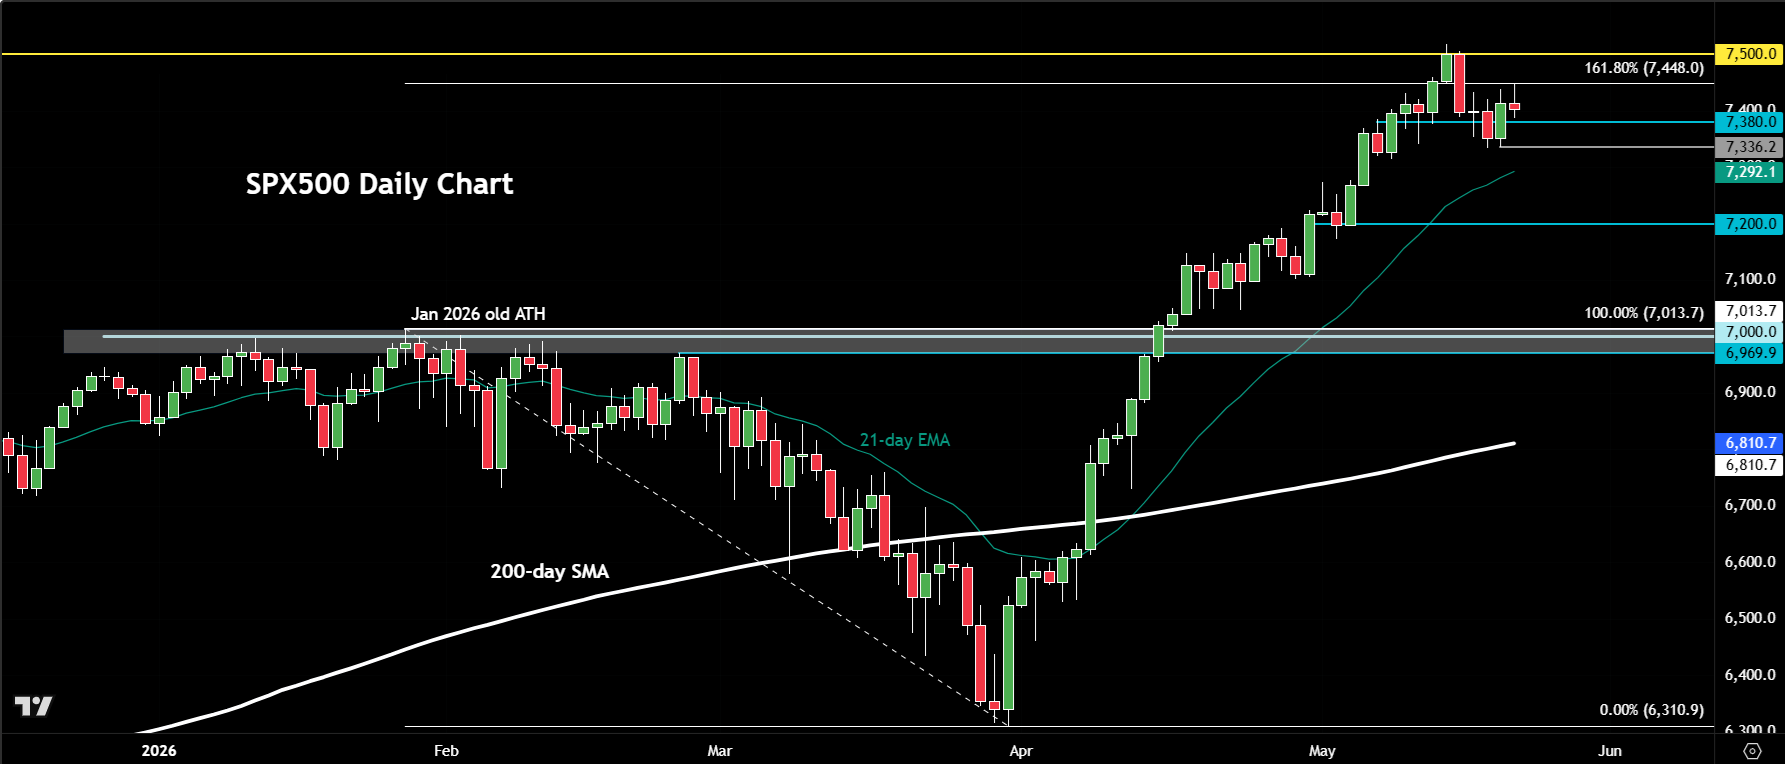
In many respects, that pause may already be underway. The S&P 500 has spent roughly the past week trading around similar levels, suggesting momentum has stalled rather than accelerated. The next phase now depends heavily on the direction of oil prices and bond yields.
The index has already extended into the 161.8% Fibonacci extension of the major downswing that began in late January and bottomed towards the end of March. That extension sits near the 7,448 region and has started to attract profit-taking activity.
Initial support is seen around 7,380. However, a move below yesterday’s low near 7,336 could expose a deeper retracement towards 7,300 and then 7,200.
Longer term, the more significant support zone remains around 7,000— effectively the previous all-time highs established earlier this year. Reaching those levels would likely require a renewed escalation in geopolitical tensions alongside another sharp rise in both crude prices and Treasury yields.
On the upside, resistance levels remain relatively thin beyond the psychologically important 7,500 area, while last Thursday’s record high near 7,540 remains the next obvious reference point for traders watching for signs of exhaustion.
For now, any weakness still appears likely to remain relatively contained. A more meaningful correction would probably require clearer evidence that underlying momentum across the broader market is beginning to deteriorate more decisively.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY forecast: US dollar strengths amid hawkish Fed despite recent oil weakness
The US dollar has extended its gains this morning, even if oil prices finished lower for the fifth consecutive day yesterday. Oil prices have bounced back in this first half of today’s session, causing a bit of pressure on currencies that rely on energy imports such as the euro, pound, Swiss franc, and Japanese yen. But it was the dollar that was exerting the most pressure, amid hawkish FedSpeak. Meanwhile, European indices and precious metals were also under a bit of pressure amid the strength of the dollar.

Why Crude Oil Slid While Middle East Tensions Kept Building
The crude oil pullback from monthly highs is running ahead of the headlines, as WTI and Brent ease while Middle East tensions stay unresolved.


EUR/AUD, GBP/AUD Outlook: Rates, risk and metals reinforce bearish technical case
EUR/AUD and GBP/AUD are coiling near support, with recent correlations suggesting the Aussie’s strength is being driven more by rates, risk and metals than energy.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.