




S&P 500 Forecast: SPX falls on caution ahead of the Fed meeting
US stocks point lower, and nerves start to show as the FOMC's two-day meeting kicks off. The market is fully pricing in that the Fed will leave rates unchanged, but it has also pushed back on when the Fed could start rate cuts. The possibility of a rate cut in June is being priced in at a little over 50/50, which has lifted the USD and is dragging on demand for stocks. Nvidia falls after the unveiling of its latest AI chip failed to attract more buyers into the stock.
Share this:

US futures
Dow futures -0.16% at 38725
S&P futures -0.40% at 5128
Nasdaq futures -0.58% at 17875
In Europe
FTSE -0.24% at 7707
Dax 0.04% at 17948
- Nerves show as the Fed’s 2-day meeting kicks off
- FOMC rate decision on Wednesday
- Nvidia’s announcement fails to attract more buyers
- Oil holds onto yesterday’s gains
The Fed’s 2-day meeting kicks off today
U.S. stocks are heading for a weaker open as nerves show through at the start of the Federal Reserve’s two-day monetary policy meeting later today. The rate announcement is due tomorrow.
The market is fully pricing in the Fed leaving interest rates unchanged at 5.25% to 5.5% this month, but the Fed could adopt a slightly more hawkish tone after hotter-than-expected inflation data for two straight months.
With no rate changes expected, the focus will also be on the Federal Reserve's new projections, particularly the dot plot, which in December signaled three rate cuts this year. However, given the sticky inflation, the Fed could lower this to two rate cuts this year. Such a move would lift the US dollar and lower equities on concerns of high rates for longer.
According to the CME fed watch tool, the market is pricing in little more than a 50/50 chance of the Fed cutting rates at the June meeting, down from around 85% just a month earlier. Meanwhile, the market is pricing in a 75% probability of a rate cut in the July meeting.
Corporate news
Nvidia is set to open lower as its annual developers conference continues. Yesterday, Chief Jensen Huang unveiled a new AI chip, the B200 Blackwell, which is 30% faster than its predecessor in some operations. However, the announcement failed to attract new buyers into a stock that had already traded up 240% Over the past year.
Bitcoin and cryptocurrency-related stocks will also be in focus after Bitcoin experienced its largest one-day decline in two weeks yesterday and continues to fall today. While the exact cause of the decline is unclear, concerns over a more hawkish Federal Reserve, notable withdrawals from Grayscale ETF, and some large liquidation could be significant contributing factors.
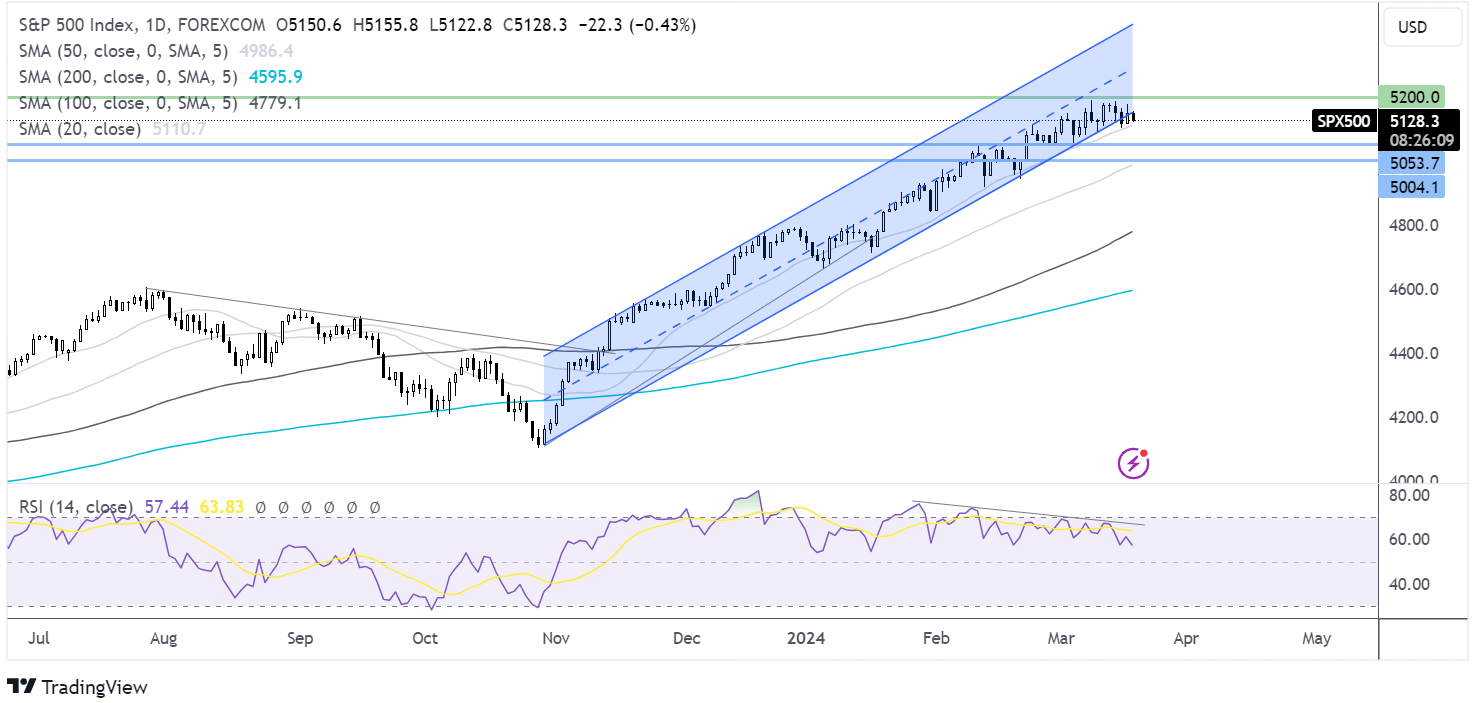
S&P 500 forecast – technical analysis.
The S&P 500 is easing lower after reaching an all-time high of 5188 earlier in the month. The price is falling out of the multi-month rising channel as it heads towards 5100, the 20 SMA. A break below here opens the door to 5050, the March low. On the upside, should the 20 SMA hold, a rise back up towards 5188 and fresh all-time highs could be on the cards.
FX markets – USD rises, USD/JPY rises
The US dollar is rising as the Federal Reserve interest rate decision comes into focus. Expectations that the Fed could adopt a more hawkish stance after persistently sticky inflation has lifted the USD against its major peers.
EUR/USD is falling against a stronger U.S. dollar and after data from the eurozone showed that wage growth slowed in the final quarter of 2023. Wage growth eased to 3.1%, down from 5.2%, and comes after the ECB president Christine Lagarde had warned that solid wage growth had been a reason to be cautious about cutting rates. Meanwhile, German ZEW economic sentiment improved for an eighth straight month, jumping to 30.5, up from 19.9 in February, suggesting there could be light at the end of the tunnel for the German economy.
USD/JPY has risen towards 150.5 after the Bank of Japan raised interest rates for the first time in 17 years. BoJ hiked by 0.1% to 0% amid signs that a wage inflation cycle could be emerging. However, the yen fell following the decision as the rate increase was only a marginal move away from the ultra-loose policy, and the central bank cited uncertainties surrounding the Japanese economy to suggest that further increases are unlikely for now.
Oil holds yesterday’s gains
Oil prices rose around 2% yesterday, and they are holding those gains, hovering around a four-month high.
Oil rose to its highest level since November yesterday, boosted by lower crude exports from Saudi Arabia and signs of strong demand from China.
However, concerns about exports rising from Russia as Ukraine continues attacks on oil refineries are limiting the upside today.
The stronger U.S. dollar is also capping gains as attention turns to the FOMC meeting. The USD is rising on the prospect of high interest rates for longer in the US, the world's largest consumer of oil. This hurts the oil demand outlook and makes oil more expensive for buyers with other currencies.
Looking ahead, attention will be on the API oil inventory data. Oil rallied last week after US crude stockpiles showed a -5.521-million-barrel draw, which was larger than expected.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Update: SPX Records Its Biggest Selloff of the Year Ahead of NFP
The trading week has not been particularly favorable for risk appetite in the short term, and this is now becoming increasingly evident in the performance of the S&P 500. During today's session, the index is down nearly 4.2%, marking its largest intraday decline of 2026.
S&P 500 Forecast: SPX tanks as tech rout resumes
U.S. trade sharply lower investors resume the chip selloff as the post-election euphoria is quickly unwound and as attention turns to upcoming economic data.

US Midterm Fallout: What Does the “Blue Tsunami” Mean for the S&P 500?
Democrats made sweeping gains in the US midterm elections, winning control of both the House and Senate - what does it mean for the S&P 500 and the AI trade?

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.