



S&P 500 Forecast: SPX rises after PPI data & gradual trade tariff reports
U.S. stocks are heading for a positive open on Tuesday, boosted by softer US PPI data ahead of tomorrow's CPI figures and by hopes of gradual trade tariffs from Trump. PPI rose 3.3% YoY in December, below the 3.4% forecast. Reports that Trump's team could adopt a gradual approach to trade tariffs are also helping the mood and bringing treasury yields modestly lower. Fed speakers are in focus later today.
Share this:
US futures
Dow future 0.27% at 42410
S&P futures 0.34% at 5855
Nasdaq futures 0.43% at 20868
In Europe
FTSE -0.05% at 8220
Dax 0.81% at 20300
- US PPI rises to 3.3% vs 3.4% forecast
- Reports circulate of Trump gradually hiking trade tariffs
- Nvidia rises after 4-days of losses
- Oil steadies at a 4-month high
PPI is cooler than forecast
U.S. stocks are heading for a positive open on Tuesday, boosted by softer US PPI data ahead of tomorrow's CPI figures and by hopes of gradual trade tariffs from Trump.
US PPI was softer than expected, at 3.3% in December, up from 3% in November but below the 3.4% forecast. The data has helped to ease some concerns regarding hot inflation following last week's ISM Services PMI data and impressive nonfarm payroll.
The PPI data comes ahead of tomorrow's inflation data, which is expected to show that CPI ticked higher in December to 2.9%, further from the Fed’s 2% target. Hot inflation combined with Trump's expected inflationary policies when he takes office later this month boosted treasury yields to 14-month highs recently.
Today, yields are easing in part following the softer PPI data but also on reports that Trump's team is considering a more gradual approach to trade tariffs, which could help bolster its negotiation position while also avoiding a spike in inflation.
These considerations are reportedly still in the early days; however, the market is clearly relieved - a softer stance from Trump towards trade tariffs would benefit stocks. Wall Street indices have been on a downward trajectory since early December, with the S&P 500 hitting a two-month low on concerns that Trump's policies will mean a more cautious stance from the Federal Reserve regarding rate cuts.
Attention will now turn to Federal Reserve officials, including Jeffrey Smith and John Williams, who could provide further clues over the outlook for Fed rate cuts.
Corporate news
Nvidia is rising after four days of declines following expectations that new US export restrictions could hurt the company's revenue.
Tesla is opening over 1.3% higher boosted by Morgan Stanley lifting its target price for the EV maker to a new valuation of $800 citing its advancements in autonomous vehicle technology and integration of embodied AI.
KB Homes is set to open over 9% higher after the homebuilders' fourth-quarter results beat forecasts. Katie Holmes posted EPS of $ 2.52 on $2 billion in revenue. This was ahead of EPS of $2.45 forecasts on $1.99 billion of revenue. Home deliveries rose 17% across the year
S&P 500 forecast – technical analysis.
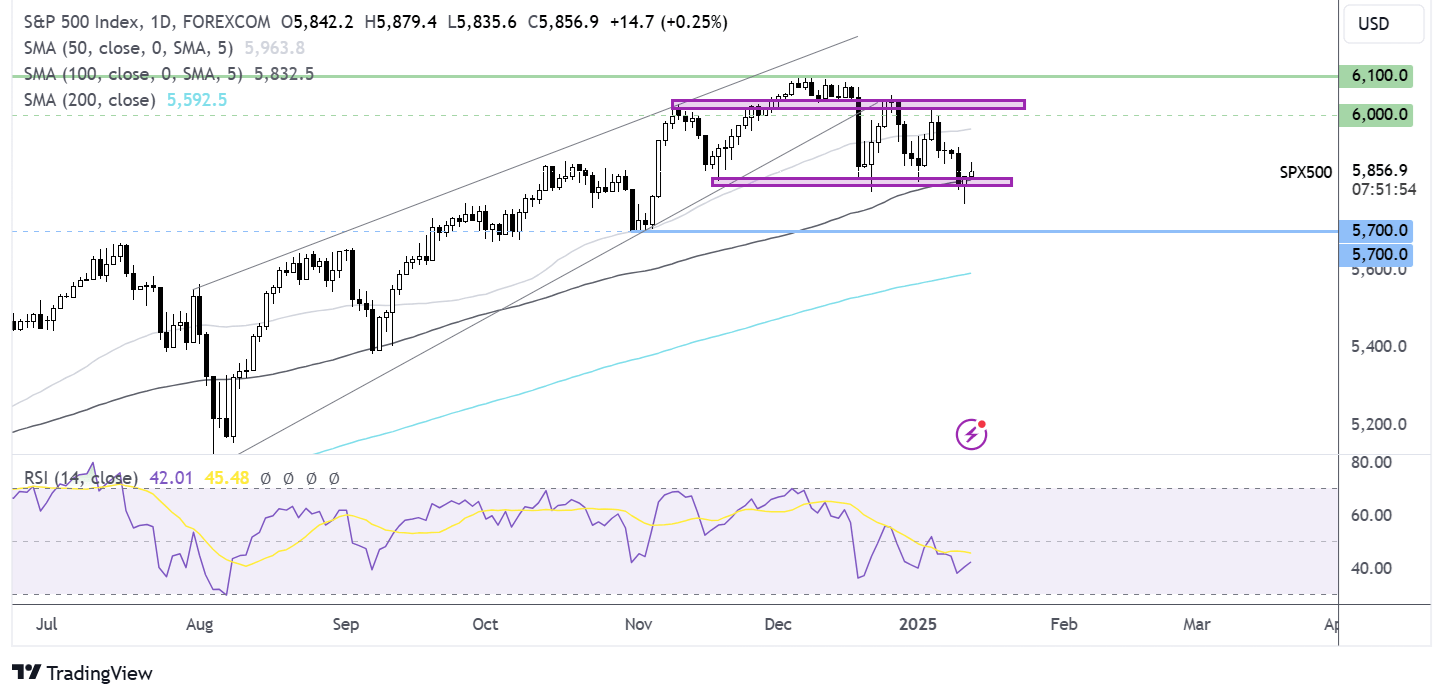
S&P 500 briefly broke below its 100 SMA yesterday, falling to a 2-month low of 5770 before recovering back above the dynamic support and 8825. The hammer candle pattern suggests a bullish reversal. However, the RSI points to further downside. Any recovery would need to rise above 5950, the 50 SMA and 6025 resistance zone. Meanwhile, sellers will look to break below the 5800 zone and 5770 to create a lower low.
FX markets – USD falls, GBP/USD falls
The USD is easing after PPI data which has eased some inflation fears, at least for now. Attention is turning to Fed speakers later today and US CPI data tomorrow.
EUR/USD is hovering around 1.0250 finding some support from reports that Trump could adopt a more gradual approach to implementing trade tariffs. Still, gains in the pair are likely to be limited given the ECB’s trajectory for rate cuts compared to the Fed. ECB meeting minutes are due tomorrow.
GBP/USD continues to slump lower, falling for a 6th straight session while trading at tits lowest level since November 2023. Concerns over the UK’s fiscal health have resulted in Gilt yields surging and GBP falling sharply amid capital flight from the UK.
Oil rises as supply concerns persist.
Oil prices are holding steady at 77.00 per barrel after three days of gains, as the market remains focused on the impact of U.S. sanctions on Russian oil exports.
Oil prices have risen to a 4-month high after the US Treasury Department announced severe sanctions on the Russian oil sector, blacklisting almost 200 vessels from its so-called shadow fleet that's also targeting oil producers Gazprom Neft and Surgutneftegas.
The move means nations like China and India seek alternative fuel supplies.
Attention will now turn to US CPI data and API oil inventories. Hot inflation and reduced Fed rate cut expectations could limit oil's upside.




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Dow Jones Forecast: DJIA rises after weaker jobs data
U.S. stocks are rising after weaker-than-expected U.S. jobs data saw markets rein in rate hike expectations.

Nasdaq 100 Forecast: NDX slips as Treasury yields keep rising
U.S. stocks are falling at the start of Q4, as gains in software stocks offset concerns over soaring Treasury yields. U.S. Treasury yields continue to rise, with the 10-year yield up 2 basis points at 5.31% and the 30-year at 5.66%, multi-decade highs.

S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.