



S&P500 easy money gone - what happens next ?
A quiet start to the new trading week as U.S stock markets closed mixed ahead of this week's FOMC and Q2 GDP data and earnings reports from U.S Mega Tech companies.
Share this:
A quiet start to the new trading week as U.S stock markets closed mixed ahead of this week's FOMC and Q2 GDP data and earnings reports from U.S Mega Tech companies.
The run of softer-than-expected leading data, including the global flash PMI’s, has raised the odds of recession from 33% to 40%. However, in the latest episode of where “bad economic news is good news”, evidence of a sharp loss of economic momentum has flowed through into lower interest rates and inflationary expectations.
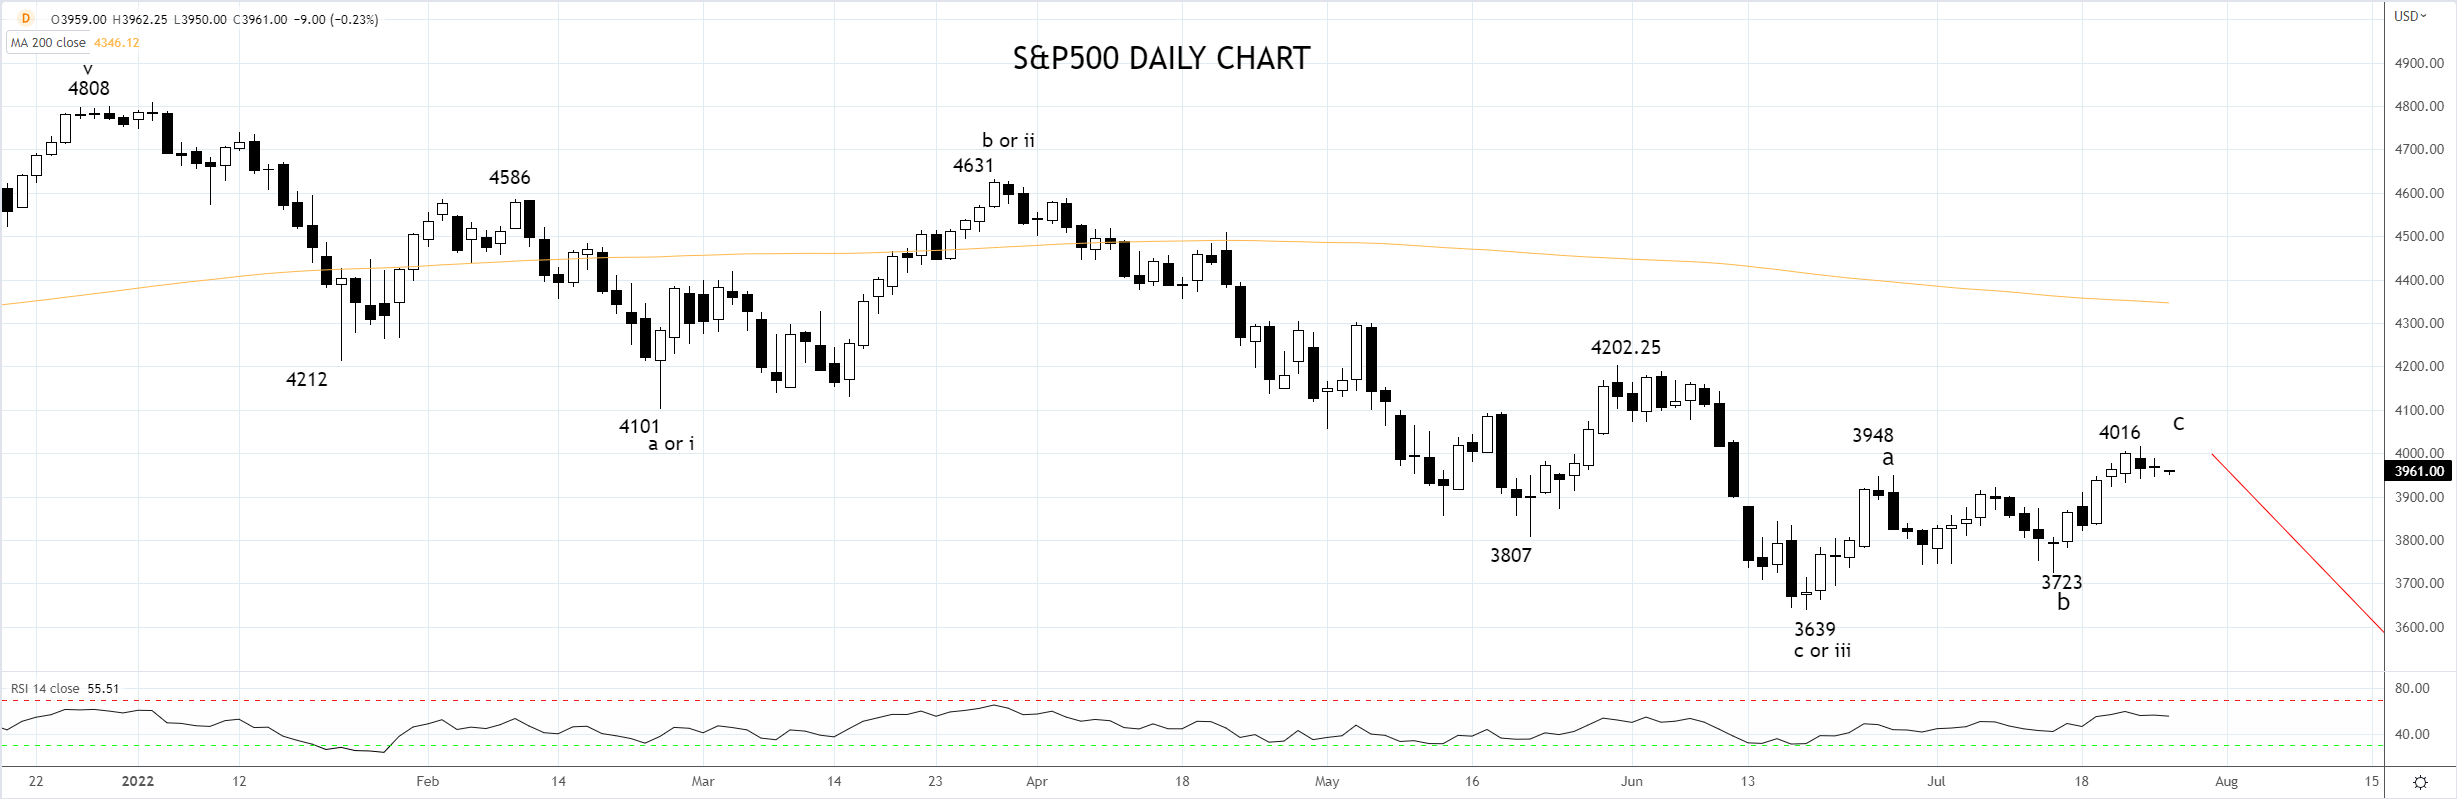
This combination has helped the S&P500 to all but reach the 4050 level we have been targeting since late June here. The "easy money" from the rally from June lows is now gone and raises the question of what happens next?
The first thing to note is that volatility will likely rise in the coming days, and following the FOMC meeting, Q2 GDP will be released later that day. The market is looking for a modest rise in Q2 GDP of 0.5%. However, the partial data has been soft, and a second consecutive negative GDP print is possible, which fits one of the technical criteria used to define a recession.
Another point to note is that the initial post-FOMC reaction is frequently reversed in the very next session. The reversal could result from positioning heading into the FOMC or investors having more time to review the nuances of the accompanying messaging.
Presuming the initial reaction for U.S stock markets is for a relief rally after the FOMC, a sell-off may well follow, particularly if the Fed remains hawkish and fails to acknowledge the slowdown in data which would inflame recessionary fears. Further to this point, the bellwether U.S equity market the S&P500 is now well off its June lows, and there is room to move to the downside.
On the other hand, should a more dovish messaging come out of the FOMC meeting, it would be a significant development and likely the catalyst for a more substantial rally - one that I suspect investors would be quick to embrace.
Turning to the charts, the rally from the June 3639 low continues to appear corrective or countertrend. Providing the S&P500 does not extend above resistance at 4200/20, the downtrend is expected to resume.
Source Tradingview. The figures stated are as of July 25th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
A quiet start to the new trading week as U.S stock markets closed mixed ahead of this week's FOMC and Q2 GDP data and earnings reports from U.S Mega Tech companies.
The run of softer-than-expected leading data, including the global flash PMI’s, has raised the odds of recession from 33% to 40%. However, in the latest episode of where “bad economic news is good news”, evidence of a sharp loss of economic momentum has flowed through into lower interest rates and inflationary expectations.
This combination has helped the S&P500 to all but reach the 4050 level we have been targeting since late June here. The "easy money" from the rally from June lows is now gone and raises the question of what happens next?
The first thing to note is that volatility will likely rise in the coming days, and following the FOMC meeting, Q2 GDP will be released later that day. The market is looking for a modest rise in Q2 GDP of 0.5%. However, the partial data has been soft, and a second consecutive negative GDP print is possible, which fits one of the technical criteria used to define a recession.
Another point to note is that the initial post-FOMC reaction is frequently reversed in the very next session. The reversal could result from positioning heading into the FOMC or investors having more time to review the nuances of the accompanying messaging.
Presuming the initial reaction for U.S stock markets is for a relief rally after the FOMC, a sell-off may well follow, particularly if the Fed remains hawkish and fails to acknowledge the slowdown in data which would inflame recessionary fears. Further to this point, the bellwether U.S equity market the S&P500 is now well off its June lows, and there is room to move to the downside.
On the other hand, should a more dovish messaging come out of the FOMC meeting, it would be a significant development and likely the catalyst for a more substantial rally - one that I suspect investors would be quick to embrace.
Turning to the charts, the rally from the June 3639 low continues to appear corrective or countertrend. Providing the S&P500 does not extend above resistance at 4200/20, the downtrend is expected to resume.
Source Tradingview. The figures stated are as of July 25th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Update: Will Fed Expectations Keep Pressure on the Euro?
The week continues to present challenges for the euro's short-term strength. This is reflected in the recent performance of EUR/USD, which has declined by nearly 0.6% over the last three trading sessions

NZD/USD: US yield advantage keeps pressure on the Kiwi
NZD/USD has become unusually sensitive to relative front-end rates, with the US two-year yield advantage now near historically extreme levels.

USD/MXN Analysis: Can the Peso Recover Against a More Aggressive Fed?
Although the Mexican peso is attempting to regain some ground during today's session, price action throughout the week shows a gain of more than 1.00% in USD/MXN, highlighting buying momentum that continues to favor the U.S. dollar.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.