



Swiss Franc Outlook: USD/CHF bearish bias capped by Fed outlook
Dollar-franc has tracked front-end U.S. yields and Fed cut bets nearly tick-for-tick since August. But with cuts already priced to neutral, downside may be running out of road unless the Fed signals something more extreme.
Share this:
- USD/CHF locked to Fed cut pricing, 2yr yields
- 131bp of easing priced, funds rate implied at 3%
- Fed unlikely to flag stimulatory policy just yet
- Technicals favour shorts, fundamentals limited downside
USD/CHF Summary Outlook
USD/CHF remains arguably the cleanest play on the U.S. interest rate outlook across the G10 FX universe, meaning Wednesday’s Federal Reserve policy decision and revised funds rate forecasts may be more influential on the pair than most. Unless you believe the Fed will signal a need to push policy rates into stimulatory territory before the easing cycle has played out—implying economic weakness—downside may be limited in the near-term.
Franc and Fed tied at the Hip
Market pricing for Fed rate cuts and USD/CHF have been essentially tied at the hip since the release of the July U.S. nonfarm payrolls in early August, demonstrating a strong relationship with shifts at the front of the U.S. interest rate curve. On a rolling 10- and 20-day basis, its correlation coefficient with market pricing for rate cuts out to June 2026 sits at -0.83 and -0.91 respectively, signalling that when pricing for cuts has increased, USD/CHF has almost always fallen, and vice versa. Similarly, the score with U.S. two-year yields has been equally strong, standing at 0.85 and 0.87 respectively for 10- and 20-day periods.
Given the influence shifts at the front of the curve have had on USD/CHF recently, it suggests that in the absence of that relationship suddenly falling apart, anything that can influence market pricing will almost certainly influence dollar-franc, including Tuesday’s U.S. retail sales report before the FOMC rate decision on Wednesday.


Downside Limited as Rate Cut Pricing Swells?
While the technical picture for USD/CHF remains in favour of playing the pair from the short side (we’ll get to potential setups later), from a fundamental perspective, downside risks may be limited in the near-term given just how much easing is priced in. There’s already 131 basis points of cuts priced into the Fed funds curve out to September next year, which implies a Fed funds rate of 3%.

Source: TradingView
That figure is important as it’s also where the median FOMC member forecast the long-run level for the funds rate three months ago, otherwise known as the nominal neutral rate. That’s the level where policy is estimated to be neither restrictive nor expansionary on economic activity, pointing to stable inflation and unemployment.
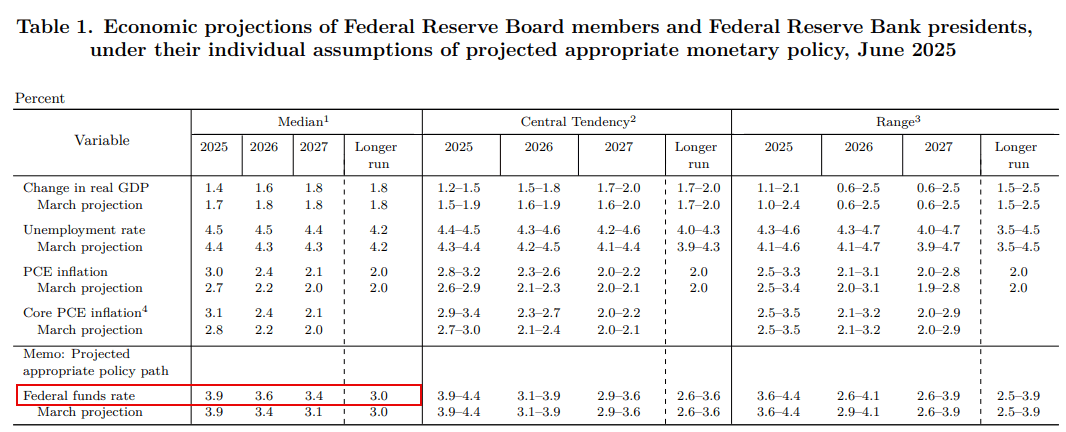
Source: Federal Reserve
Though compositional shifts of the FOMC may increase the risk of the median nominal neutral rate forecast being marginally lower on this occasion, the question traders need to ask is whether Fed forecasters want to signal a need to push rates into stimulatory territory given it will point to weakness in the economy. I suspect the public answer will be no, even if in private they see the risk, an outcome that may limit how much more easing markets can price. And, consequently, limit downside in USD/CHF until we receive strong evidence of a need for the Fed to cut aggressively to support the economy—it doesn’t feel like we’re at that point yet.
USD/CHF Consolidates Near July Swing Low

Source: TradingView
While fundamentals point to limited downside risks in the near-term, from a technical perspective, USD/CHF remains an obvious sell-on-rallies prospect. The pair broke out of the bear pennant pattern it had been trading in for several months but is yet to retest the July swing low, attracting bids at .7920 and offers at .8000 over the past week. The consolidation is to be expected given the risk events that lie ahead, but it does provide a blueprint for potential trade setups depending on how Fed pricing evolves.
If the Fed fails to deliver upon dovish market pricing, the 50DMA is the first relevant level above .8000, with a break of that putting downtrend resistance (~.8080) and resistance at .8150 on the radar for longs. However, should the Fed deliver a dovish surprise including a small risk of a 50-point rate cut (which I personally don’t see), a break below .7920 would put a retest of the July swing low of .7873 on the menu. Below that level, there is scant technical support, meaning shorts should be on the lookout for obvious reversal patterns should we see a downside break.

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY weekly outlook: Quarter turn scrambles rates regime
USD/JPY’s tight relationship with front-end US rates broke down sharply last week, but quarter-turn flows and positioning suggest the disconnect may prove temporary.

USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.


USD Sets Fresh Yearly High as EUR/USD Drops Dramatically, USD/JPY Stable
Well, it was a week of USD strength that wasn’t entirely pushed by USD/JPY, as a strong sell-off in EUR/USD has pushed the major pair to its most oversold state in a decade.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.