



US open Futures point to a mixed start ahead of Tesla earnings
US futures point to a quietly mixed start ahead of a very busy week for earnings.
Share this:

US futures
Dow futures +0.1% at 34099
S&P futures +0.04% at 4180
Nasdaq futures -0.02% at 13929
In Europe
FTSE +0.4% at 6960
Dax -0.06% at 15286
Euro Stoxx +0.1% at 4019
Learn more about trading indices
US stocks point to a mixed open
US futures are pointing to a relatively quiet open ahead of a very busy week, which sees a slew of earning releases and the Fed’s rate decision.
The Nasdaq is just coming under a bit of pressure heading towards the open as treasury yields tick slightly higher, undermining growth stocks and supporting the cyclicals on the Dow.
Europe to allow US tourists
Covid news has been a little more upbeat with EC President Ursula von der Leyen saying that fully vaccinated Americans will be allowed into Europe this summer. European travel stocks have rallied on the back od the news, with a similar reaction expected in the US market.
Commodities in focus
Commodity prices are surging higher. Copper hit its highest level in a decade. Copper prices have been on the rise in recent weeks, not just on the back of reopening optimism but also in anticipation of strong demand from the car industry, amid an acceleration towards electric vehicles. Furthermore the front runner in the Peruvian elections is threatening to nationalise mining.
Tesla to report
Tesla is due to report after the close. Tesla is expected to report EPS od $0.77c on revenue of $10.42 billion, up 66% from a year ago. The earnings come after the stock surged 740% in 2020 but is up just 3% so far this year amid a series of PR issues in both China and Texas and as competition from other automobile firms heats up.
Where next for the S&P 500?
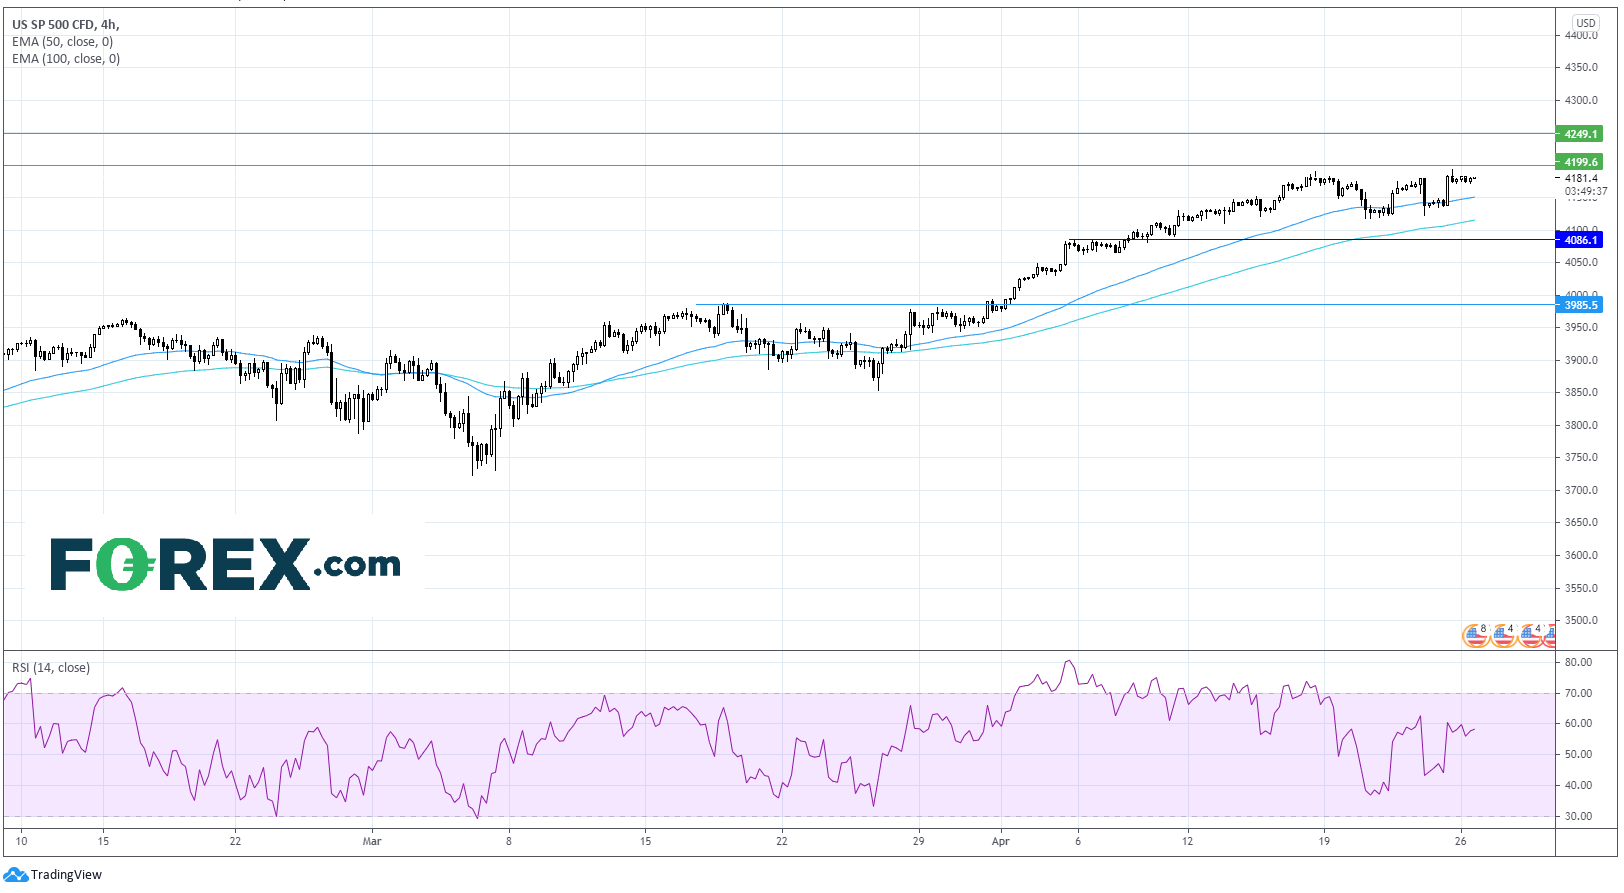
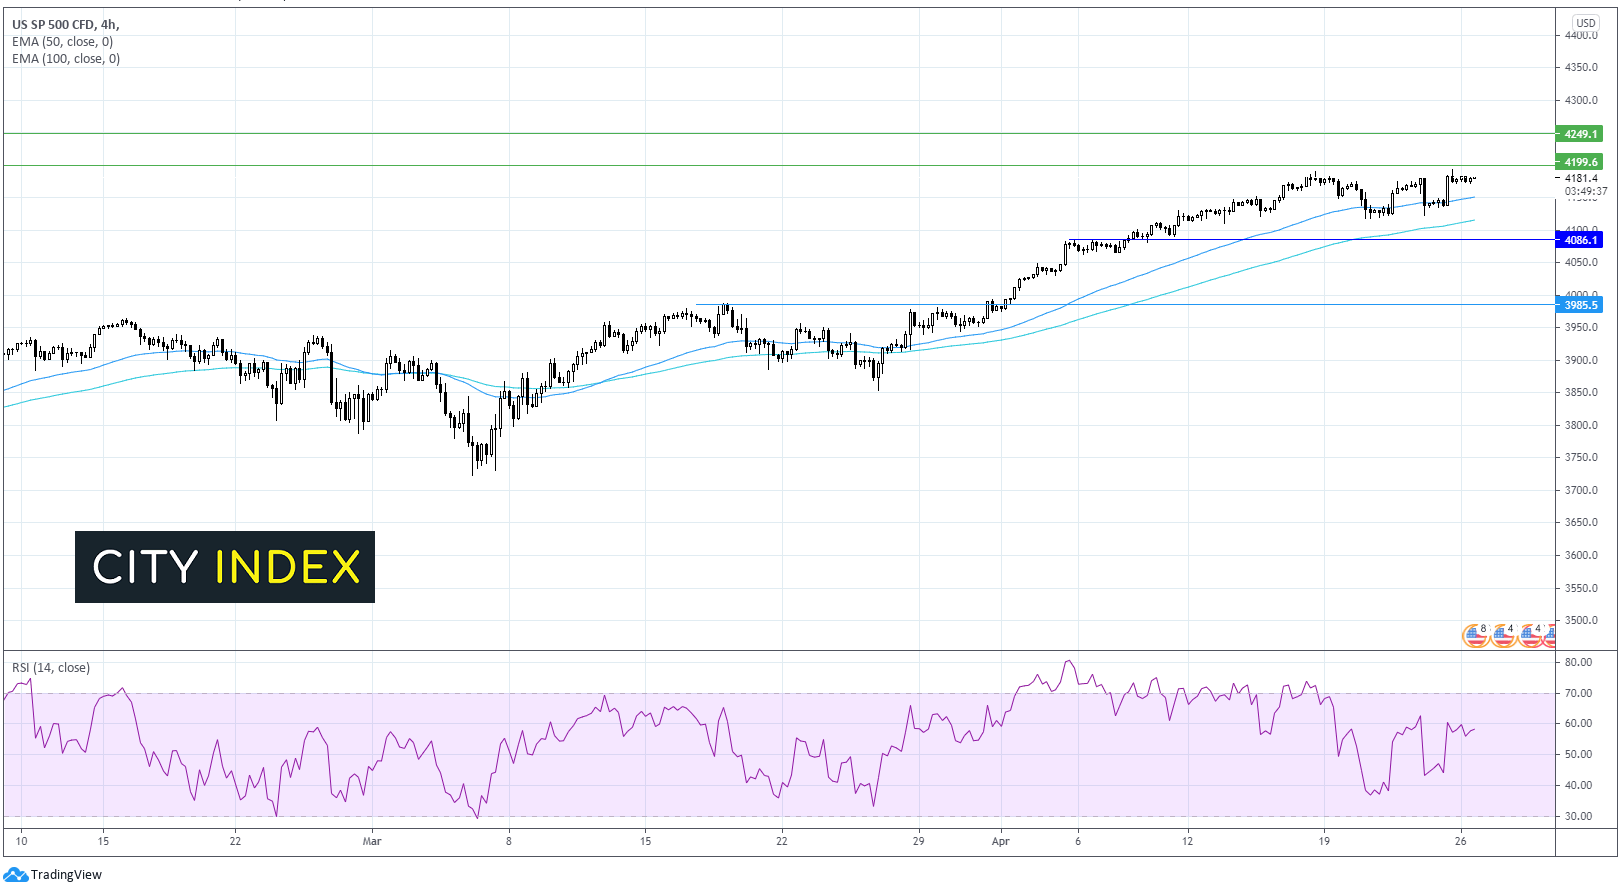
After briefly touching a fresh all time high time high on Friday the S&P 500 eased back. It trades marginally higher on the open. The technical picture remains bullish for the index with the 4200 potentially being hit in the near term, ahead of 4250. Support can be seen at 4150 the 50 EMA.
FX – Euro stumbles on weaker German IFO data
The greenback trades under 91.00 at around an 8-week low ahead of the FOMC later this week.
GBP/USD is capitalising on the weaker US Dollar, edging higher amid hopes of a vaccine led recovery. BoE policymakers’ optimism is adding to the upbeat mood surrounding the sterling.
EUR/USD trades lower after disappointing German IFO business sentiment data with 96.8. This was a slight improvement from March’s 96.6 but was short of the 97.8 forecast. Business morale slipped amid the resurgence of covid and supply issues of industrial components.
GBP/USD +0.05% at 1.3880
EUR/USD -0.1% at 1.2083
Oil extends last week’s losses on covid fears
Both oil benchmarks lost ground in the previous week and are seen extending declines on Monday amid a worsening covid crisis in India and Japan. The world’s third and fourth largest importers of oil have both seen lockdown restrictions tighten which is softening the demand outlook for oil.
On Sunday, Japan announced a state of emergency in Tokyo, Osaka and two other regions. India recorded surging covid numbers, which reached record levels for a fifth straight day. Covid cases hit 350,000 and the lockdown in New Delhi has been extended. Oil buyers will want to see some floor under the covid crisis in order to move meaningfully higher.
US crude trades -1.3% at $61.32
Brent trades -1.4% at $64.58
Learn more about trading oil here.
The complete guide to trading oil markets
Looking ahead
14:00 ECB’s Lane speech
15:30 US Dallas Fed manufacturing business index

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY weekly outlook: Quarter turn scrambles rates regime
USD/JPY’s tight relationship with front-end US rates broke down sharply last week, but quarter-turn flows and positioning suggest the disconnect may prove temporary.


USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.


USD Sets Fresh Yearly High as EUR/USD Drops Dramatically, USD/JPY Stable
Well, it was a week of USD strength that wasn’t entirely pushed by USD/JPY, as a strong sell-off in EUR/USD has pushed the major pair to its most oversold state in a decade.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.