

USD/CAD Outlook: Loonie left behind as US CPI looms
USD/CAD's sharp rebound has coincided with widening US–Canada interest rate differentials. With US CPI approaching and bullish momentum building, another breakout may be on the cards.
Share this:
- Canadian dollar badly lags G10 peers on Monday
- Divergent jobs data drives rate repricing
- US CPI threatens further USD/CAD volatility
- Bullish momentum builds beneath 1.4137 resistance
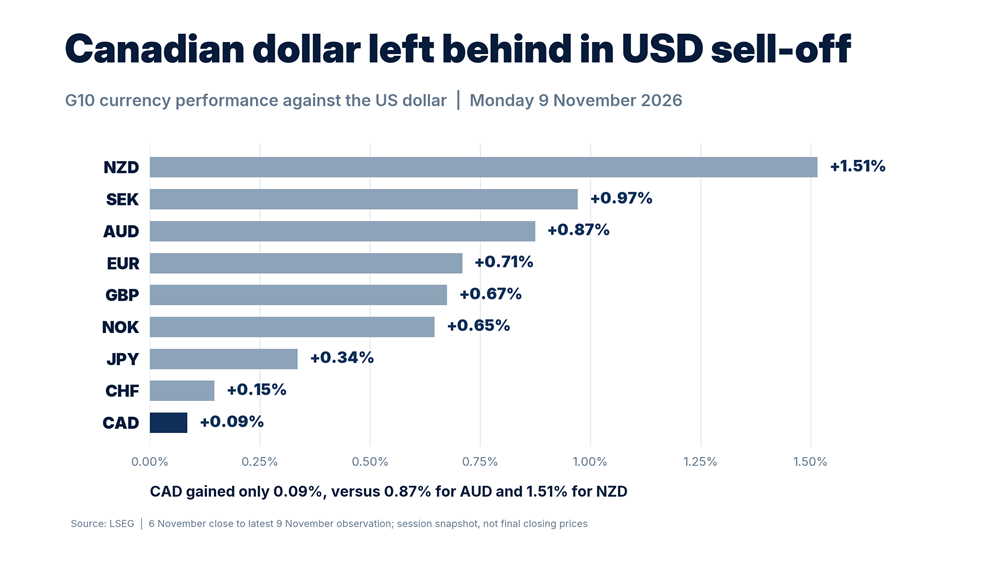
The Canadian dollar was a notable laggard among G10 currencies against the US dollar on Monday, staging a dramatic reversal after strengthening sharply earlier in the session. To put the loonie's underperformance in context, the Kiwi dollar surged more than 1.5%, while the Australian dollar, another commodity-linked currency, gained nearly 0.9%, in contrast to a miserly 0.09% gain for CAD.
While there are plenty of moving parts behind the story, the stark divergence in labour market data released last Friday appears to be continuing to have after-effects on USD/CAD heading into Tuesday's key US inflation report.
Source: LSEG
Friday's jobs data drives rate repricing
While it's now fading into the distance in the rearview mirror, it's clear that Friday's jobs reports on either side of the border continue to influence USD/CAD.
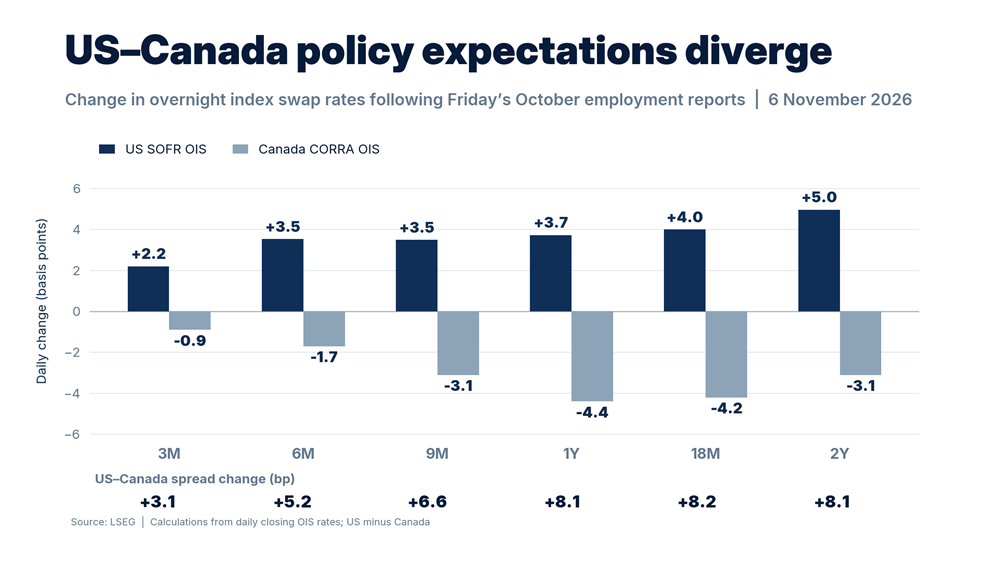
To recap, US nonfarm payrolls surged by 165,000 last month, nearly three times expectations, while unemployment ticked down to 4.1%. Average hourly earnings, which have linkages to domestic services inflation, rose by an impressive 0.4%, with the three-month annualised rate picking up to 3.9%, suggesting wage pressures may be starting to accelerate.
In Canada, the picture was the polar opposite. Employment unexpectedly fell by 4,700 against expectations for an increase of nearly 14,000, marking a third consecutive monthly decline, while unemployment unexpectedly rose to a six-month high of 6.7%. The weakness further calls into question the wisdom of the Bank of Canada's decision to raise interest rates pre-emptively last month over concerns about potential second-round inflationary effects. Put simply, there is little evidence of wage pressures emerging in the Canadian labour market, with substantial slack still evident.
Source: LSEG
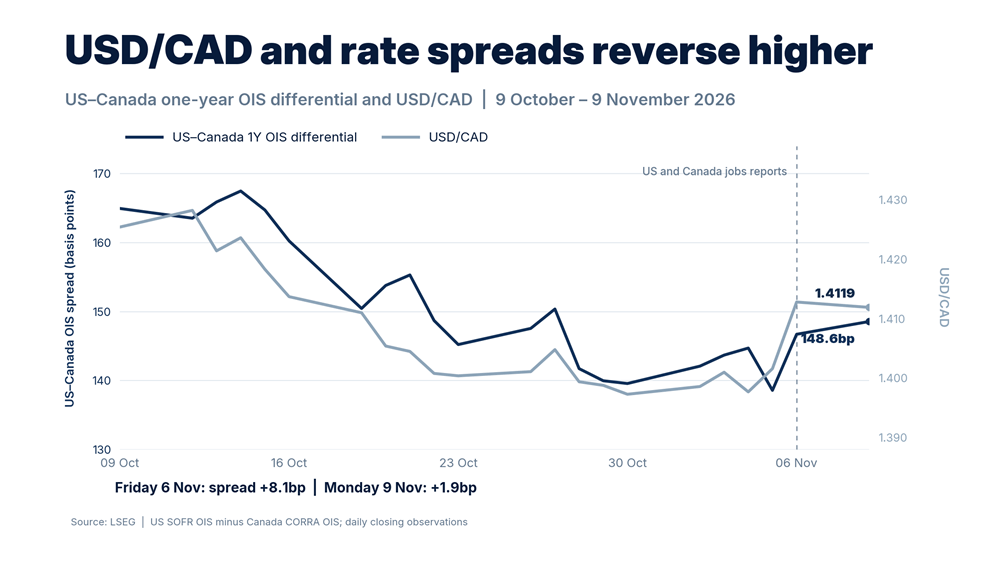
The divergent jobs reports had an immediate impact on the relative interest rate outlooks for the Bank of Canada and Fed. The one-year US–Canada OIS differential widened by 8.1 basis points on Friday, followed by a further 1.9 basis points on Monday, providing a potential explanation for the loonie's stark underperformance.
Relative rates offer a clue to USD/CAD's reversal
Analysis of LSEG data suggests relative interest rate expectations have been an important influence on USD/CAD movements. Over the past year, the correlation between twenty-session changes in the currency pair and the one-year US–Canada overnight index swap (OIS) differential has been approximately +0.79, indicating a strong positive relationship over longer periods.
While the relationship has weakened considerably over recent weeks, the price action remains consistent with the direction of relative rate movements. The widening in the one-year OIS differential since Friday has coincided with USD/CAD's sharp recovery, as seen in the graphic below. Should relative rates continue to exert a strong influence on the pair, Tuesday's US consumer price inflation report could determine whether Monday's rebound extends or falters during the session.
Source: LSEG
US CPI looms as the next major catalyst
Headline consumer prices are expected to rise 0.25% in October, with core inflation seen increasing 0.22%, according to a survey of economists conducted by the Wall Street Journal. The Bureau of Labor Statistics will not publish year-on-year headline or core inflation rates because of missing October 2025 data resulting from last year's government shutdown.
While market pricing for Fed tightening over the coming year has roughly halved from levels seen a couple of months ago, an inflation report broadly in line with expectations would still leave a strong possibility of another rate hike in December, following the increase delivered in September. Our calculations using SOFR OIS pricing suggest markets are assigning approximately a 74.5% probability to a 25 basis point hike at the next meeting.
An upside inflation surprise, similar to September's report, could all but cement another Fed increase in December, potentially widening US–Canada interest rate differentials further in favour of the US dollar and encouraging additional upside in USD/CAD. Conversely, a downside surprise could see those differentials narrow, undermining the pair's recent recovery.
USD/CAD bulls eye another breakout
Source: TradingView
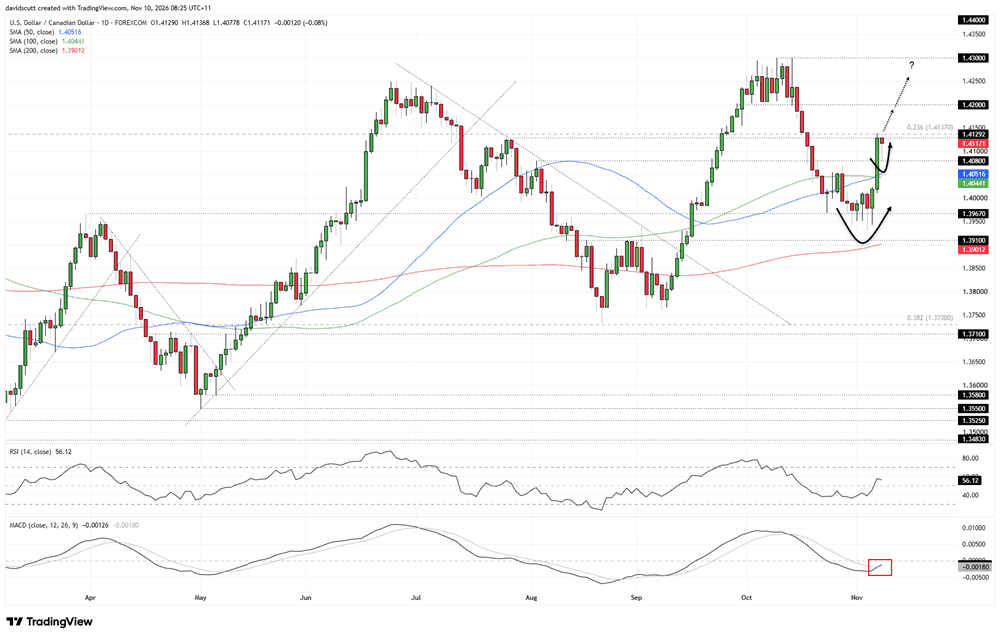
Before the latest leg higher, USD/CAD had repeatedly attracted buying interest on pullbacks towards 1.3967, the swing high set in late March that has acted as both support and resistance on several occasions. The subsequent breakout saw the price reclaim its 50- and 100-day moving averages and clear resistance at 1.4080 before stalling between the July high of 1.4129 and the 23.6% Fibonacci retracement of the June 2021 to 2025 bull move at 1.4137.
What stood out during Monday's session was the sharp rebound after the price retested former resistance at 1.4080. Buyers stepped in aggressively, sending USD/CAD back towards where it began the trading week. Combined with the strength of the preceding rally, the velocity of that rebound suggests bulls may be preparing for another attempt to break higher.
A break above 1.4137 that sticks would put 1.4200 on the radar initially, followed by 1.4300, where the pair stalled on a couple of occasions in October. Alternatively, should resistance between 1.4129 and 1.4137 continue to hold, 1.4080 would be the first level to watch on the downside.
Momentum indicators also mildly favour long setups over shorts. RSI (14) has recovered above the neutral 50 level as bearish momentum has faded and upside momentum has started to build. MACD has also staged a bullish crossover, although it remains in negative territory for now, suggesting a potential shift in momentum is taking place.
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DAX Nears New Highs as Investors Rotate Back Into Growth
The DAX continues to push higher, trading above 26,500 as investors extend last week's recovery. Falling oil prices, improving sentiment toward technology stocks and stronger-than-expected German industrial production have helped support risk assets globally. Attention now turns to US inflation data and a busy earnings calendar, which will determine whether the rally can continue toward fresh record highs.
Bond yields and crude call the shots for ASX 200
The ASX 200 has rallied on 93% of occasions this year when Australian three-year bond yields have fallen at least five basis points. With crude prices also plunging, the latest breakout has history on its side.
Gold coils for potential breakout as US CPI looms
Gold's ascending triangle is putting $4,140 firmly in focus ahead of US CPI. With traditional macro relationships offering few clues, the price action may prove more useful for traders.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.