



USD/CHF in focus as NFP beats with CPI coming up next
Well, that was quite a straightforward initial reaction in the market. But once the dust settled, we saw a quick return to pre-NFP levels on many markets, as traders realised it is the CPI – due next week – that matter more right now. Meanwhile, Trump has bizarrely suggested that the Fed should CUT rates because of the strong jobs numbers. That’s not going to happen, rest assured.
Share this:
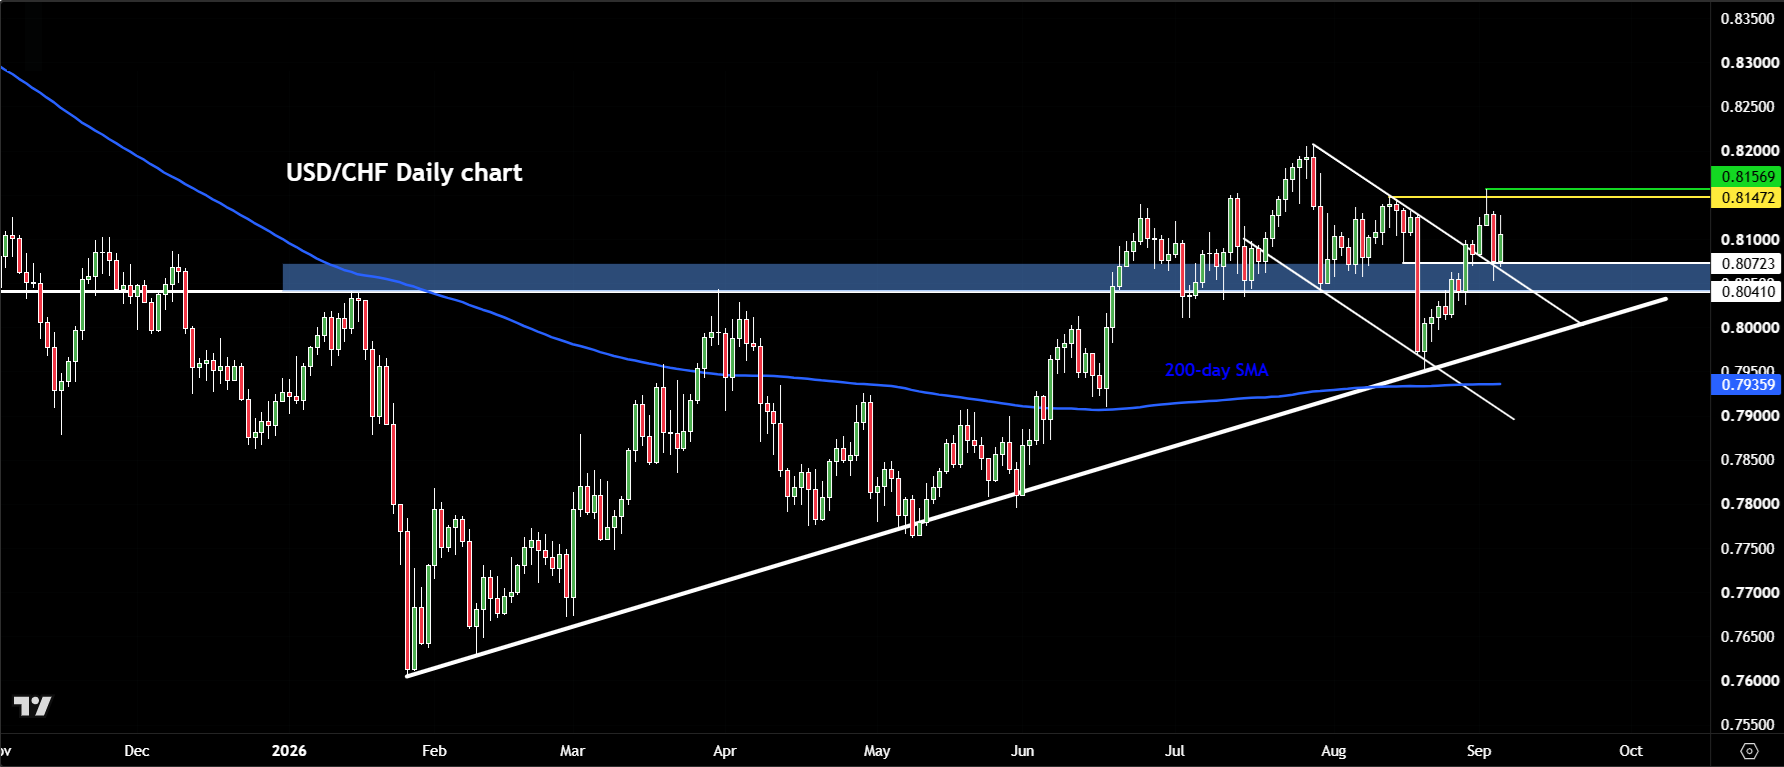
Well, that was quite a straightforward initial reaction in the market. But once the dust settled, we saw a quick return to pre-NFP levels on many markets, as traders realised it is the CPI – due next week – that matter more right now. Meanwhile, Trump has bizarrely suggested that the Fed should CUT rates because of the strong jobs numbers. That’s not going to happen, rest assured. The dollar bulls could re-emerge later especially against currencies where there is no yield advantage. Given the shenanigans in the Japanese yen market, I think the USD/CHF is the pair to keep an eye on as it could rise with the US yield advantage growing post NFP.
Anyway, the US jobs report came out much stronger than expected, for a change. And good news was bad news, I suppose, as the big beat sent rate-hike expectations soaring, causing stocks, gold and crypto to take a bit of a quick, but mini dump. Soon after, though, those moves reversed, and in some cases entirely. The bond market also fell, yields rose, and markets are now expecting the Fed to hike interest rates in September, with the probability rising to 59% from 49% before the data was released. Let’s see how the markets will take it from here on, now that we have had the usual spike and return to pre-jobs levels.
How good was the NFP data?
As far as the data is concerned, the headline number was quite strong at 162,000, compared with just 56,000 expected. That was a much better performance compared with the previous month.
Speaking of the previous month, the -23,000 figure was revised to +21,000. The net revision for the prior two months was +55,000. When you consider the revisions alongside the big beat, it was a strong number overall, and markets reacted in the way you would have expected - at least initially anyway.
The unemployment rate, meanwhile, stayed the same at 4.1%, so there were no surprises there.
Average hourly earnings came in at 0.3% month over month, again in line with expectations. However, the year-over-year rate beat expectations, coming in at 3.1% compared with 3% expected.
So that’s another sign that inflation isn’t weakening, with wage growth remaining relatively firm.
Focus turns to CPI
The focus will now turn to the US CPI report due next week. And given Fed Governor Waller’s suggestion yesterday that he will wait for the CPI data before deciding whether to vote for a hike or hold, it looks like many traders will be looking forward to that CPI release. Hence, the post-NFP reaction quickly faded as traders took profit.
Anyway, CPI is the last major piece of data before the Fed meets again in a couple of weeks’ time.
For now, it looks like a rate hike could be on the way, with the market increasing expectations of such an outcome.
What to expect from markets next?
So, the key question now is: will we see some weakness following the jobs report for equity and other markets sensitive to rate expectations?
Well, so far, the reaction has been interesting. US index futures were slightly higher before the data release, but they turned negative after the jobs report, not by a huge degree, but there was a bit of a pullback. However, the initial moves unwound quite quickly.
Now, it all depends on whether the market thinks a Fed hike is definitely on the cards. And to some degree, a lot will also depend on the price of oil, which has weakened today but has been going up over the last few days.
So, keep an eye on oil prices, as they could have an important impact on market sentiment.
As far as the US dollar is concerned, the initial reaction was a positive one, as you would have expected.
Interestingly, though, the USD/JPY remained heavy. It couldn’t move much above 156.00 initially, and after the data was released, it quickly sold off, suggesting there was perhaps some continuing intervention in that market.
Elsewhere, EUR/USD fell below the 1.1600 handle, reaching a low so far of around 1.1580 to 1.1585, before bouncing back from there at the time of writing to reach near pre-data levels of 1.1615. Gold also fell and the bounced off its low.
The question now is whether we will see fresh losses for assets like gold, indices and bitcoin, or whether we’ll see the return of the US dollar debasement trade, where the dollar sells off despite stronger US economic data. So far, it has been the latter, but the US session has just started.
In a nutshell
So far, it’s been a fairly mild reaction to the strong jobs report. The initial reaction wasn’t too significant, suggesting that markets are perhaps waiting for next week’s CPI release before deciding whether to punish the dollar or buy it more decisively. The jury is still out.

Related tags:

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.

USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.


Gold, silver slammed as hawkish Fed repricing reignites dollar upside
Gold and silver had held up surprisingly well against surging US yields. Wednesday’s DXY breakout may have changed that equation.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.