


Weekly COT Report: Sterling extends short-covering rally
The British pound was the only major to close higher against the greenback last week, and speculative positioning suggests short covering remains the main driver.
Share this:
As of Tuesday 4th January 2022
- Traders trimmed their net-long exposure to the US dollar by -$0.27 billion, taking bullish exposure down slightly to +$19.5 billion
- Long exposure to the US dollar rose to its highest level since October 2019 (although it is just at a 5-week high if adjusted for open interest)
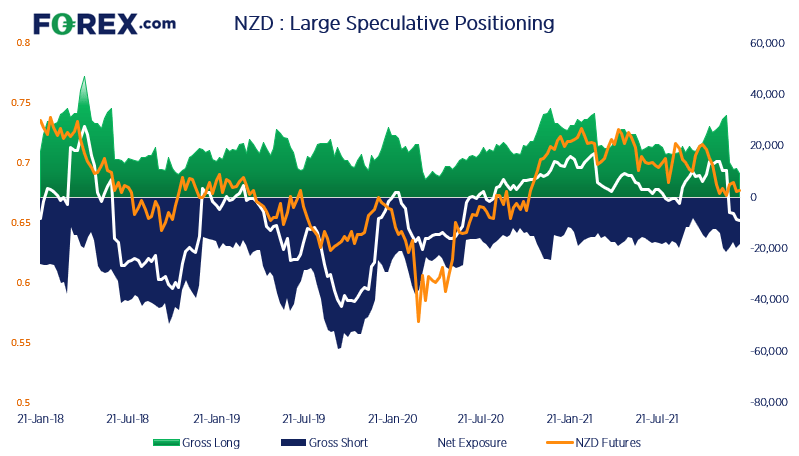
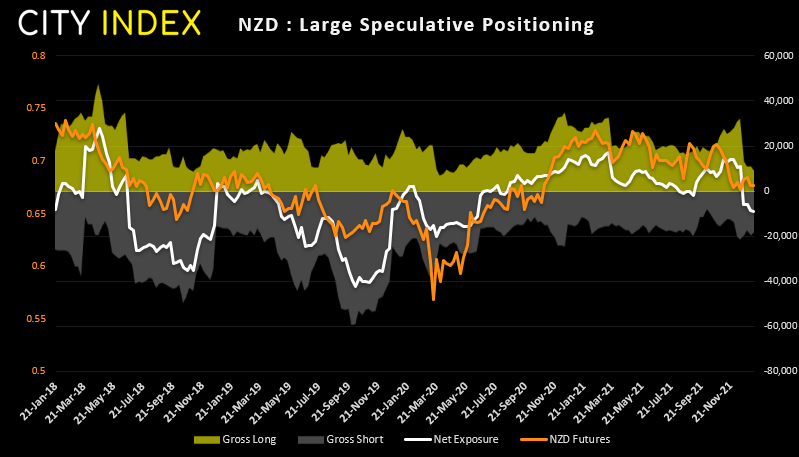
- NZD futures were net short for a fourth week and traders were their most bearish on the Kiwi dollar since June 2020
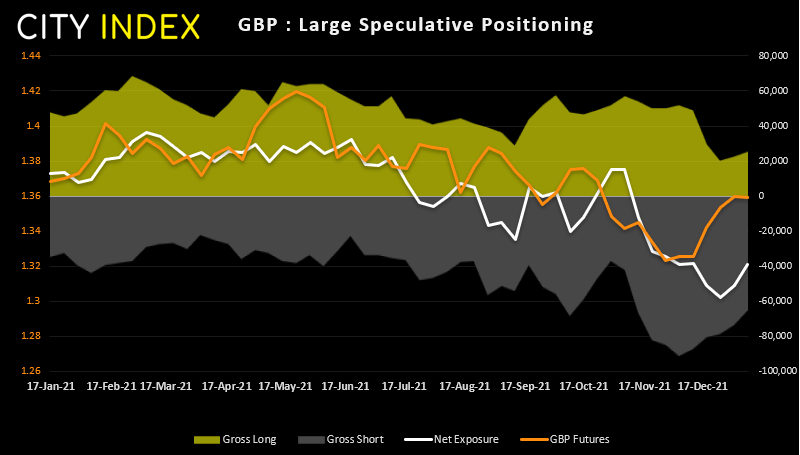
- Short exposure to GBP futures fell for a second consecutive week as its short-covering rally resumed
Sterling extends short-covering rally for a second week
Traders remain net-short GBP futures, as they have done for over 9-weeks now. Yet more may be gleaned from looking at the inflection point of gross short exposure, as bearish positioning appeared to hit a sentiment extreme back in early December. Gross shorts have been trimmed for five consecutive weeks, and gross longs have been increased the past two as prices have rallied. So GBP now appears to be in a corrective phase on the weekly chart as traders reconsider their grim view of the Omicron variant, as it may not turn out to be as dire as originally feared one month ago.
Traders remain pessimistic on the Kiwi dollar
Considering RBNZ remain a relatively hawkish central bank it’s a little surprising to see NZD at net-short exposure with large speculators. But then we do have a hawkish Fed to contend with over the coming months, at which point we suspect yield differentials will matter again and favour NZD over USD. Over the near-term we note that gross shorts sit around 20k contract, and this is a level which has held fairly steady since November, so we have an initial clue that bears could being to lose momentum. That said, gross longs are also at their lowest level since April 2020 (and trending lower) so we’d want to see a pickup of long interest before calling a reversal on the weekly charts, but this is something to consider over the coming weeks or months.
As of Tuesday 4th January 2022
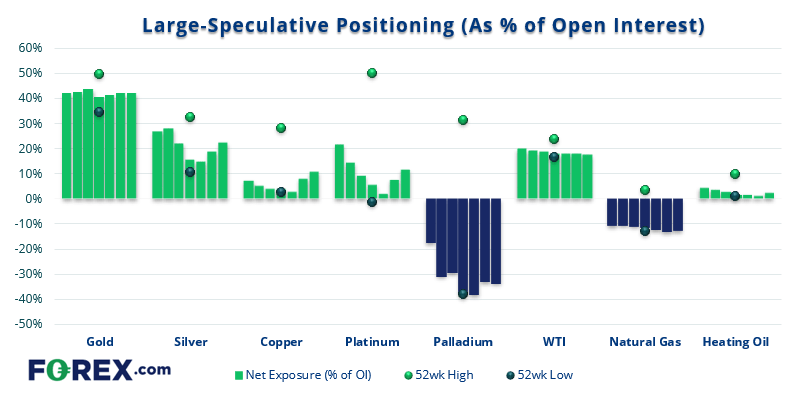
- Net-long exposure to copper futures rose for a second consecutive week
- Traders increased net-long exposure to silver futures to a 5-week high, although bearish price action since the report was compiled suggests many (if not all of these new longs) have been closed out
- Bullish interest also rose on platinum futures, with net-long exposure rising to a 6-week high
Copper bulls return to the table?
As noted above, net-long exposure to copper futures rose for a second consecutive week. Whilst it is still early days, we like how gross shorts have remained steady (lack of fresh bearish interest), and how the renewed bullish interest backs up our longer-term view that a base has been built around $4 in August and e we anticipate a breakout from its multi-month sideways range. What we would like to see in the weeks ahead to reaffirm this view is for bearish interest to decline whilst new longs continue to be initiated.
As of Tuesday 4th January 2022
- Traders trimmed their net-long exposure to the US dollar by -$0.27 billion, taking bullish exposure down slightly to +$19.5 billion
- Long exposure to the US dollar rose to its highest level since October 2019 (although it is just at a 5-week high if adjusted for open interest)
- NZD futures were net short for a fourth week and traders were their most bearish on the Kiwi dollar since June 2020
- Short exposure to GBP futures fell for a second consecutive week as its short-covering rally resumed
This content will only appear on Forex websites! Read our guide on how to interpret the weekly COT report
Sterling extends short-covering rally for a second week
Traders remain net-short GBP futures, as they have done for over 9-weeks now. Yet more may be gleaned from looking at the inflection point of gross short exposure, as bearish positioning appeared to hit a sentiment extreme back in early December. Gross shorts have been trimmed for five consecutive weeks, and gross longs have been increased the past two as prices have rallied. So GBP now appears to be in a corrective phase on the weekly chart as traders reconsider their grim view of the Omicron variant, as it may not turn out to be as dire as originally feared one month ago.
Traders remain pessimistic on the Kiwi dollar
Considering RBNZ remain a relatively hawkish central bank it’s a little surprising to see NZD at net-short exposure with large speculators. But then we do have a hawkish Fed to contend with over the coming months, at which point we suspect yield differentials will matter again and favour NZD over USD. Over the near-term we note that gross shorts sit around 20k contract, and this is a level which has held fairly steady since November, so we have an initial clue that bears could being to lose momentum. That said, gross longs are also at their lowest level since April 2020 (and trending lower) so we’d want to see a pickup of long interest before calling a reversal on the weekly charts, but this is something to consider over the coming weeks or months.
As of Tuesday 4th January 2022
- Net-long exposure to copper futures rose for a second consecutive week
- Traders increased net-long exposure to silver futures to a 5-week high, although bearish price action since the report was compiled suggests many (if not all of these new longs) have been closed out
- Bullish interest also rose on platinum futures, with net-long exposure rising to a 6-week high
Copper bulls return to the table?
As noted above, net-long exposure to copper futures rose for a second consecutive week. Whilst it is still early days, we like how gross shorts have remained steady (lack of fresh bearish interest), and how the renewed bullish interest backs up our longer-term view that a base has been built around $4 in August and e we anticipate a breakout from its multi-month sideways range. What we would like to see in the weeks ahead to reaffirm this view is for bearish interest to decline whilst new longs continue to be initiated.

How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Latest market news
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Analysis: XAU/USD Ends the Week Without a Clear Trend
The trading week is coming to an end, and a sense of neutrality remains evident around gold's short-term price action. Over the last five trading sessions, the metal has posted a move of barely -0.3%, a situation that continues to highlight a growing phase of indecision and reflects a clear lack of direction across the market.
Swiss Franc Forecast: USD/CHF Seven-Week Rally Reverses From Yearly Highs 10 16 2026
A sharp rejection from fresh highs has shifted momentum in favor of USD/CHF bears, raising the stakes for a critical support test.

EUR/USD, GBP/USD Price Outlook: Can the Dollar Pullback Fuel a Bullish Rebound?
Could EUR/USD and GBP/USD be confirming a bullish rebound? The DXY’s pullback from the 103 resistance level may support a recovery in both pairs, although confirmation is still needed.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.