


AUD/USD Bears Tighten Their Grip Into AU Jobs, RBA Minutes
AUD/USD falls below 68 cents as US dollar strength and peak RBA rate expectations put Australian jobs data and RBA minutes in focus.
Share this:

After a bruising week for the Australian dollar, the focus shifts to whether domestic data can halt the sell-off or give bears another reason to press their advantage. Australian employment figures, RBA minutes and a busy calendar of Fed speakers could shape the next move in AUD/USD, with monetary policy divergence continuing to favour the US dollar.
View related analysis:
AUD/USD Outlook: Bears Eye 67 Cents Ahead of Australian Jobs and RBA Minutes
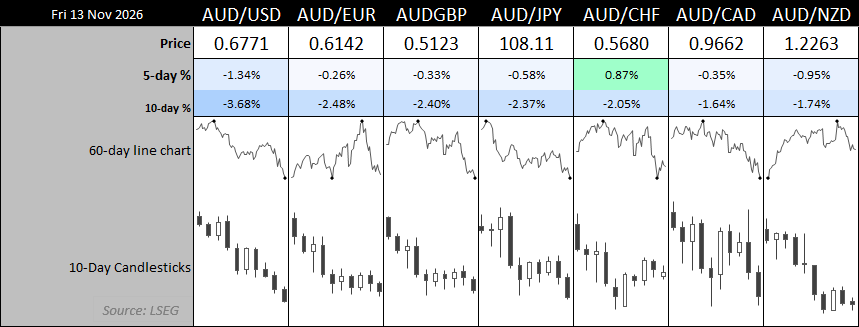
The Australian dollar was pummelled against all major currencies last week, with AUD/USD breaking beneath 0.6800 as rising Treasury yields, hawkish Fed expectations and weaker commodity prices added to the pressure. Yet the Aussie's broad-based decline suggests there was more at play than US dollar strength alone.
While the RBA raised interest rates to 4.85% earlier this month, the 6–3 decision was hardly a resounding endorsement for further tightening. And with unemployment rising, consumer sentiment at a four-year low and housing finance deteriorating, there is a growing argument that Australian interest rates have peaked.
Westpac added weight to that view on Friday, citing a weaker outlook for housing, consumer spending and employment. The recent decline in oil prices also threatens to undermine the RBA's elevated inflation projections, which were partly driven by higher energy costs associated with the Iran war.
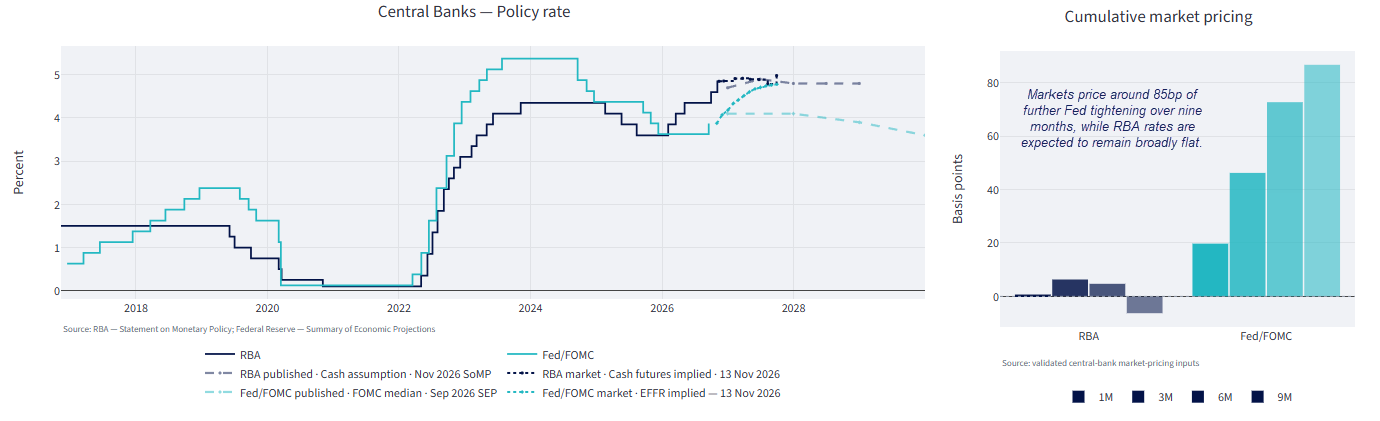
That leaves AUD/USD facing an interesting policy divergence between the two central banks. While markets continue to price further Fed tightening, the RBA may have already delivered its final hike. Whether this week's Australian wages and employment figures reinforce that view could determine if AUD/USD extends its decline or finds some much-needed support.
Traders should also keep an eye on headlines from the Middle East. Reports over the weekend suggest Bahrain intercepted Iranian aerial attacks for the first time since September. Any renewed rally in crude oil prices could revive inflation expectations and complicate the case for peak RBA rates.
AUD/USD Economic Calendar: Fed, RBA and Australian Jobs in Focus
Fed Speakers and FOMC Minutes
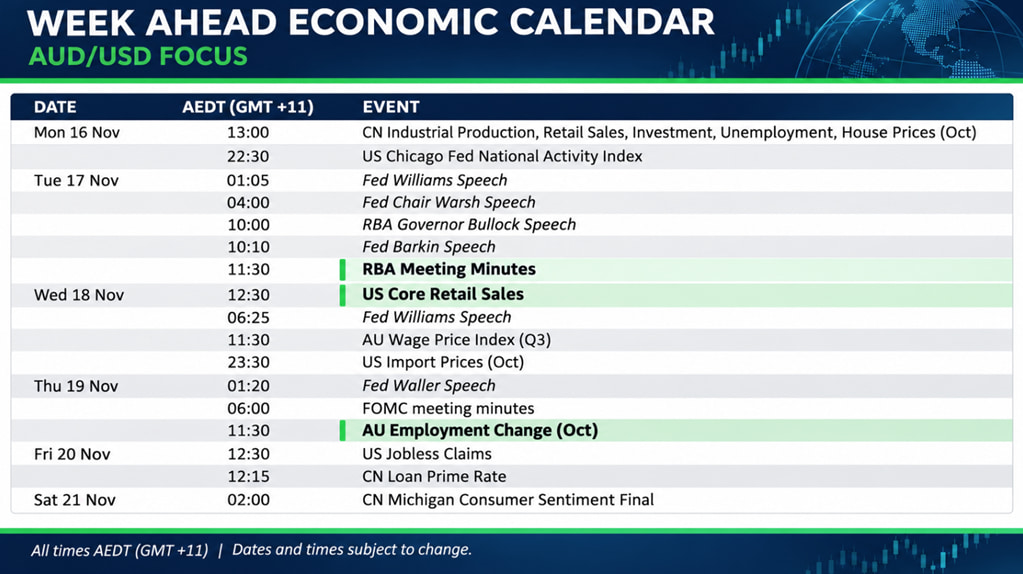
It is a busy week for Fed speakers, including Fed Chair Warsh, Williams and Waller. With markets having aggressively repriced their expectations for further Fed tightening, traders will be particularly sensitive to any comments that reinforce or challenge the hawkish narrative.
Thursday's FOMC minutes will also be closely scrutinised for clues about the appetite for further hikes, particularly whether policymakers are becoming more concerned about persistent inflation or the risks to economic growth.

RBA Minutes and Bullock Speech
The RBA's November meeting minutes arrive on Tuesday, shortly after Governor Bullock's scheduled appearance. With three of the nine board members voting against November's hike, the minutes could reveal just how close the RBA is to ending its tightening cycle.
Any comments from Bullock suggesting the RBA is comfortable assessing the impact of previous hikes could reinforce expectations that Australian interest rates have peaked. Conversely, a renewed focus on inflation risks could provide some much-needed support for the Australian dollar.
Australian Employment: Unemployment Nears RBA's Projected Peak
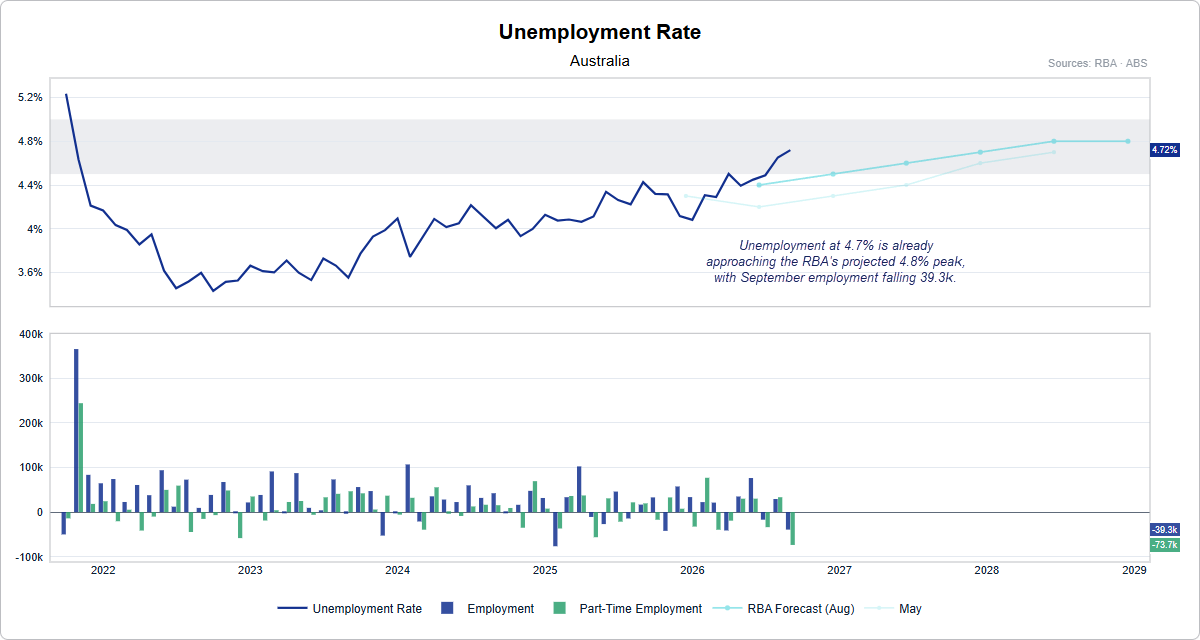
Australia's unemployment rate has crept up to 4.7%, just shy of the RBA's projected peak of 4.8%. And with employment falling by 39.3k in September, driven by a sharp 73.7k decline in part-time jobs, there are signs that the labour market is losing momentum.
Thursday's employment report will therefore be particularly important. Another weak print, or a rise in unemployment towards 5%, could strengthen the argument that the RBA has already delivered its final hike and add further pressure to the Australian dollar.
China Data, Australian Wages and US Retail Sales
China's industrial production, retail sales and investment figures kick off the week on Monday. With concerns over China's domestic demand resurfacing, another soft set of figures could weigh on the Australian dollar and commodity prices.
Australia's wage price index is due Wednesday, with stronger wage growth potentially complicating the case for peak RBA rates. US retail sales and industrial production will also provide an update on the resilience of the world's largest economy, while Friday's final University of Michigan consumer sentiment survey could attract attention if inflation expectations surprise.
AUD/USD Technical Analysis: Bears Eye 67 Cents
I warned last week that the US dollar appeared set to surge higher, and it did not disappoint, with DXY closing above 103 at a 20-month high. With no imminent signs of a top, the trend is assumed to be our friend – to the detriment of the Australian dollar.
AUD/USD bears made light work of breaking beneath the March low, and the pair now finds itself below 68 cents for the first time since January. The lower one-week implied volatility band sits just above 67 cents, and unless the USD wants to top out any time soon, AUD/USD could reach that next milestone by the end of the week at current volatility levels.
The March low (0.6832) and July low (0.6863) are potential areas for bears to fade a bounce, should the Aussie recover that far. The only things seemingly in favour of AUD/USD bulls right now is that the AU-YS 2yr spread and risk reversals have held above their own recent swing lows, though neither are they providing any compelling buy signals.
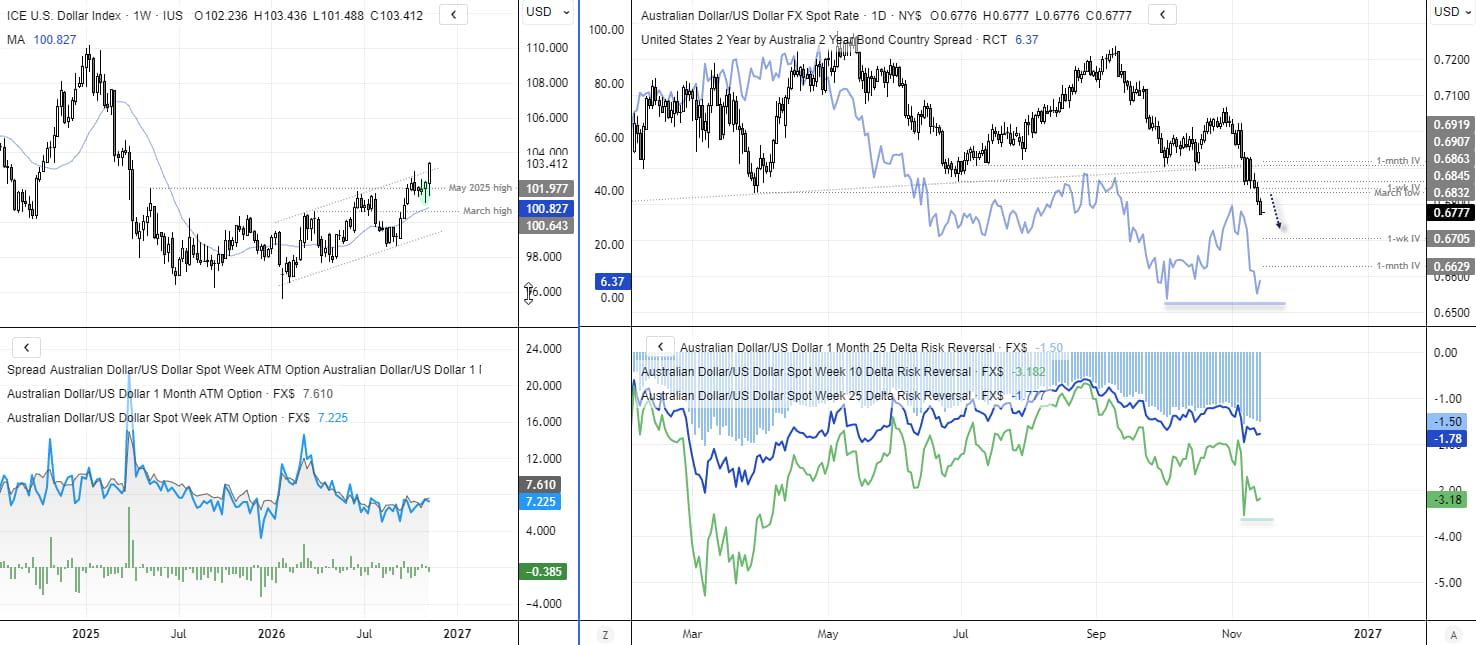
Source: ICE, TradingView
AUD/USD Correlations: US Dollar and Commodities Dominate
- US dollar remains the dominant driver: AUD/USD's inverse correlation with DXY strengthened to -0.98 over 10 days, reinforcing the bearish outlook while the dollar remains strong.
- Commodities remain closely aligned: Copper, gold and iron ore all have strong positive 10-day correlations of 0.94 or higher. The broader CRB index also remains strongly correlated across all periods.
- Chinese yuan offers some confirmation: CNH/USD maintains positive correlations over 10 and 20 days (0.61 and 0.79), although its weaker 60-day relationship suggests it is not a consistently reliable driver.
- Equity relationships remain mixed: AUD/USD has a strong inverse 20-day correlation with the ASX 200 (-0.87), while its relationship with the S&P 500 remains relatively weak. Traditional risk-on signals are less reliable.
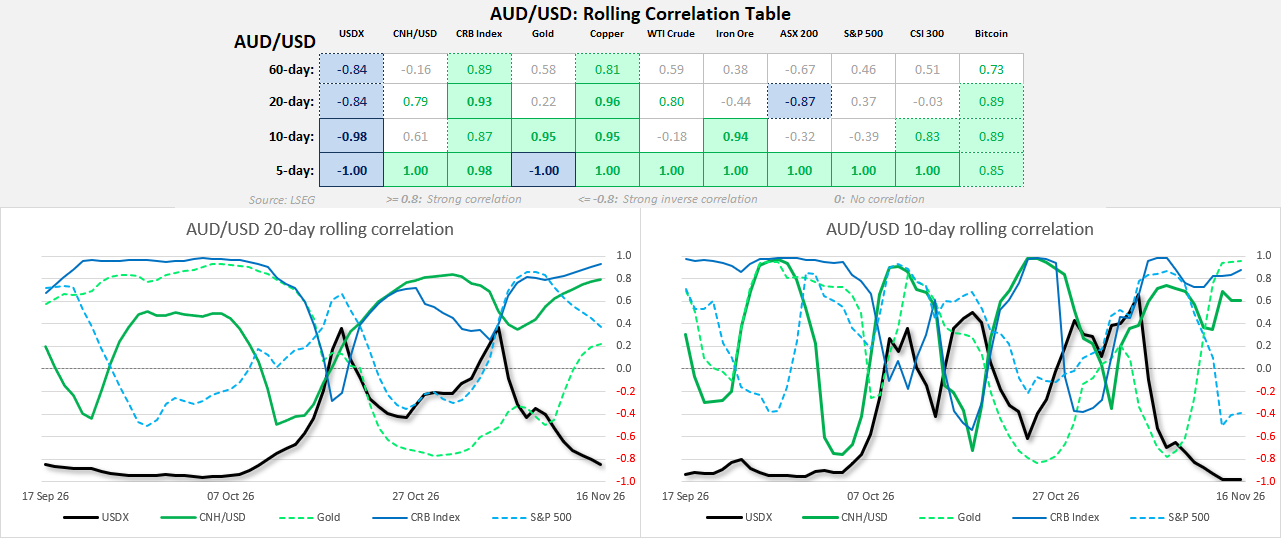
Source: LSEG
Related tags:
Latest market news


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
AUD/USD Bears Tighten Their Grip Into AU Jobs, RBA Minutes
AUD/USD falls below 68 cents as US dollar strength and peak RBA rate expectations put Australian jobs data and RBA minutes in focus.
Australian Dollar Forecast: AUD/USD Breaks Multi-Month Range, Hits 10-Month Low 11 14 2026
Aussie bears are closing in on major technical support, with next week's Australian employment data raising the stakes for a pivotal reaction.

USD/JPY Weekly Outlook: Bulls Eye Higher Range After Historic Rate Shock
A historic US rate shock has sent USD/JPY above 160, but with intervention risks rising and few major economic catalysts ahead, AI sentiment could hold the key to the next move.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.