



Market Brief DJIA Rallies for Seventh Straight Day Longest Streak in Over a Year
See a summary of the top market themes and trends from today's US trading session!
Share this:


- In its highly-anticipated monetary policy meeting, the ECB cut deposit rates by 10bps to -0.5%, reintroduced QE (with no end date!), and introduced a tiering system for banks – see our initial review of the decision. The central bank also cut growth and inflation forecasts.
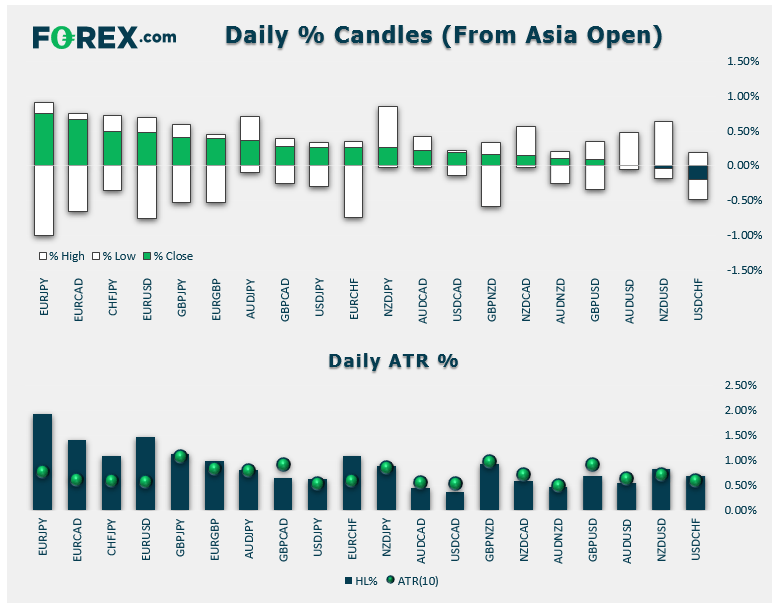
- FX: After an initial drop, the euro rallied back to become the strongest major currency on the day in a classic “sell the rumor, buy the news” dynamic around the ECB. The Japanese yen was the weakest major currency.
- Optimism about a possible interim US-China trade deal to delay tariffs boosted risk appetite (though that rumor was subsequently denied by a White House spokesperson)
- US data: August CPI came in softer than expected at 1.7% y/y vs. 1.8% eyed, while initial jobless claims met expectations at 204k.
- Commodities: Gold ticked higher while Oil shed over 1% on the day.

- US indices traded higher across the board, marking the seventh straight rally for the Dow Jones Industrial average. This is the longest winning streak since last May.
- Financials (XLF) were the strongest sector while Energy (XLE) was the weakest, hurt by the drop in oil prices.
- Stocks on the move:
- Oracle (ORCL) gained 1% after co-CEO Mark Hurd announced he would take a leave of absence for health reasons.
- Car rental firm Hertz Global Holdings (HTZ) gained 20% after billionaire investor Carl Icahn increased his stake in the company above 30%.
- New IPO SmileDirectClub dropped -28% in its first day of trading.
- In its highly-anticipated monetary policy meeting, the ECB cut deposit rates by 10bps to -0.5%, reintroduced QE (with no end date!), and introduced a tiering system for banks – see our initial review of the decision. The central bank also cut growth and inflation forecasts.
- FX: After an initial drop, the euro rallied back to become the strongest major currency on the day in a classic “sell the rumor, buy the news” dynamic around the ECB. The Japanese yen was the weakest major currency.
- Optimism about a possible interim US-China trade deal to delay tariffs boosted risk appetite (though that rumor was subsequently denied by a White House spokesperson)
- US data: August CPI came in softer than expected at 1.7% y/y vs. 1.8% eyed, while initial jobless claims met expectations at 204k.
- Commodities: Gold ticked higher while Oil shed over 1% on the day.

- US indices traded higher across the board, marking the seventh straight rally for the Dow Jones Industrial average. This is the longest winning streak since last May.
- Financials (XLF) were the strongest sector while Energy (XLE) was the weakest, hurt by the drop in oil prices.
- Stocks on the move:
- Oracle (ORCL) gained 1% after co-CEO Mark Hurd announced he would take a leave of absence for health reasons.
- Car rental firm Hertz Global Holdings (HTZ) gained 20% after billionaire investor Carl Icahn increased his stake in the company above 30%.
- New IPO SmileDirectClub dropped -28% in its first day of trading.

Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY weekly outlook: Quarter turn scrambles rates regime
USD/JPY’s tight relationship with front-end US rates broke down sharply last week, but quarter-turn flows and positioning suggest the disconnect may prove temporary.


USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.


USD Sets Fresh Yearly High as EUR/USD Drops Dramatically, USD/JPY Stable
Well, it was a week of USD strength that wasn’t entirely pushed by USD/JPY, as a strong sell-off in EUR/USD has pushed the major pair to its most oversold state in a decade.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.