




Rio Tinto bullish for 2020
Rio Tinto, along with the FTSE350 mining index as a whole, has had a roller coaster year.
Share this:

Rio Tinto, along with the FTSE350 mining index as a whole, has had a roller coaster year.
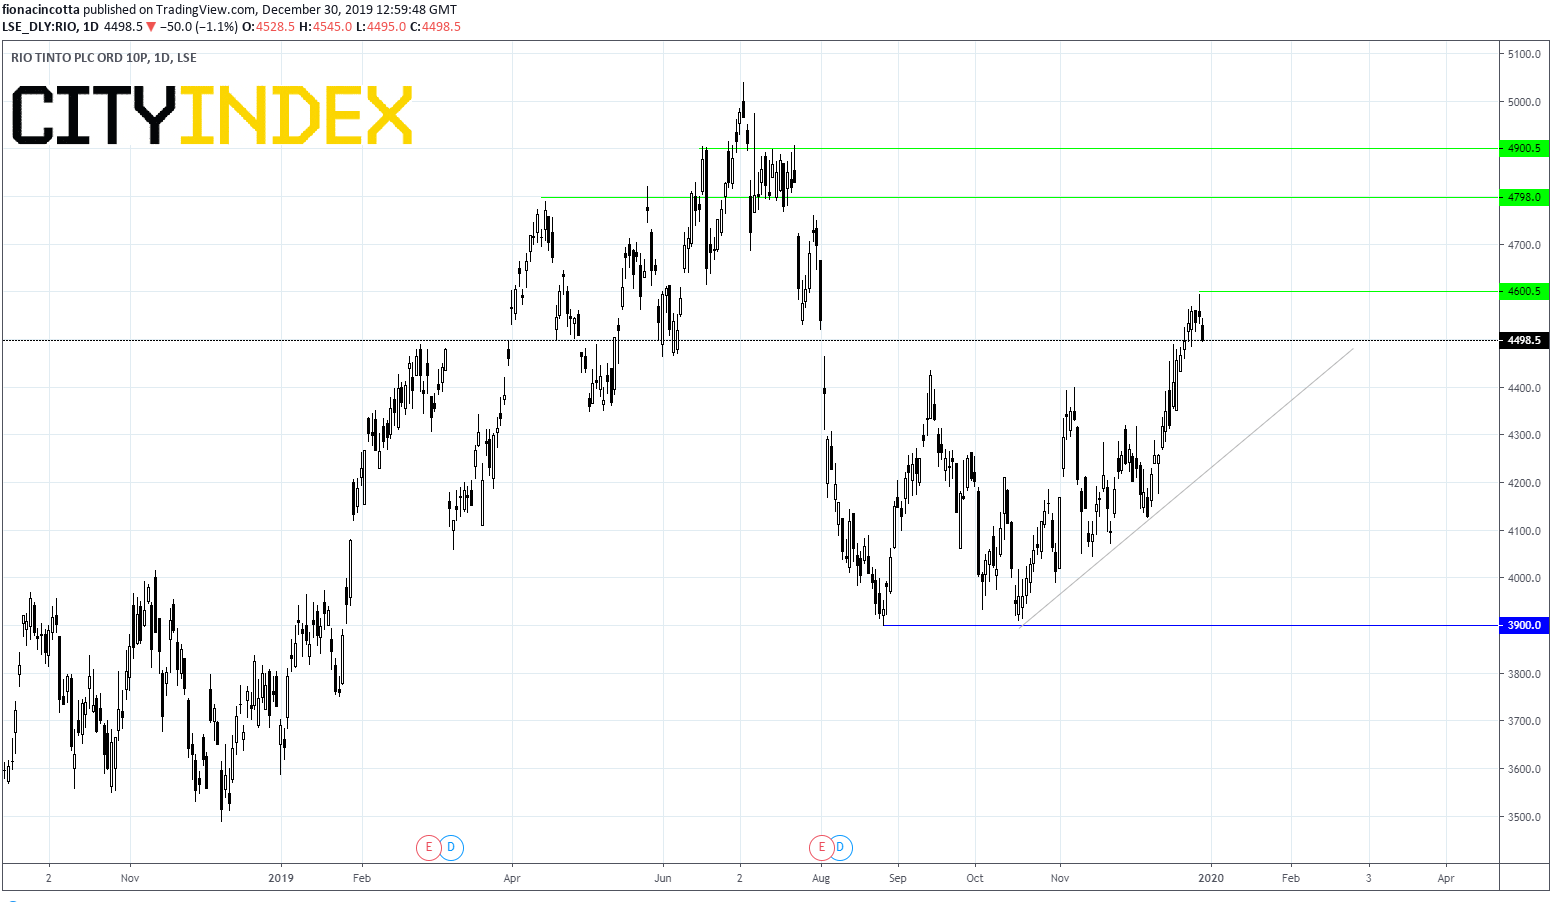
Rio Tinto rallied an impressive 39% across the start of the year, hitting an all-time high of 5039 in early July on rising commodity prices. The stock slumped across the summer months amid elevated US – China trade tensions and has since put in a bit of a rebound as global risks, particularly US – China trade tensions have eased towards the end of 2019.
Rio Tinto is ending 2019 up 27%, outperforming the FTSE100 which gained 12%. With the US - China first phase trade deal potentially being signed in early 2020 Rio Tinto could have more upside.
Metals for the global economy
The three metals that the global economy needs the most are iron ore (an important component of steel which is used in construction, cars, machinery etc), aluminium and copper. The importance of these metals plays right into Rio Tinto’s hand, as it is a global leader in iron ore production, a leader in aluminium and in the top 10 producers of copper.
When the global economy is growing strongly and the prospect of further growth is high, demand and the demand outlook for these metals increases, boosting prices and lifting the share price of the miners.
As trade tensions eased between US and China, and the outlook for the global economy improved and Rio Tinto pushed higher, benefitting greatly from the recent rebound in commodity prices, most notably iron ore.
Low production costs
Production costs are incredibly low. At the flagship Pilbara mines production costs are under $15 a tonne, average market prices were five times higher in the region of $80 per tonne. Mining and then selling on for 5 times the cost is always an attractive proposition.
Low net debt
Rewind 3 to 4 years and Rio Tinto had a mountain of debt and embarked on a brutal cost cutting exercise, the benefits of which are apparent today. Rio has $4.9 billion of net debt as from mid 2019, which is small given its $95 billion enterprise value.
With debt back under control Rio is free to use the cash flow it generates to give back to shareholders and reinvest to grow the business.
Risks
Given that Rio is heavily reliant on iron ore (62% of underlying EBITDA) it’s high exposure to that market can also be a risk. Should the price off iron ore weaken, Rio Tinto would be more at risk than other diversified miners.
Conclusion
Rio Tinto has a lot to offer as the outlook for the global economy improves. Low production costs of key industrial metals and low debt levels mean it is well positioned to prosper.
Rio Tinto, along with the FTSE350 mining index as a whole, has had a roller coaster year.
Rio Tinto rallied an impressive 39% across the start of the year, hitting an all-time high of 5039 in early July on rising commodity prices. The stock slumped across the summer months amid elevated US – China trade tensions and has since put in a bit of a rebound as global risks, particularly US – China trade tensions have eased towards the end of 2019.
Rio Tinto is ending 2019 up 27%, outperforming the FTSE100 which gained 12%. With the US - China first phase trade deal potentially being signed in early 2020 Rio Tinto could have more upside.
Metals for the global economy
The three metals that the global economy needs the most are iron ore (an important component of steel which is used in construction, cars, machinery etc), aluminium and copper. The importance of these metals plays right into Rio Tinto’s hand, as it is a global leader in iron ore production, a leader in aluminium and in the top 10 producers of copper.
When the global economy is growing strongly and the prospect of further growth is high, demand and the demand outlook for these metals increases, boosting prices and lifting the share price of the miners.
As trade tensions eased between US and China, and the outlook for the global economy improved and Rio Tinto pushed higher, benefitting greatly from the recent rebound in commodity prices, most notably iron ore.
Low production costs
Production costs are incredibly low. At the flagship Pilbara mines production costs are under $15 a tonne, average market prices were five times higher in the region of $80 per tonne. Mining and then selling on for 5 times the cost is always an attractive proposition.
Low net debt
Rewind 3 to 4 years and Rio Tinto had a mountain of debt and embarked on a brutal cost cutting exercise, the benefits of which are apparent today. Rio has $4.9 billion of net debt as from mid 2019, which is small given its $95 billion enterprise value.
With debt back under control Rio is free to use the cash flow it generates to give back to shareholders and reinvest to grow the business.
Risks
Given that Rio is heavily reliant on iron ore (62% of underlying EBITDA) it’s high exposure to that market can also be a risk. Should the price off iron ore weaken, Rio Tinto would be more at risk than other diversified miners.
Conclusion
Rio Tinto has a lot to offer as the outlook for the global economy improves. Low production costs of key industrial metals and low debt levels mean it is well positioned to prosper.




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
SK Hynix IPO: Everything You Need to Know About SK Hynix
Learn everything you need to know about the SK Hynix IPO, including its Nasdaq listing, valuation, financials, ownership, competitors and investment risks.

FTSE 100 and GBP/USD forecast: UK data gives BoE March cut a further boost
The FTSE 100 edged higher to close in on last week’s record, as the pound weakened following the release of UK wages and Jobs data that puts a March rate cut firmly on the table, barring any surprises in tomorrow’s inflation report. Unless we see a sharp turnaround in data, I would be expecting another rate cut in June, and possibly more in the summer if inflation risks ease. This should keep the longer term FTSE 100 forecast firmly supported and keep a lid on sterling.

FTSE 100 forecast - Indices weekend outlook | February 16, 2026
With the US out on Monday for Presidents’ Day and China celebrating Spring Festival all week, it makes sense to focus on European markets to start the week off. So the FTSE 100 forecast is in focus for this week’s weekend indices outlook. We have plenty of UK, European and US earnings to look forward to as the week progresses, while key data from the UK and US will make rate cut expectations a key talking point on both sides of the pond.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.