



Asian Open: Oil prices are firing on all cylinders
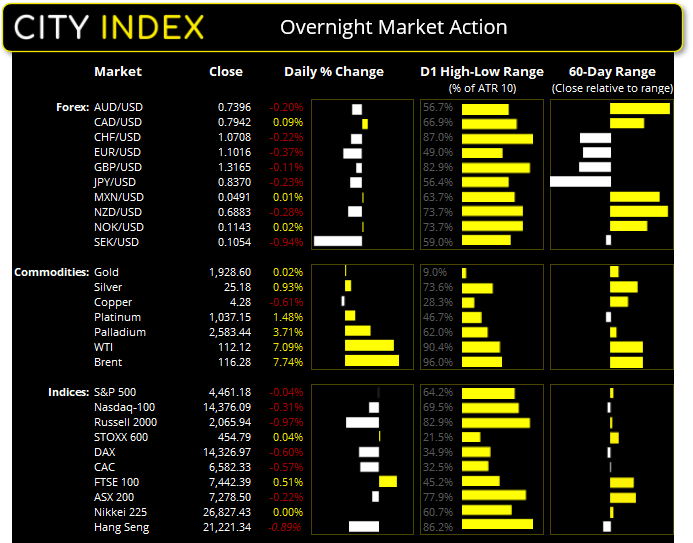
WTI and brent rose over 7% overnight as the pressure for Europe to ban Russian oil imports intensified.
Share this:

US Friday close:
- The Dow Jones fell -201.94 points (-0.58%) to close at 34,552.99
- The S&P 500 fell -1.94 points (-0.05%) to close at 4,461.18
- The Nasdaq 100 fell -43.991 points (-0.31%) to close at 14,376.09
Asian Indices:
- Australia’s ASX 200 index closed at 7,278.50 on Friday
- Japan's Nikkei 225 index closed at 26,827.43 on Friday
- Hong Kong's Hang Seng index closed at 21,221.34 on Friday
- China'sA50 Index closed at 13,725.45 on Friday
European Friday close:
- UK's FTSE 100 index rose 37.66 points (0.51%) to close at 7442.39
- Europe's Euro STOXX 50 index fell -20.64 points (-0.53%) to close at 3881.8
- Germany's DAX index fell -86.12 points (-0.6%) to close at 14326.97
- France's CAC 40 index fell -37.91 points (-0.57%) to close at 6582.33
The Pentagon says there is “clear evidence that Russian forces are committing war crimes” and accused the Kremlin of indiscriminate attacks within Ukraine. However, whilst the Pentagon will continue to help collect evidence of such crimes they also said it is not up to them as to what will come of it. In response, Russia has told the US that relations between the two are ‘on the verge of collapse’.
The US state department also confirmed a meeting between US and Russian ambassadors took place, where the US demanded Moscow follows international law. A NATO official has warned that Belarus may soon attack Ukraine, and that Belarus are potentially preparing to let Russia place nuclear weapons in their country.
Headlines overnight were enough to take the steam out of Wall Street’s rally, but not enough to turn the tide with the S&P 500 effectively flat at -0.4% lower and the Nasdaq closing just -0.3% lower.
Commodities rise with geopolitical tensions
Overall, commodities rose in tandem. The Thomson Reuters commodities index rose 2.5% and closed just below 300, less than a day’s trade from its 7-year high. But notable gains were seen on oil prices as European officials continued to bicker over how to deal with a Russian oil embargo. Germany’s claim to remain dependant on Russia’s energy markets, whilst another EU diplomat thing Europe could have replaced Russia’s exports by June. But whilst EU’s foreign ministers may not be on the same page regarding banning Russian oil imports, the pressure is on to do so, given the war-crime status Putin has now earned via Russia’s attack on civilians.
WTI closed above $110 and near its high of the day. Technically it is headed into several historical highs between 110.23 – 114.83 but, if the geopolitical landscape continues to heat up then such levels likely account for little.
Gold is holding above the June high around 1916 although failed to recapture losses sustained on Friday as it is caught between the safe-haven flows and threat of hawkish Fed. Silver was also higher overnight yet remains below 25.54, a break above which invalidated out near-term, bearish bias and a break beneath Friday’s low confirms it.
ASX 200:
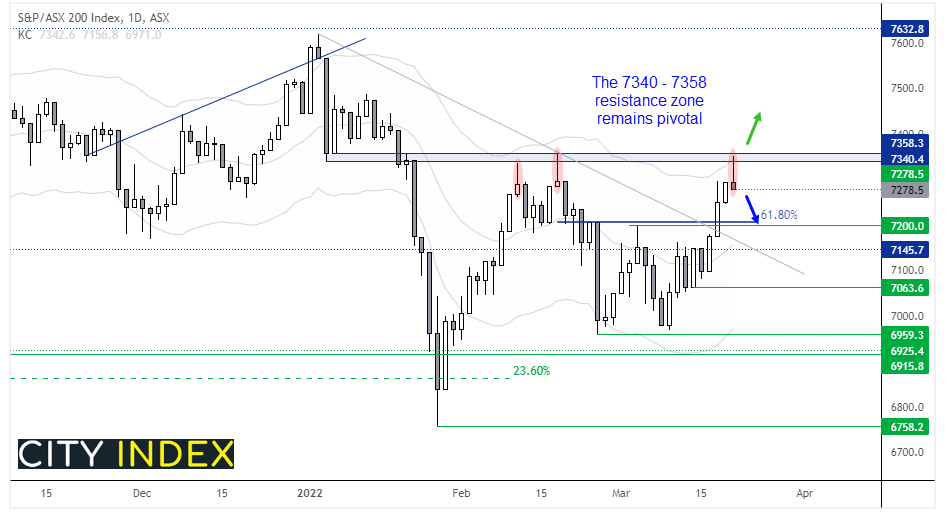
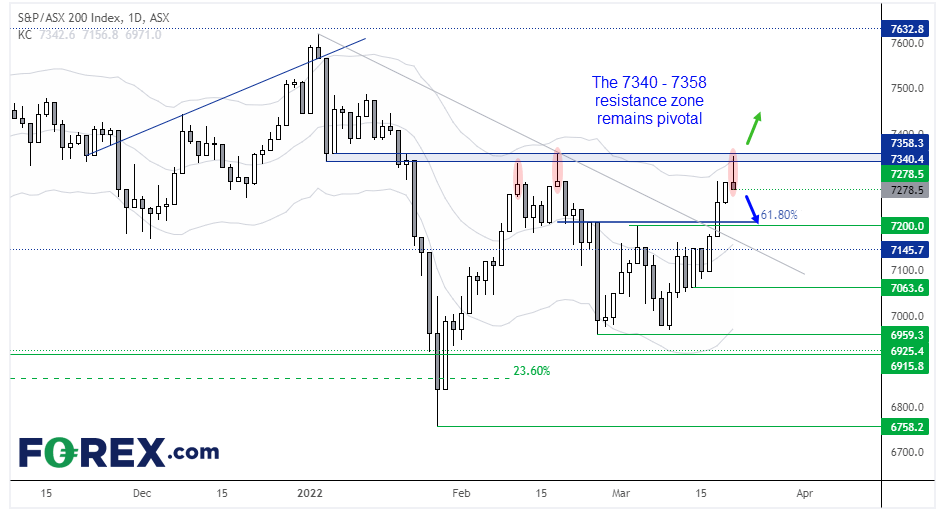
Due to the rise in energy and materials stocks overnight, the ASX 200 is expected to open higher today. But we need to see a break above 7360 to assume bullish continuation, and even then 7400 is likely to provide resistance. Therefore, we would be keen to explore a break of yesterday’s low should the opportunity arise, to mark a countertrend move. We have now seen three bearish hammers around 7340 which makes it a pivotal level (and one for bears to watch whilst prices remain below it).
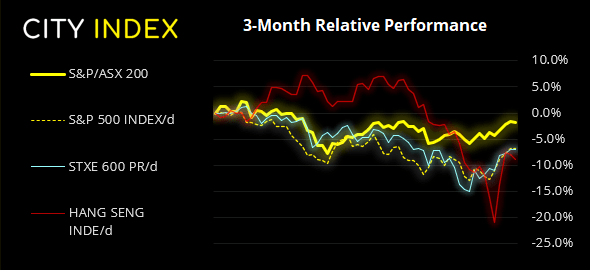
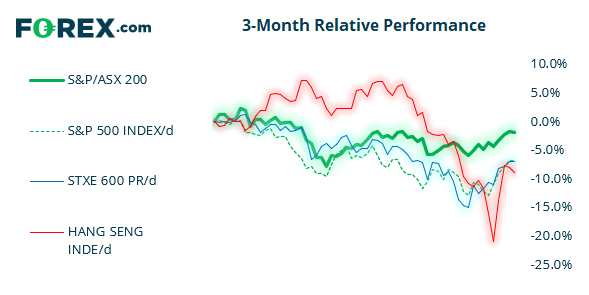
ASX 200: 7278.5 (-0.22%), 21 March 2022
- Info Tech (2.46%) was the strongest sector and Industrials (-1.24%) was the weakest
- 5 out of the 11 sectors closed higher
- 6 out of the 11 sectors closed lower
- 6 out of the 11 sectors outperformed the index
- 81 (40.50%) stocks advanced, 101 (50.50%) stocks declined
Outperformers:
- +5.42% - Liontown Resources Ltd (LTR.AX)
- +4.1% - Hyperion Global Growth Companies Class A (HYGG.AX)
- +4.06% - EBOS Group Ltd (EBO.AX)
Underperformers:
- -4.32% - Magellan Financial Group Ltd (MFG.AX)
- -3.73% - Atlas Arteria Group (ALX.AX)
- -3.57% - Imugene Ltd (IMU.AX)
Read our guide on the ASX 200 trading guide
Read our ASX 200 trading guide
Fed to raise more aggressively if required
Jerome Powell left little to interpret by saying the Fed must move “expeditiously” and potentially raise rates “more aggressively” to prevent inflation becoming entrenched at high levels. Citing a strong labour market alongside high inflation which is “much too high” it could reignite calls for a 50-bps hike in future meetings. Currently there a 59.4% chance of a 25-bps hike at their next meeting, up from 43.9% from Friday.
The US dollar index and USD/JPY rose 0.25%, AUD/USD and NZD/USD pulled back from their highs despite the rise in commodity prices. The US 10-year yielded 2.3% overnight for the first time since May 2019.
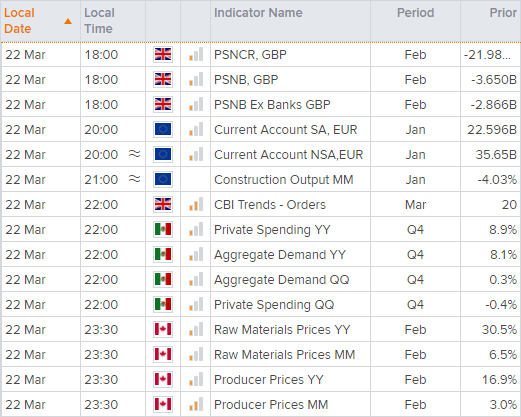
Up Next (Times in AEDT)
How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.