



Asian Open: Peace talks weigh on commodities, AUD and NZD
Supply chain concerns were so last week it seems, with a bulk of key commodity markets (including gold) moving lower.
Share this:

Monday US cash market close:
- The Dow Jones Industrial fell 105 points (0%) to close at 32,945.24
- The S&P 500 index rose -31.2 points (2.51%) to close at 34,058.75
- The Nasdaq 100 index fell -255.19 points (-1.92%) to close at 13,046.64
Asian futures:
- Australia's ASX 200 futures are down -61 points (-0.85%), the cash market is currently estimated to open at 7,088.40
- Japan's Nikkei 225 futures are up 10 points (0.04%), the cash market is currently estimated to open at 25,317.85
- Hong Kong's Hang Seng futures are down -526 points (-2.69%), the cash market is currently estimated to open at 19,005.66
- China's A50 Index futures are down -141 points (-1.07%), the cash market is currently estimated to open at 13,222.62
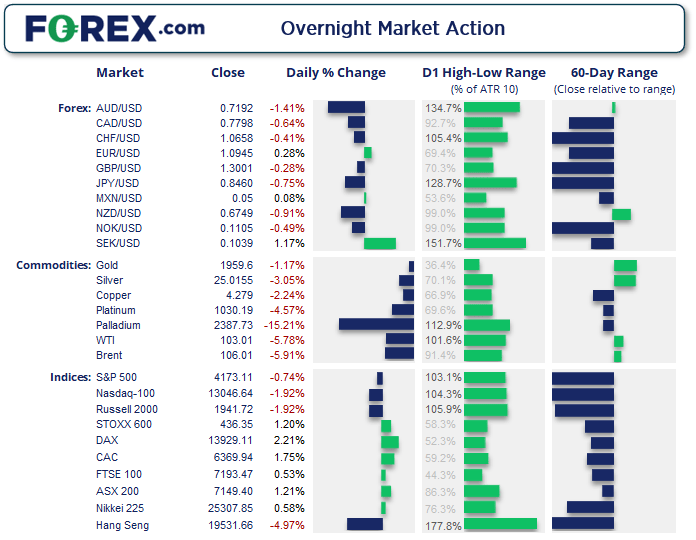
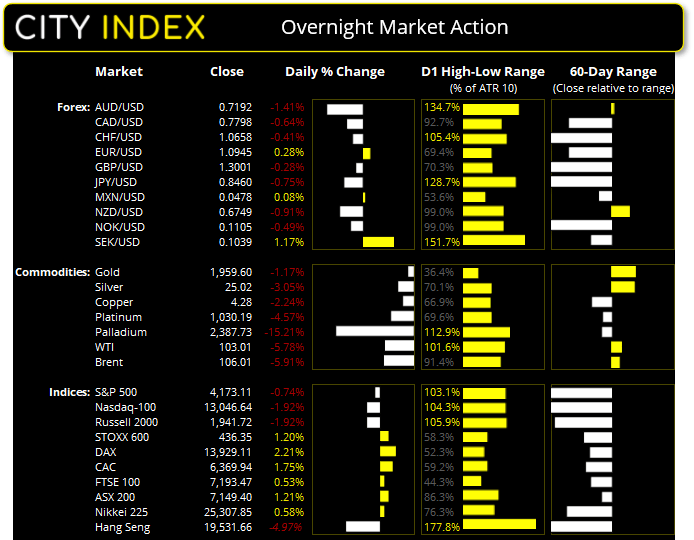
A fourth round of peace talks between Ukraine and Russian officials were held via video link overnight. Whilst they’re yet to produce any solid results, they are deemed as step in the right direction and hope remains a resolution can be found. And those hope have removed a key pillar of support for commodity prices which surged last week on supply disruption.
The US piled the pressure on China during ‘intense’ meeting in Rome to not provide military aid to Russia, with the White House warning of ‘significant consequences’ if they do. Yet despite these positive developments, Wall Street traded lower as investors were allowed to refocus their negative energy on the prospects of multiple Fed hikes.
Peace talks weigh on commodities
WTI slipped to $100, meaning it has fallen over -23% from its 14-year high set last Monday. And with that we’re now seeing calls for $50 oil – just one week after seeing calls for $200. We think both of these scenarios are far-fetched, but over the neat-term it could range around $90 - $110.
Gold fell to a 6-day low and is now down around -5.8% from last week’s high. Yet in context of its 16.4% rally from the January low, it could still be part of a healthy pullback. And trader positioning last week showed that large speculators and managed funds remain long the metal, and we doubt they’ve all gone scrambling for cover because of a small retracement.
ASX 200:
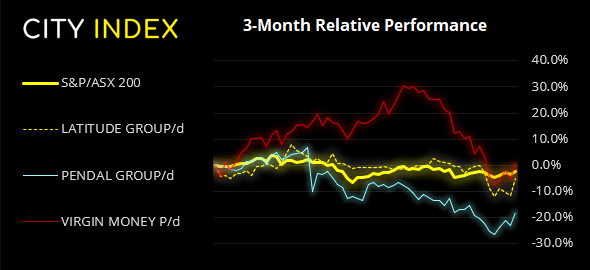
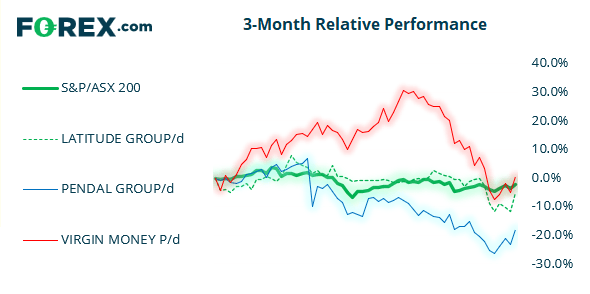
The ASX printed a gain with conviction yesterday, by opening at the day’s low and closing at the high. And with despite a weaker lead from Wall Street we suspect it can defy gravity, as it generally has done these past two weeks, and challenge 7200 today.
ASX 200: 7149.4 (1.21%), 14 March 2022
- Financial (2.46%) was the strongest sector and Materials (-0.34%) was the weakest
- 10 out of the 11 sectors closed higher
- 1 out of the 11 sectors closed lower
- 6 out of the 11 sectors outperformed the index
- 147 (73.50%) stocks advanced, 43 (21.50%) stocks declined
Outperformers:
- +7.39% - Latitude Group Holdings Ltd (LFS.AX)
- +6.56% - Pendal Group Ltd (PDL.AX)
- +6.16% - Virgin Money UK PLC (VUK.AX)
Underperformers:
- -7.47% - Paladin Energy Ltd (PDN.AX)
- -4.41% - Chalice Mining Ltd (CHN.AX)
- -4.17% - Nickel Mines Ltd (NIC.AX)
Euro rallies on peace talk hopes
Sometimes, a little can go a long way and that appeared to be the case with the stronger euro overnight. Rising across the board, euro printed bullish outside days against all majors. The US dollar was the second strongest major and traded higher against all majors except the euro, as traders refocussed on the prospects of multiple rate hikes.
AUD and NZD were dragged down with commodities and the stronger US dollar. NZD/USD fell to a 2-week low in line with yesterday’s bearish bias, and our target remains either 0.67 or trend support from the January low (whichever comes first). USD/JPY closed above 118 for the first time since January 2017 and is less than a day’s trade away from hitting a 6-year high.

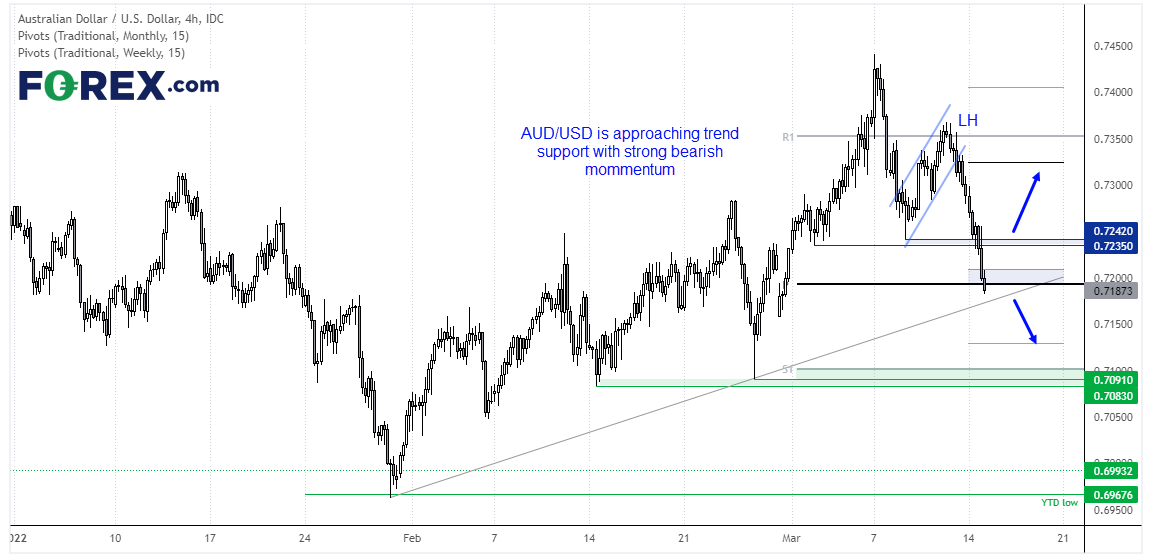
If commodities continue to weigh on the Aussie and traders remain bid the dollar, a break of trend support seems inevitable. Bearish momentum is also on its side having formed a lower high and strong impulsive move lower. Still, there chance of a ounce back above 72c but, as long as prices remains beneath the 0.7240 support zone, our bias remains bearish and for a run towards 0.7100. Whereas a break above 0.7245 invalidates our bearish bias and assumes the trendline remains valid.
Up Next (Times in AEDT)
How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.
DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.