




AUD/USD mulls 64c breakout, US yields hint at swing high post Fed
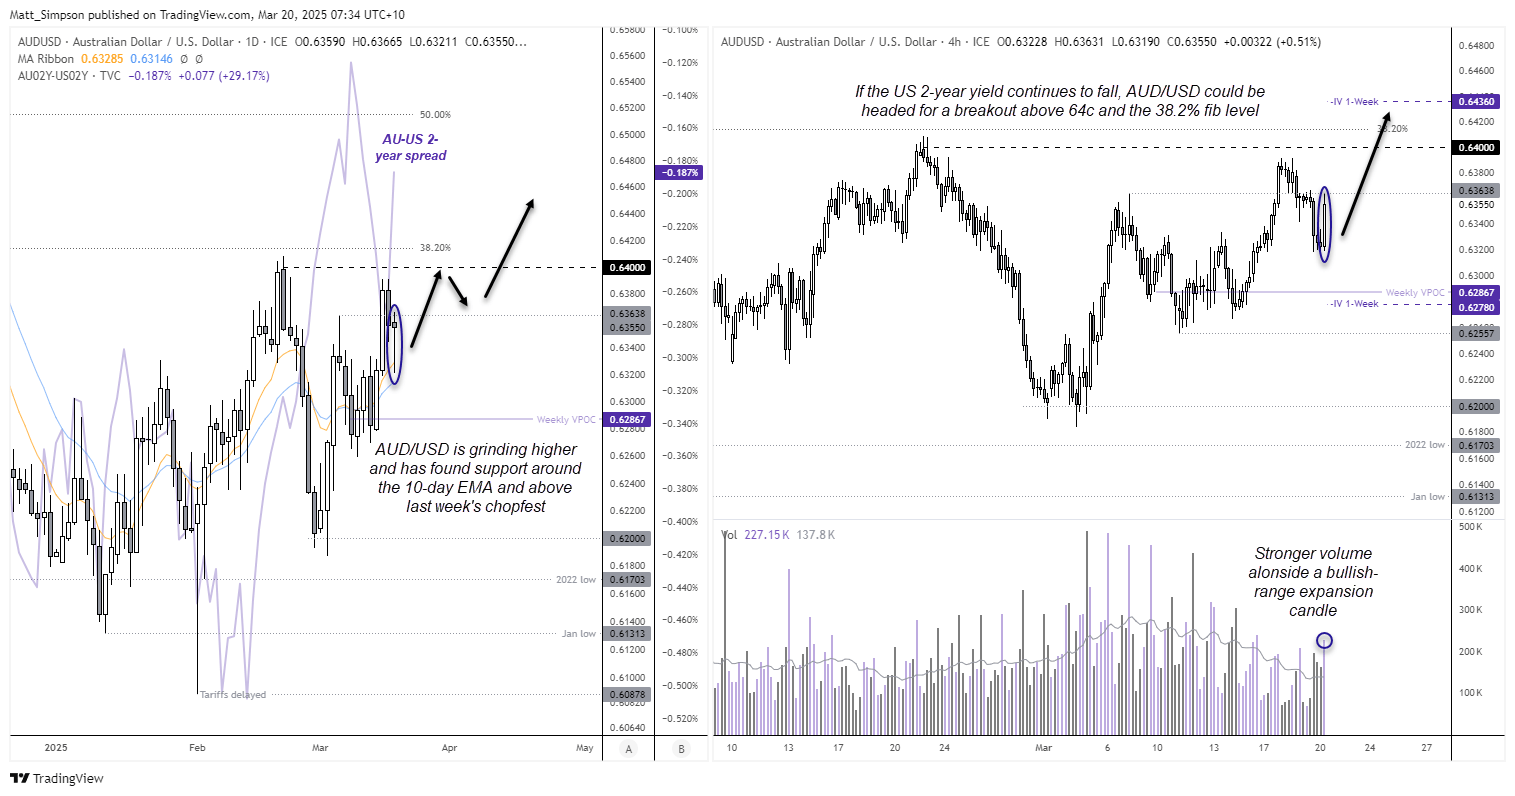
With US yields lower and hinting at a swing high, the relationship between AUD/USD and the AU-US 2-year spread appear to be back on talking terms. And that could bode well for AUD/USD bulls if US yields continue to fall in line with my bias.
Share this:
View related analysis:
- AUD/USD Forecast: FOMC, AU Jobs to Wake the Aussie Up From Its Lull?
- USD/JPY Hits Speed Bump at 150 Ahead of BOJ and FOMC, ASX to Open Lower
- Gold's Surge is Leaving Traders for Dust: Matt's 2-Minute Take
View related analysis:
While the Fed downgraded growth and upgraded their inflation forecast in light of Trump’s tariffs, they opted for a ‘wait and see’ approach regarding rates by keeping them at 3.9% for 2025, unchanged from their December forecasts. If anything, I felt they may have trimmed some easing out of the equation for this year, so from that angle it could be seen as dovish for the Fed to retain 50bp of cuts on the table.
- The Fed held rates steady at 4.25% - 4.5% as widely expected
- Lowered their 2025 growth outlook to 1.7% (down from 2.1%) and 2026 GDP to 1.8% (down from %)
- Core PCE for 2025 increased to 2.7% (2.5% prior)
- PCE increased to 2.8% (2.5% prior)
- Fed Funds rate unchanged at 3.9% for 2025 and 3.4% for 2026
- Balance sheet runoff to be slowed from April
Wall Street traders took the dovish tilt as good news, with the S&P 500, Nasdaq and Dow Jones were all up on the day. Although volatility was contained. Gold continued to a new high, as it doesn’t seem to know how to do much else these days.
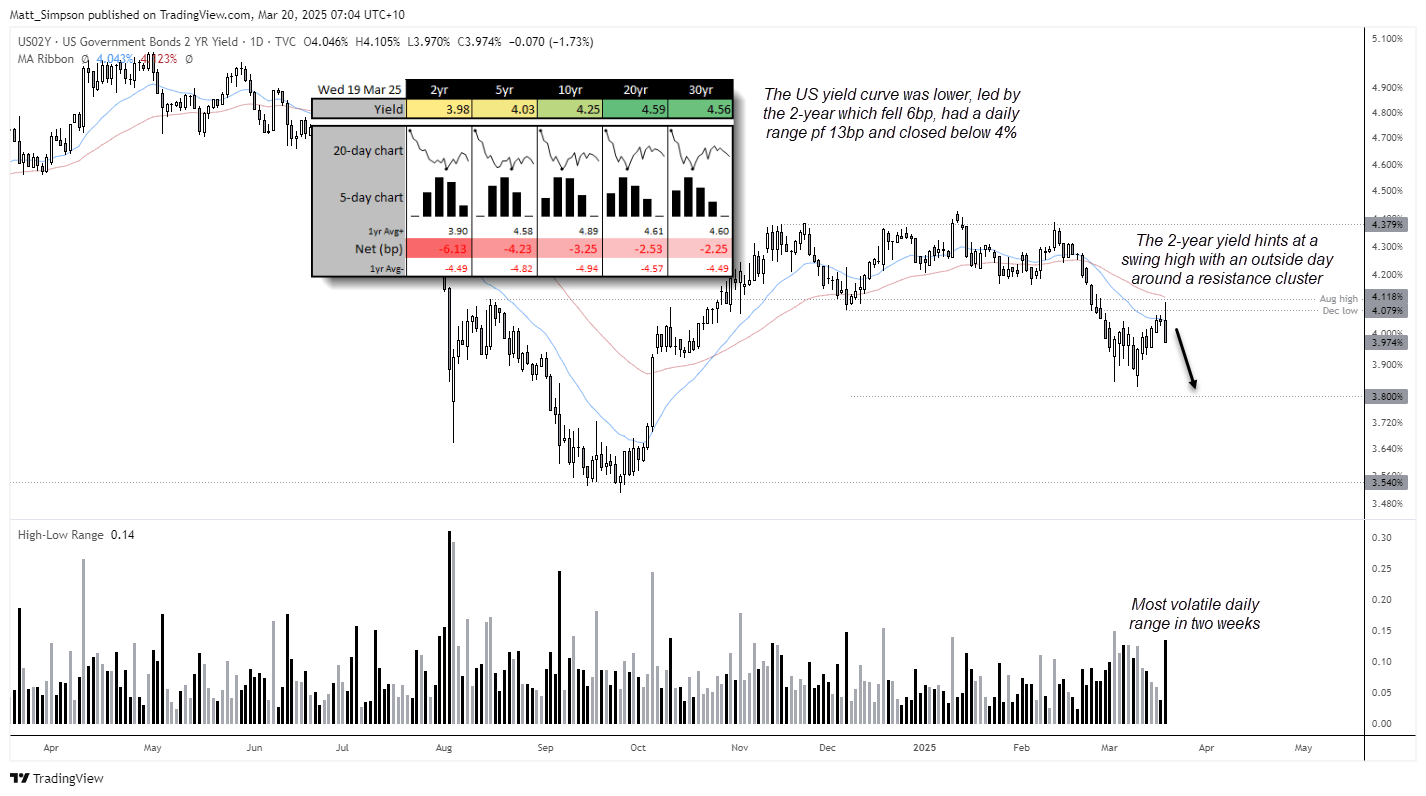
It was the most volatile day for the 2-year yield in two weeks, with its bearish outside day spanned 13bp to close -6bp lower and back beneath 4%. The recovery from 3.83% stalled around the December low, August high and 50-day EMA, further adding to the case that a swing high on yields may have been seen.
AUD/USD technical analysis
While AUD/USD closed flat following the Fed meeting, its lower wick on the day shows demand around the 10 and 20-day EMAs, around last week’s choppy range. And as messy as price action may have been, it is grinding higher since its rebound from 62c.
Yield differentials appear to be making a comeback, with the AU-US 2-year rising alongside AUD/USD this week. The relationship between the two was weak heading into last week, but they appear to now be back on talking terms again.
It should be noted that the differential is rising due to a drop in US yields as opposed to a rise in AU yields, but the bearishness of the US 2-year chart does look appealing enough to at least support AUD/USD over the near term.
The 4-hour chart shows a strong bullish bar accompanied with rising volume, which suggest a swing low around 0.6320. Bulls could seek dips within that candles range in anticipation of a move up to 64c. But for a break above it strong enough to clear the 38.2% Fibonacci level, we likely need a strong AU employment report alongside a continued selloff on the US 2-year yield.
Economic events in focus (AEDT)
The Bank of England (BOE) are likely to become the third major central bank to hold rates this week. Sticky inflation gives little room for cuts, even if there are two dissenters within the ranks – which likely leaves it 7-2 in favour of no action today. Still, some estimate that there could be as many as three cuts this year.
You can read my thoughts on Australia’s employment situation in the AUD/USD outlook article linked above, but in a nutshell it is likely to remain robust and not allow RBA doves to jeer for an imminent RAB rate cut. If it comes in strong enough, it could help AUD/USD head for 64c again.
- 00:00 – Japanese Public Holiday (Vernal Equinox)
- 08:45 – New Zealand Q4 GDP
- 11:30 – Australian Employment (Feb)
- 12:00 – PBOC Loan Prime Rate
- 18:00 – UK Earnings, Claimant Count, Employment Change
- 19:30 – SNB Interest Rate Decision (25bp cut expected)
- 23:00 – BOE Interest Rate Decision, MPC Votes (No Change Expected)
- 23:30 – BOE Governor Bailey Speaks
- 23:30 – US Jobless Claims, Philly Fed Manufacturing
ASX 200 at a glance
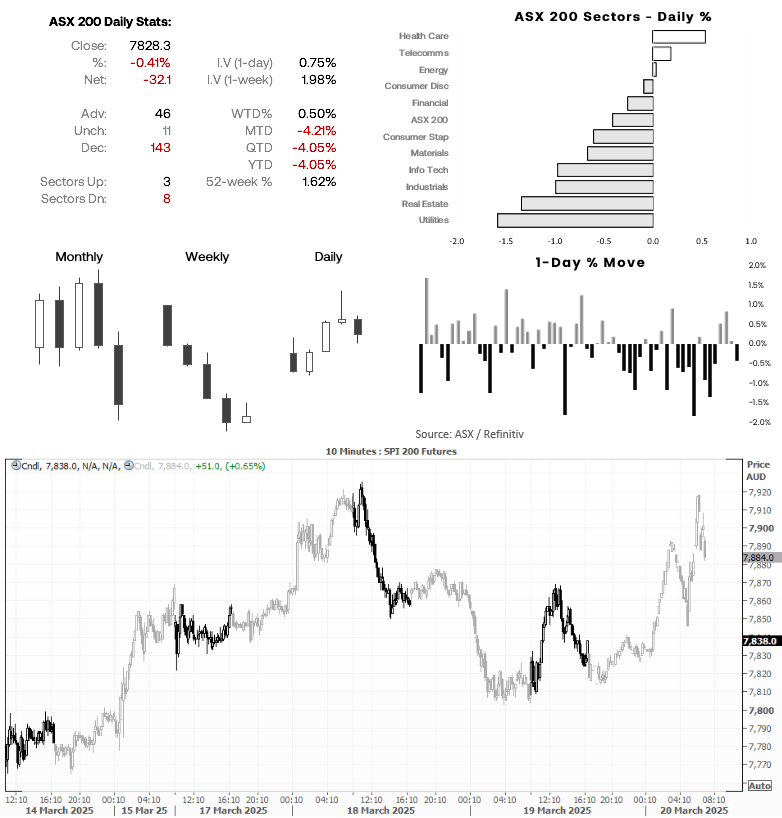
- The ASX 200 snapped a 3-day winning streak,
- Info tech is the weakest the 10 ASX sectors this past four weeks, down -19.3% while utilities is the only ASX sector to gain at 4%
- The bounce on Wal Street helped ASX 200 (SPI 200) futures rise 0.5% overnight, which points to a positive open for the ASX cash index today
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.