



Black Friday sale for crude ahead of busy next week
This holiday shortened trading week did not put off speculators from being heavily engaged in the markets, as volatility remained elevated.
Share this:

It was literally a “Black Friday sale” for crude oil, which fell more than 6% at one stage with Brent dipping below $58.50 amid concerns Saudi Arabia won't be able to cut crude supply due to pressure from Donald Trump to keep prices low. But we think that oil prices may have fallen too far, too fast. Thus, a short-covering rebound is increasingly likely soon, possibly in early next week, especially as Brent is now at a long term support area in the $57-$59 region – see the chart below.
Bitcoin and other cryptocurrencies also had a week to forget, as sentiment continues to deteriorate towards digital currencies. The stricter regulatory environment and momentum is giving the bears the sort of opportunities the bulls were enjoying last year.
However, the immediate focus will be on Brexit. Spanish objections over Gibraltar remain among a few sticking points as the UK is seeking to finalise its exit deal with the EU. An EU summit will take place this weekend to approve the Draft Withdrawal agreement. Ahead of this, the UK Prime Minister, Theresa May, once again refused to say whether she will quit if parliament votes against her Brexit deal next month.
Meanwhile, the economic calendar will be a lot busier next week.
New Zealand retail sales will come out first thing Monday. This will be a quarterly figure (as is the case for most of NZ’s key data releases), so it should have a meaningful impact on the kiwi should the actual figure deviate significantly from +1.0% expected. Then, once Europe gets underway, we will have the German Ifo Business Climate, which is a closely-watched survey of about 7,000 businesses, asking respondents to rate current business conditions and expectations for the next 6 months. So, let’s see if recent events (EM currency crises, trade wars etc.) have dented sentiment among manufacturers, builders, wholesalers, services and retailers.
In mid-week, we will have several important economic pointers from the US. The CB Consumer Confidence is released on Tuesday; preliminary US GDP will be published on Wednesday and a few other second-tier macro pointers will come out on Thursday – including core PCE price index, personal spending and pending home sales, as well as the Fed’s last meeting minutes.
A couple of Federal Reserve members have already expressed concerns about these risks last week and hinted at the prospects of slower rate hikes going forward. Meanwhile, inflationary pressures stemming from the crude oil market should also be weakening given the big falls for Brent and WTI amid concerns over excessive supply and slower demand growth for the black stuff. This is an additional reason why the Fed may decide against hiking aggressively next year. If we indeed do see further dovish commentary from Fed members then the dollar could start to head lower.
Friday will see the release of Chinese manufacturing PMI as well as some not-so-important Japanese pointers. The Chinese PMI will be watched closely as investors try to gauge the economic impact of the nation’s trade dispute with the US. Also on Friday, we will have German retail sales and Eurozone CPI, and Canadian GDP.
So, there’s plenty to look forward to next, which should mean more volatility and hopefully even better trading opportunities.
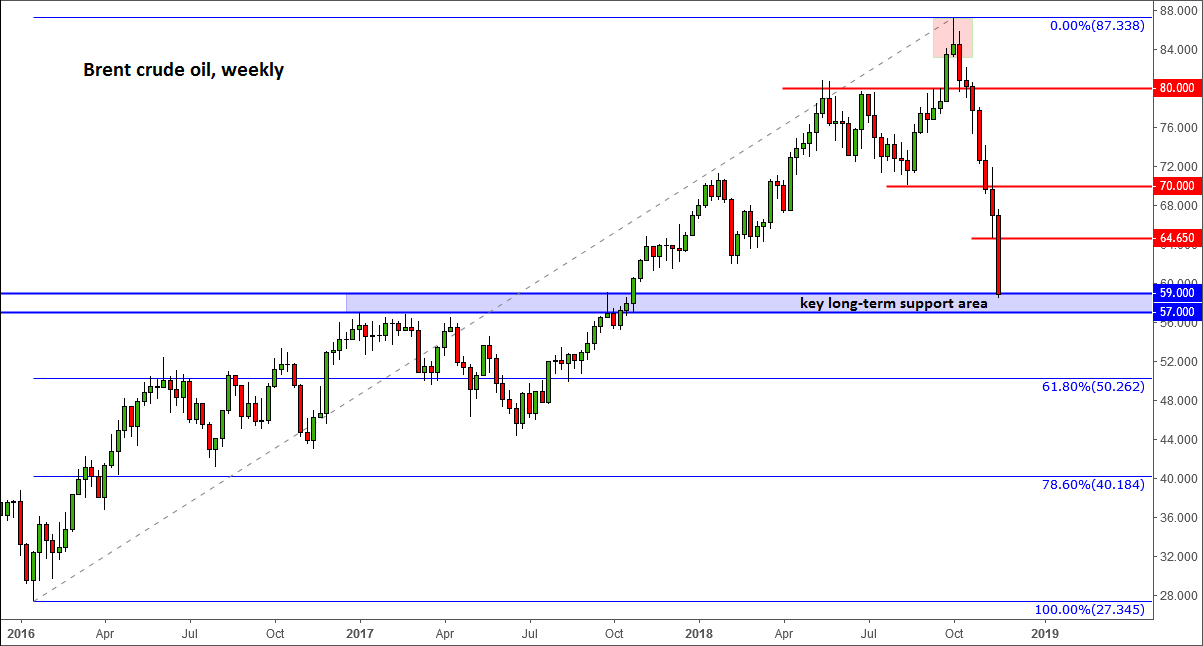
Source: Trading View and FOREX.com

Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.