



Brexit trade and FOMC to dominate agenda next week
The biggest story this week was perhaps the easing of trade wars as China apparently blinked first in its dispute with the US.
Share this:

Another week has flown by and what a week it has been! The biggest story this week was perhaps the easing of trade wars as China apparently blinked first in its dispute with the US. Global stock markets, led by China, and base metal prices all staged a relief rally. The firmer metal prices and positive risk sentiment helped to boost the likes of the Australian dollar and yen crosses. Although China retaliated to the latest imposition of tariffs by the US, Beijing nevertheless sharply slashed its tariff rates on imports of US goods compared to what it had proposed previously. So, China in particular appears willing to talk and this has boosted speculation among market participants that an agreement will be formed at a not-so-distant future despite the growing trade dispute. Thanks to renewed optimism over trade, the Dow posted its 12th record close of the year on Thursday although there was little further follow-through on Friday when this report was being written.
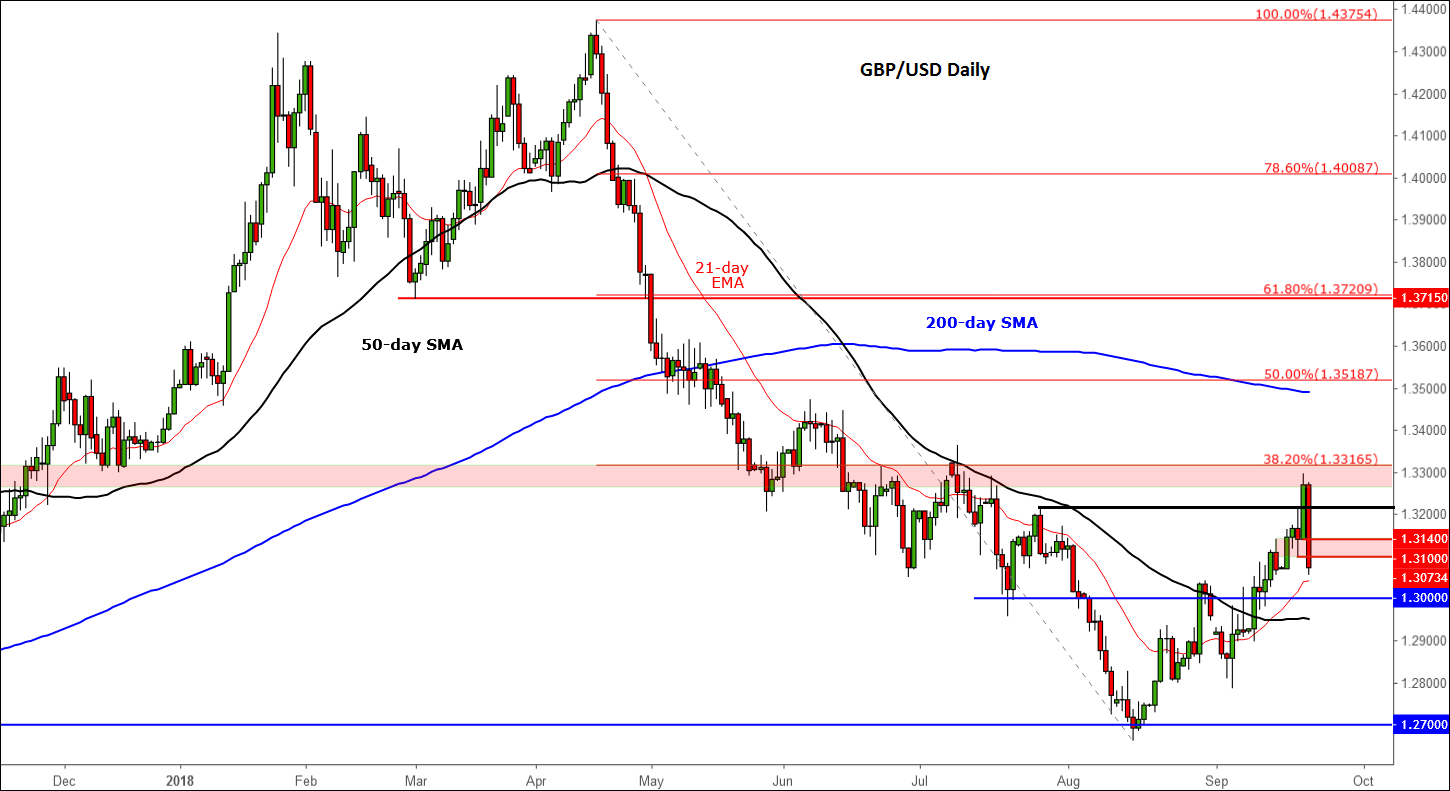
In Europe, Brexit remained in focus and the incoming mixed headlines tossed the pound around throughout the week. But after the early optimism, all hopes for a quick resolution were dashed after EU negotiators told UK Prime Minister Theresa May that her Chequers Brexit plan “would not work.” The pound fell back sharply on Friday morning, giving back its entire gains made the day before. Then it sunk even more after UK Prime Minister Theresa May admitted that the UK and EU "are at an impasse" in Brexit talks and wanted to be shown respect – demanding the EU to shift its negotiating position to avoid a no deal exit.
Looking ahead to next week, we have two major central bank meetings on the agenda, namely the US Federal Reserve and Reserve Bank of New Zealand both on Wednesday, while in terms of data the economic calendar will be light. It will be also be interesting to see how the EU would respond to Theresa May’s speech. At the moment the UK-EU relationship looks divided, but the same can be said about May’s position within her Conservative party. So, things could potentially get a lot worse for her and the UK before it gets better. This concern could weigh further on the pound in early next week.
Meanwhile as far as the Federal Reserve is concerned, a rate increase is almost certain on Wednesday. It would be a massive shock if the Fed refused to hike. In any case, the dollar may not respond much as a rate hike is now fully priced in. The Fed’s next “live” meeting is on December 19-20, which is when the Fed is most likely to hike again, should economic conditions still warrant it. But this potential rate hike is less certain. Thus, if there are more indications from the rate statement, dot plots or Jerome Powell at the press conference suggesting the FOMC is leaning towards a rate hike in December than had been indicated in the past, then this could be dollar-positive.
Source: TradingView.com and FOREX.com.

Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.