



Brexit what Brexit UK data continues to confound expectations
<p>After the surprisingly strong UK inflation figures on Tuesday, the jobs and wages data released today confounded expectations once again, albeit to a lesser degree. […]</p>
Share this:

After the surprisingly strong UK inflation figures on Tuesday, the jobs and wages data released today confounded expectations once again, albeit to a lesser degree.
The average earnings index, which includes bonuses, rose 2.4% in the three months to June compared to the same period a year ago. The good news is that it was up from 2.3% in May, but it was slightly lower than 2.5% expected. The unemployment rate was unchanged during this period at 4.9%, but the employment rate hit its highest since records began in 1971.
Meanwhile, the more up-to-date data for July showed that claims for unemployment benefits fell by a good 8,600 applications. This was a big surprise in that not only did it easily beat expectations for a rise of 5,200 expected but more importantly it was a rise in the month after Brexit, when things were supposed to turn bleak.
Don’t jump into conclusions
So far, the evidence therefore suggests that Brexit isn’t having much of an impact on the jobs market. In a way this is not surprising because everyone knows that it will be at least two years before the UK actually leaves the EU. But it is early days to gauge even the near-term impact of Brexit, while it is also possible that the data is simply an outlier. So we shouldn’t jump into any conclusions, the Bank of England certainly wouldn’t.
Market reaction
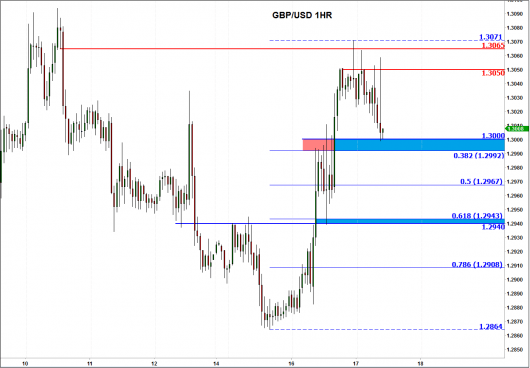
Indeed, that is how the markets took the news, judging by the behaviour of price action immediately after the data was released. The GBP/USD briefly neared its overnight highs, before starting to drift back from 1.3060 to trade at 1.3000 at the time of this writing. Against the euro, the pound also relinquished most of its early advance. But the pound may be able to regain its poise later on today for two reasons.
First, the FOMC’s last meeting minutes may reveal a dovish message, although if we go by what William Dudley, president of the New York Fed, said yesterday – that a rate rise next month was still possible – the minutes may not be dovish after all, causing the GBP/USD to slump.
Secondly, the short-term technical outlook on the Cable has turned bullish following yesterday’s rally, so we may see dip buyers emerge at these slightly lower prices, especially given the fact that the jobs figures were stronger-than-expected. Indeed, the Cable has been putting in a couple of higher lows and higher highs on its intra-day charts over the past 24 hours or so. Thus, we may see a technical rebound at around 1.3000 support or further lower at 1.2940/5 (both areas shaded in light blue on the chart). These levels were previously support and converge with Fibonacci retracement levels. The short-term bullish bias would be confirmed on a potential break above yesterday’s high of 1.3070. However, if yesterday’s low breaks down conclusively then that would invalid this bullish outlook. Today’s price action will therefore be very important.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.