



Bumper AU jobs data and China rate cut ignite AUDNZD
Following an impressive gain of +366k jobs in November, the Australian economy added another +64.8k job in December. The seasonally adjusted unemployment rate fell to 4.2% from 4.6%, its lowest level since pre the Global Financial Crisis, August 2008
Share this:
As noted in our preview yesterday, the survey reference period was November 28th to December 11th, pre the surge in Omicron cases in late December. As such, the impact of Omicron will not be seen until the January and February jobs data and result in a renewed, albeit temporary, hit to employment.
The recovery in the labour market sees the level of employment now 0.5% above pre-Delta levels. At this pace the unemployment rate is set to fall below 4% in the coming months and almost certainly spells the end to the RBA’s QE program in February.
During the second half of 2021, the Reserve Bank of Australia noted on many occasions that a tighter labour market was required to lift wages growth as a prerequisite to raising interest rates.
Based on today's data, wages growth should accelerate towards 3% y/y by the second half of 2022, putting the start of an RBA tightening cycle firmly on the calendar for early in the second half of 2022.
The preferred way to play today's robust jobs data is via long AUDNZD, which takes out of the equation some of the event risk of next week's Federal Reserve meeting.
Additionally, it incorporates the benefits of Chinese policymakers taking further steps to meet their growth targets by cutting the one-year loan prime rate by 10 basis points to 3.7% and the five-year rate by 5 basis points to 4.6%. It is worth noting that when Chinese authorities set and reaffirm growth targets, they rarely miss them.
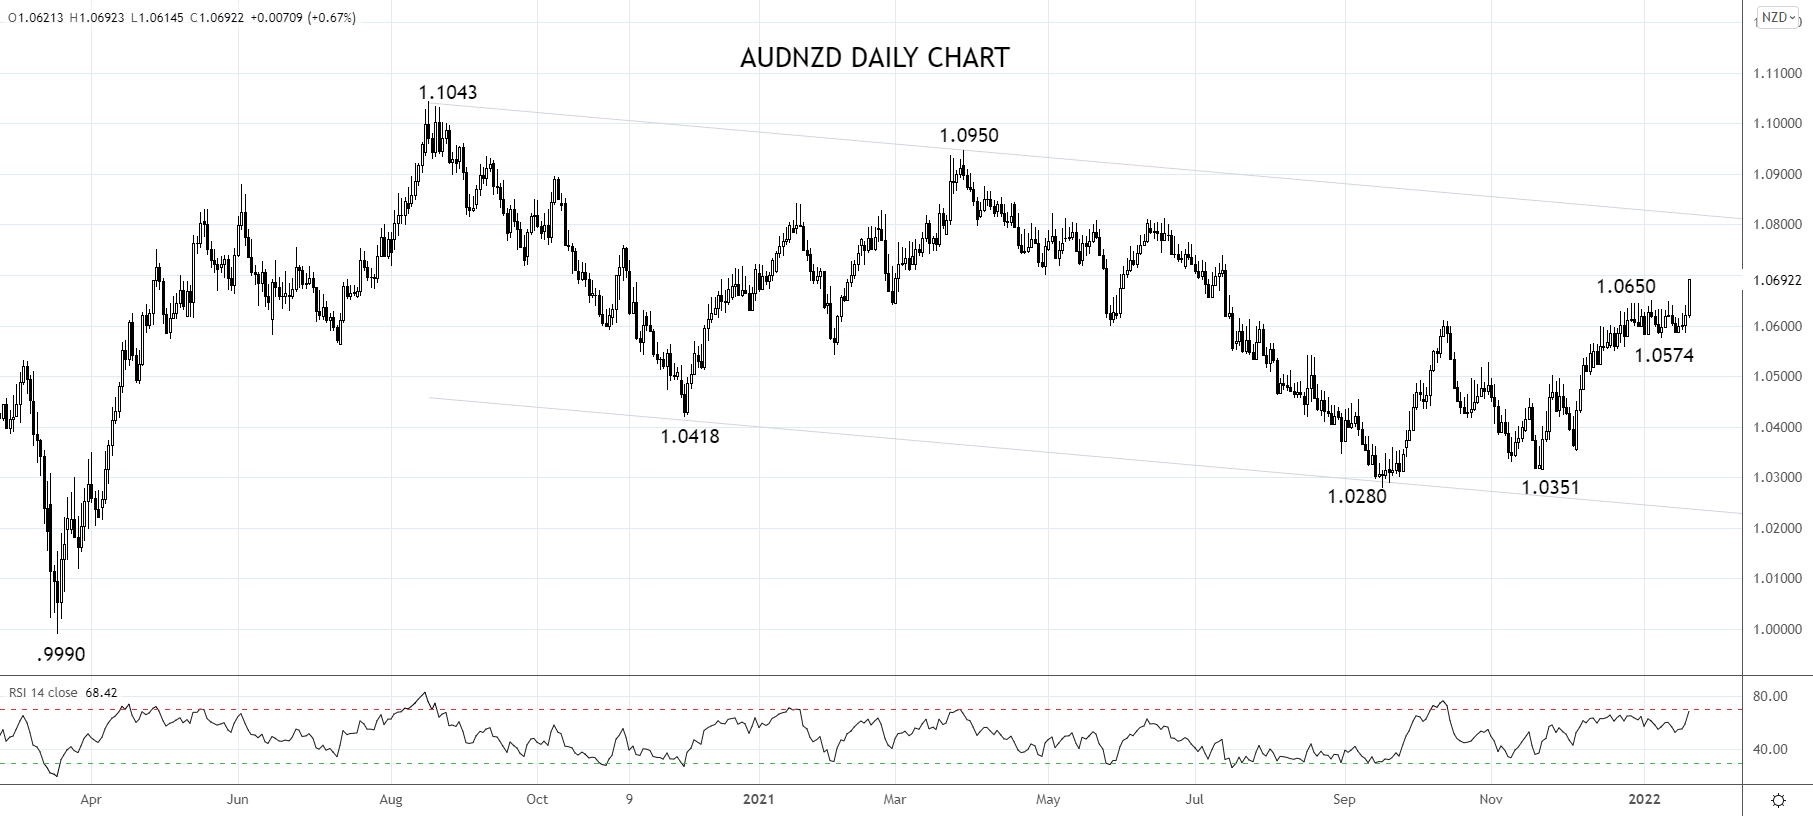
Technically, the break above resistance/congestion at 1.0650 allows the rally to extend towards the top of the six-month trend channel from the 1.1043 August high at 1.0820.
To take advantage of this view, use dips back towards 1.0665/45 to open longs in AUDNZD, looking to take profit 1.0800/20. Stops should be placed below the 2022 range lows at 1.0565.
Source Tradingview. The figures stated areas of January 20th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
As noted in our preview yesterday, the survey reference period was November 28th to December 11th, pre the surge in Omicron cases in late December. As such, the impact of Omicron will not be seen until the January and February jobs data and result in a renewed, albeit temporary, hit to employment.
The recovery in the labour market sees the level of employment now 0.5% above pre-Delta levels. At this pace the unemployment rate is set to fall below 4% in the coming months and almost certainly spells the end to the RBA’s QE program in February.
During the second half of 2021, the Reserve Bank of Australia noted on many occasions that a tighter labour market was required to lift wages growth as a prerequisite to raising interest rates.
Based on today's data, wages growth should accelerate towards 3% y/y by the second half of 2022, putting the start of an RBA tightening cycle firmly on the calendar for early in the second half of 2022.
The preferred way to play today's robust jobs data is via long AUDNZD, which takes out of the equation some of the event risk of next week's Federal Reserve meeting.
Additionally, it incorporates the benefits of Chinese policymakers taking further steps to meet their growth targets by cutting the one-year loan prime rate by 10 basis points to 3.7% and the five-year rate by 5 basis points to 4.6%. It is worth noting that when Chinese authorities set and reaffirm growth targets, they rarely miss them.
Technically, the break above resistance/congestion at 1.0650 allows the rally to extend towards the top of the six-month trend channel from the 1.1043 August high at 1.0820.
To take advantage of this view, use dips back towards 1.0665/45 to open longs in AUDNZD, looking to take profit 1.0800/20. Stops should be placed below the 2022 range lows at 1.0565.
Source Tradingview. The figures stated areas of January 20th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
NFP Preview: New Government, Same Jobs Market?
Traders are still sifting through the fallout of the US midterm elections, just in time to get hit with another volatility: The monthly Non-Farm Payrolls (NFP) report - what will the jobs report show, and what could it mean for the US dollar?

Australian Jobs Report Hammers Another Nail into the Coffin for RBA Hikes
Australian jobs fell by 39.3k as unemployment held at 4.7%, sending the Aussie lower and prompting traders to scale back expectations for further RBA hikes.


NFP Preview: Can the Jobs Report Overcome the Bond Market Meltdown Too?
Traders and economists expect the NFP report to show that the US created 90K net new jobs, with average hourly earnings rising 0.3% m/m (3.1% y/y) and the U3 unemployment rate at 4.1% - see what the leading indicators are suggesting!
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.