





City Index
A summary of news and snapshot of moves from today’s Asia session.
Share this:

- RBA’s Deputy Governor Guy Debelle says floor for rates here likely around 0% - 0.5%, adding they hope they won’t have to go as low as some countries (ie negative).
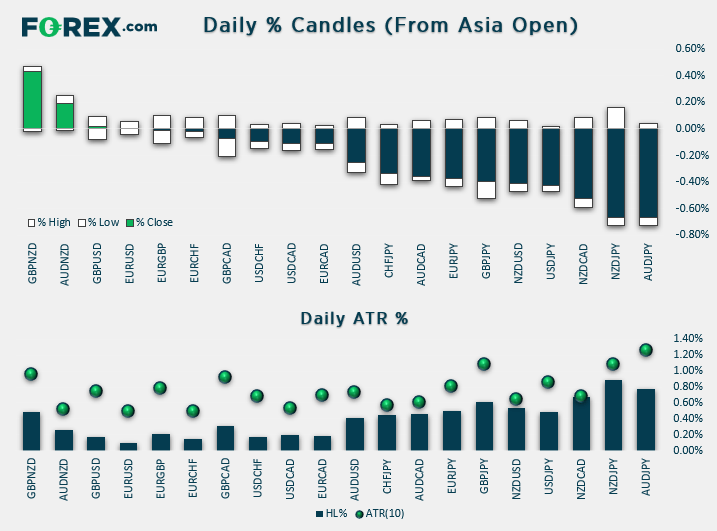
- JPY and CAD are the strongest majors, NZD and AUD are the weakest. The baulk of today’s volatility has been seen on yen pairs, with USD/JY, GBP/JPY, NZD/JPY and AUD/JPY exceeding their typical daily ranges. AUD/JPY is the largest mover, having shed nearly -0.6% at the session low.
- Japan’s Finance Minister, Taro Aso said he’s closely watching FX moves “with a sense of urgency” following the yen recent spike.
- The CNY fix was set to a fresh 11.5 year low, yet not as weak as expected. USD/CNY not trades at 7.16 and USD/CNH at 7.17.
- Philippines central bank keep the global race to the bottom alive and well, saying another 25bps cut will come by the year end.
- Asian stock markets have recouped yesterday’s losses after U.S. President Trump’s “smoothing de-escalation” comments towards China regarding the on-going trade tension. Trump said at the press conference after the G7 summit that a trade deal was around the corner after positive gestures by Beijing.
- However, it not a broad-based stellar recovery seen in Asian stocks as at today’s Asian mid-session, the Hong Kong’s Hang Seng Index and Singapore’s STI are almost unchanged. Concerns over the on-going domestic protests in Hong Kong have continued to dent sentiment despite a better than expected China’s industrial profits; it rose 2.6% y/y in Jul from a contraction of -3.1% y/y in Jun.
- Apple supplier, AAC Tech (Hang Seng component stock) has continued to underperform after it announced a weak H1 earnings result yesterday, ACC Tech has shed – 2.15% today.
- Over at Singapore’s STI, market breadth for the component stocks is lacklustre where 14 are showing gains; 14 losses and 4 at the unchanged mark. The biggest drag is Yangzijiang Shipping, down by -5.45% over uncertainty on the state of its Executive Chairman and major shareholder, Ren Yuanlin that was reported on leave since 14 Aug to assist the Chinese authorities in a confidential investigation.
- S&P 500 E-min futures is almost unchanged in today’s Asian session where it printed a current intraday high of 2886 versus a closing level of 2878 seen in the cash S&P 500 yesterday.
Up Next:
- German GDP is the final read, so tends not to deviate too much from its prior read. Although leading indicators such as German IFO business sentiment strongly point towards a recession. So a minor downgrade here could mean more than usual.
- From the US, the Richmond Manufacturing Index is of interest after it fell off a cliff last month. At -12, it as its weakest print since 2013 and, with an expectation for to ‘only’ contract at -, still leaves potential for disappointment later today if this hefty gap is not filled.
- Whilst business sentiment remains in the doldrums, consumer sentiment is soaring again and just a few points away from its post-GFC high. The argument is that consumer’s are usually the last reads to show distress I the underlying economy, so signs of weakness here could be taken as confirmation by some that the expansion is nearing an end but, for now, consumer sentiment appears quite resilient.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.
EUR/USD forecast: Dollar strength puts 1.1000 support in the spotlight | Currency Pair of the Week
The dollar extended its recent advance at the start of the week, with weakness across risk-sensitive assets reinforcing demand for the US currency. US equity futures slipped ahead of Nvidia’s earnings on Tuesday and an expected stock market debut by Anthropic later this week. Both events represent important tests for an AI trade that has become increasingly vulnerable to shifts in sentiment. In FX, EUR/USD nearly tested the psychologically important 1.1000 level, before bouncing modestly off its lows.


Forex & Gold Outlook: Dollar Dominates, Crosses Diverge
The US dollar rally gathers momentum as forex crosses develop contrasting technical setups. Matt Simpson examines eight FX markets and gold for potential trading opportunities.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.