



Dollar Rally Likely to Extend After Election
After the weekend’s surprise FBI announcement that it has found no evidence of criminal wrongdoing by Presidential Candidate Hillary Clinton in connection with her private email server, financial markets on Monday have clearly begun to price-in a Clinton victory. US stock markets (the S&P 500 and NASDAQ) rallied more than 2%, the US dollar rose sharply against most other major currencies, and gold prices plunged. If Clinton indeed wins the presidential race on Tuesday as the markets are currently predicting, most of these market reactions may likely plateau or experience much slower drift, as a more business-as-usual market environment returns. For the US dollar, however, a longer-term rally is likely to extend as focus shifts back to the Federal Reserve.
Share this:

After the weekend’s surprise FBI announcement that it has found no evidence of criminal wrongdoing by Presidential Candidate Hillary Clinton in connection with her private email server, financial markets on Monday have clearly begun to price-in a Clinton victory. US stock markets (the S&P 500 and NASDAQ) rallied more than 2%, the US dollar rose sharply against most other major currencies, and gold prices plunged. If Clinton indeed wins the presidential race on Tuesday as the markets are currently predicting, most of these market reactions may likely plateau or experience much slower drift, as a more business-as-usual market environment returns. For the US dollar, however, a longer-term rally is likely to extend as focus shifts back to the Federal Reserve.
It remains clear that a Clinton victory tomorrow will remove one of the major risk factors for the Fed in terms of raising interest rates. Regardless of political leanings, a Trump victory would most likely contribute to substantially heightened market volatility, potentially playing a key role in discouraging a December rate hike by the Fed. A Clinton win, in contrast, should dampen market volatility, and would therefore help encourage the Fed to pursue tighter monetary policy.
At the same time, despite missing headline market expectations last week, October’s US jobs data held some very significant clues that inflation was on an upswing and the US employment landscape is both solid and improving. First, the non-farm payrolls reading for the prior month of September was revised sharply up to 191,000 from its original disappointment of 156,000. But even more importantly, October’s average hourly earnings, a key measure of US wage growth and inflation, was surprisingly better than expected at +0.4% against prior expectations of +0.3% and up from September’s +0.2%. Overall, wages posted a 2.8% annualized increase, the largest rise in over seven years.
As inflation and employment are the primary drivers of Fed policy decisions, this positive data in combination with the lower likelihood of initial market volatility under a Clinton Administration, should place even more pressure on the Fed to raise interest rates in the near-term. If this indeed becomes the case, the dollar could quickly recover from its recent election-driven slump and embark on a substantial rally.
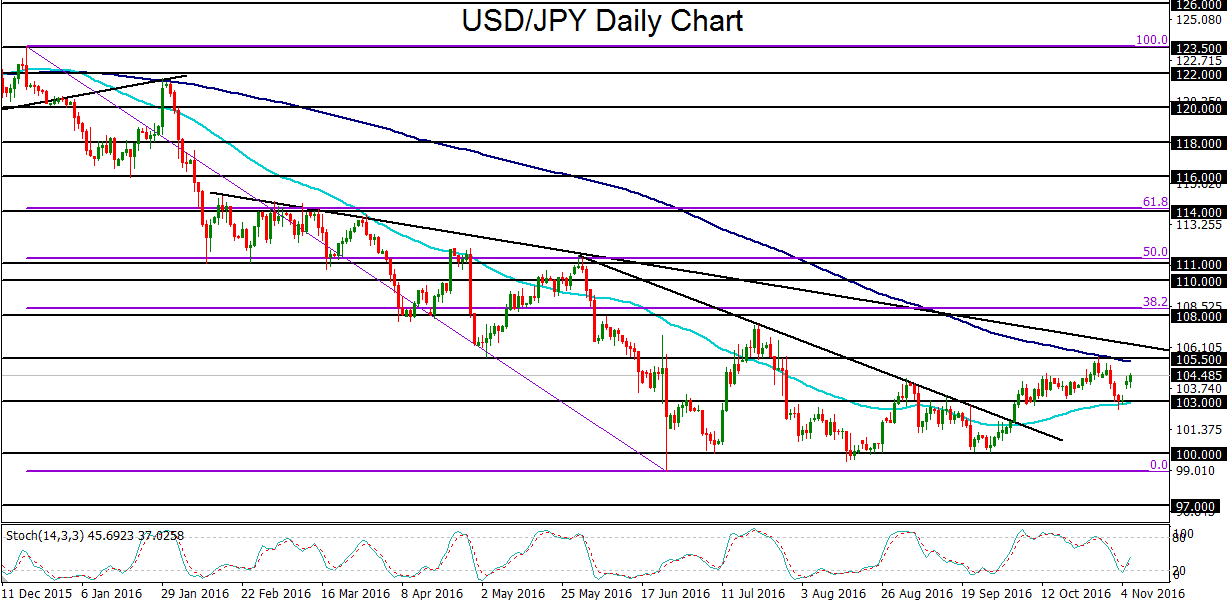
USD/JPY has recently shown some indication that it has formed a base around the major 100.00 psychological support area, as it has risen well off those lows over the past several weeks. With extended dollar strength and further weakening of the safe-haven Japanese yen after Tuesday’s election and ahead of the next Fed meeting, USD/JPY could break out above strong resistance around the 105.50 level, in which case the next major upside target is around the key 108.00 resistance level.
It remains clear that a Clinton victory tomorrow will remove one of the major risk factors for the Fed in terms of raising interest rates. Regardless of political leanings, a Trump victory would most likely contribute to substantially heightened market volatility, potentially playing a key role in discouraging a December rate hike by the Fed. A Clinton win, in contrast, should dampen market volatility, and would therefore help encourage the Fed to pursue tighter monetary policy.
At the same time, despite missing headline market expectations last week, October’s US jobs data held some very significant clues that inflation was on an upswing and the US employment landscape is both solid and improving. First, the non-farm payrolls reading for the prior month of September was revised sharply up to 191,000 from its original disappointment of 156,000. But even more importantly, October’s average hourly earnings, a key measure of US wage growth and inflation, was surprisingly better than expected at +0.4% against prior expectations of +0.3% and up from September’s +0.2%. Overall, wages posted a 2.8% annualized increase, the largest rise in over seven years.
As inflation and employment are the primary drivers of Fed policy decisions, this positive data in combination with the lower likelihood of initial market volatility under a Clinton Administration, should place even more pressure on the Fed to raise interest rates in the near-term. If this indeed becomes the case, the dollar could quickly recover from its recent election-driven slump and embark on a substantial rally.
USD/JPY has recently shown some indication that it has formed a base around the major 100.00 psychological support area, as it has risen well off those lows over the past several weeks. With extended dollar strength and further weakening of the safe-haven Japanese yen after Tuesday’s election and ahead of the next Fed meeting, USD/JPY could break out above strong resistance around the 105.50 level, in which case the next major upside target is around the key 108.00 resistance level.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.


Nasdaq 100 Forecast: NDX falls ahead of Nvidia’s earnings & Anthropic’s debut this week
U.S. stocks are heading for a weaker open amid a challenging macro backdrop and with AI-linked stocks once again under pressure ahead of Nvidia's results later this week. Attention is also turning to Anthropic's highly anticipated IPO.

Gold, USD/JPY Forecast: Two trades to watch 161126
Gold falls to a yearly low ahead of FOMC minutes this week. USD/JPY hovers around 160 amid a stronger USD and weaker Japanese GDP.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.