




USD/CNH: Economic woes mount for China
The economy needs fresh measures to stimulate domestic spending. However, the government’s strict Covid curbs are still there...
Share this:
At the start of the new week, the FX markets continue to trend strongly in the favour of US dollar after Friday's stronger US jobs report reinforced expectations of more aggressive Fed rate hikes. Meanwhile, the likes of the euro and yuan (and thus AUD) going in the opposite direction on the back of weakness in data.
The USD/CNH has started to climb back towards its recent highs after a period of relative stability since the end of September. More on this later.
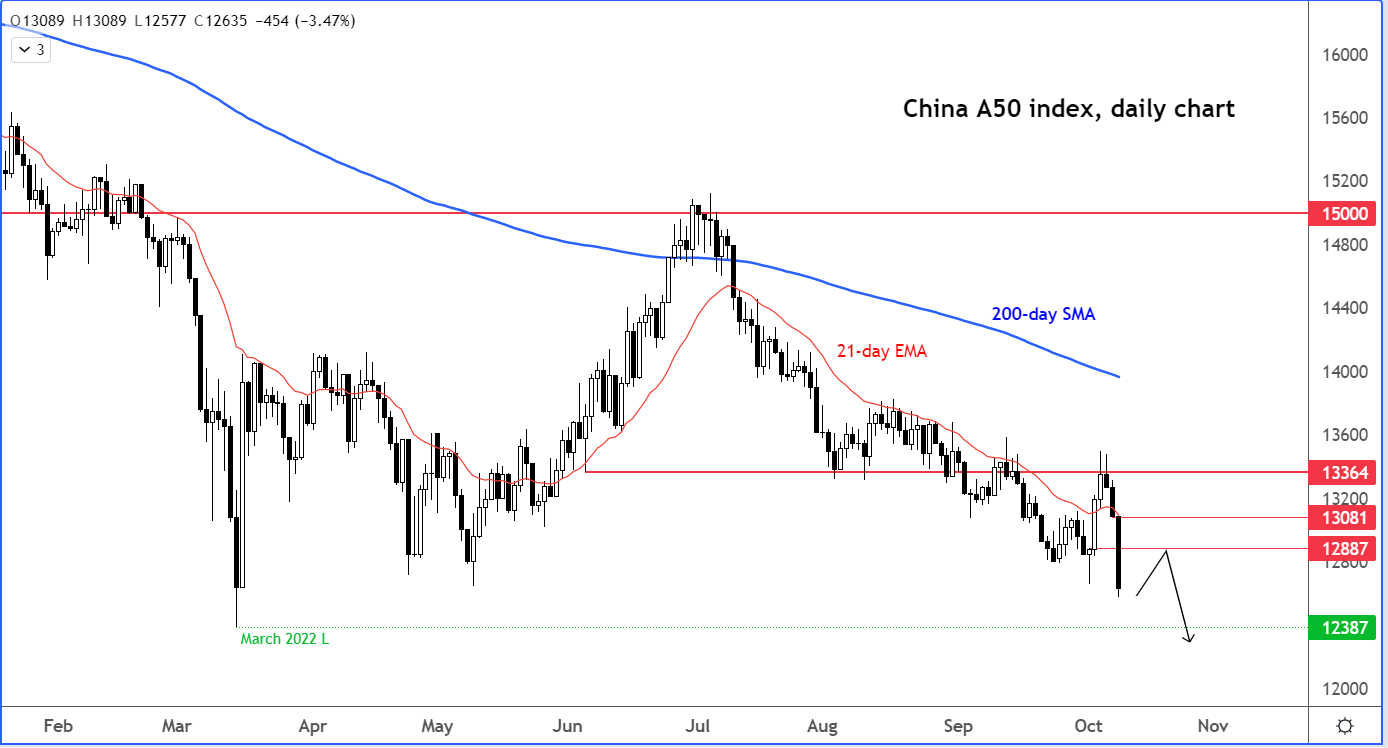
Meanwhile, Chinese equities have slumped at the start of the new week, with the benchmark CSI 300 Index falling by 2.2% to close at its lowest since April 2020. Losses were led by tech and consumer staples. The China A50 index (CHN50) plunged even more profoundly overnight:
Concerns about the health of the Chinese economy, the world’s second largest, is growing.
You might have missed a really weak Caixin Services PMI number that was released over the weekend. It came in at 49.3, more than 5 points lower than expected (54.5) and last month’s print of 55.0. This was reflected in a sharp cut back by Chinese holidaymakers on travel and spending during the National Day breaks last week.
It is clear that China is struggling. The economy needs fresh measures to stimulate domestic spending. However, the government’s strict Covid curbs are still there despite the rest of the world moving on and learning to live with the virus.
Until something changes fundamentally, the Chinese yuan is likely to remain undermined.
Dollar strength continues ahead of key US data
Meanwhile the case for an even stronger dollar continues, after Friday’s publication of a stronger US jobs report gave investors more reason to believe the Fed will continue its aggressive rate increases in order to create a soft landing in the economy to help bring inflation to more acceptable levels.
Speaking of inflation, the latest US Consumer Price Index (CPI) data will be published on Thursday. With the jobs market remaining strong, it is unlikely that the Fed will ease off the gas any time soon with inflation coming down only a little bit over the past couple of months. A lot will depend very much on incoming inflation data in the months ahead now. Annual CPI has fallen from 9.1% in June to 8.5% in July and 8.3% in August, thus remaining quite high. Expectations are that it probably drifted further lower to 8.1% last month. Risk assets will probably like a print well below that, otherwise expect dollar to remain supported on anything else.
We will also have other macro pointers from the US to look forward to this week, not least retail sales on Friday. Soaring inflation is expected to keep consumer spending in check. Thus, retail sales should have remained subdued in September after stagnating in the previous two months. If it turns out to be very poor, then this may give rise to the “Fed pivot” trade again and weigh on USD. Otherwise, it will be status quo.
Ahead of this week’s US data releases, the USD/CHN has found renewed buying interest, thanks in part to the weakness in Chinese data. This pair is thus likely to remain supported on the dips. Everything else being equal, I think the USD/CNH pair is heading for a breakout above this year’s high so far of 7.267.
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.