



European Open: Equities continued to tumble, German IFO up next
Anyone hopes of a Tuesday turnaround in Asia following Wall Street’s late rebound were quickly dashed, with equity markets across the region all in the red again.
Share this:

Asian Indices:
- Australia's ASX 200 index fell by -177.9 points (-2.49%) and currently trades at 6,961.60
- Japan's Nikkei 225 index has fallen by -475.24 points (-1.72%) and currently trades at 27,113.13
- Hong Kong's Hang Seng index has fallen by -358.77 points (-1.46%) and currently trades at 24,297.69
- China's A50 Index has fallen by -127.31 points (-0.83%) and currently trades at 15,280.93
UK and Europe:
- UK's FTSE 100 futures are currently up 25 points (0.35%), the cash market is currently estimated to open at 7,322.15
- Euro STOXX 50 futures are currently up 20 points (0.49%), the cash market is currently estimated to open at 4,074.36
- Germany's DAX futures are currently up 81 points (0.54%), the cash market is currently estimated to open at 15,092.13
US Futures:
- DJI futures are currently down -338 points (-0.99%)
- S&P 500 futures are currently down -271.5 points (-1.87%)
- Nasdaq 100 futures are currently down -61 points (-1.39%)
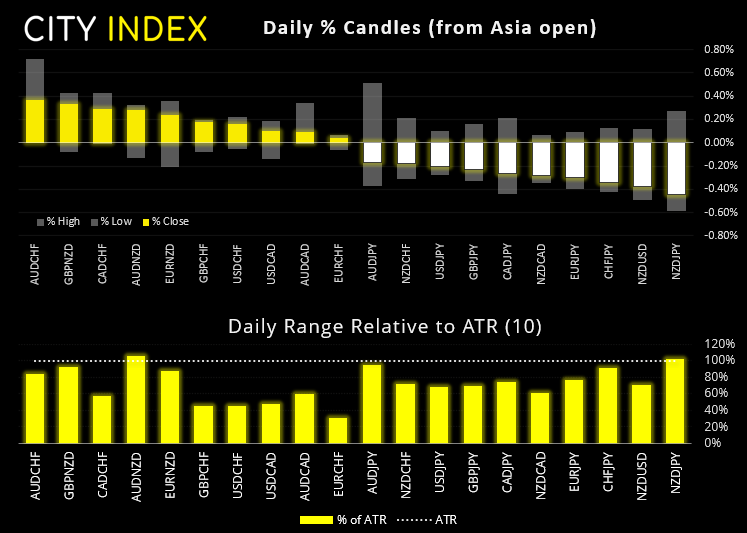
Australia’s ASX 200 was led the declines thanks to (or not thanks to) decent inflation numbers. Yet it would have arguably been lower regardless as the theme of the overnight session was to offload riskier assets. The TOPIX and Nikkei both fell over -2% and China’s benchmark indices were off by around -1.2%. The question now is whether this is a prelude of things to come in Europe, or whether it’s simply an over-reaction to moves seen on Wall Street yesterday. Futures markets point towards the former as the FTSE, DAX and CAC are expected to open higher today, but then we also saw that very same pattern ahead of the Asian open so we shall find out shortly.
Australian inflation beat expectations
A decent set of inflation numbers in Q4 for Australia helped send the Australian dollar higher and raise expectations of a rate hike. Trimmed mean CPI rose to 1% y/y, its highest level since 2008 and CPI (including energy and food) rose to 2.6%m its highest level since Q2 2014. The 6-month OIS (overnight index swap) rose to a post-pandemic level although, at 0.177 still falls short of a full rate hike being priced in. And that is likely because the RBA remain defiantly dovish in regards to hikes, although it does add further pressure to wrap up QE at their next meeting.
German IFO data up next
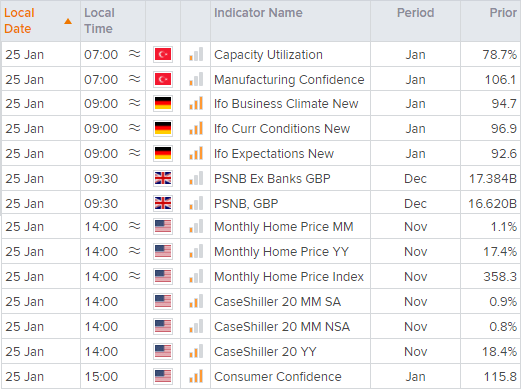
The monthly IFO business sentiment report is released at 09:00 GMT and should shed further light on the severity of the economic downturn. Business climate fell for a sixth month in December to 94.7 and is expected to remain flat later today. Current conditions are expected to fall to 96.1 from 96.9 and expectations is expected to rise slightly to 93 from 92.60.
Bundesbank warned in a report this week that GDP likely fell in Q4, although their outlook for the new year is slightly optimistic. Therefore, the outlook component of today’s IFO report could be one to watch as weak data from the region is not exactly new news.
Dollar index set to resume its rally?
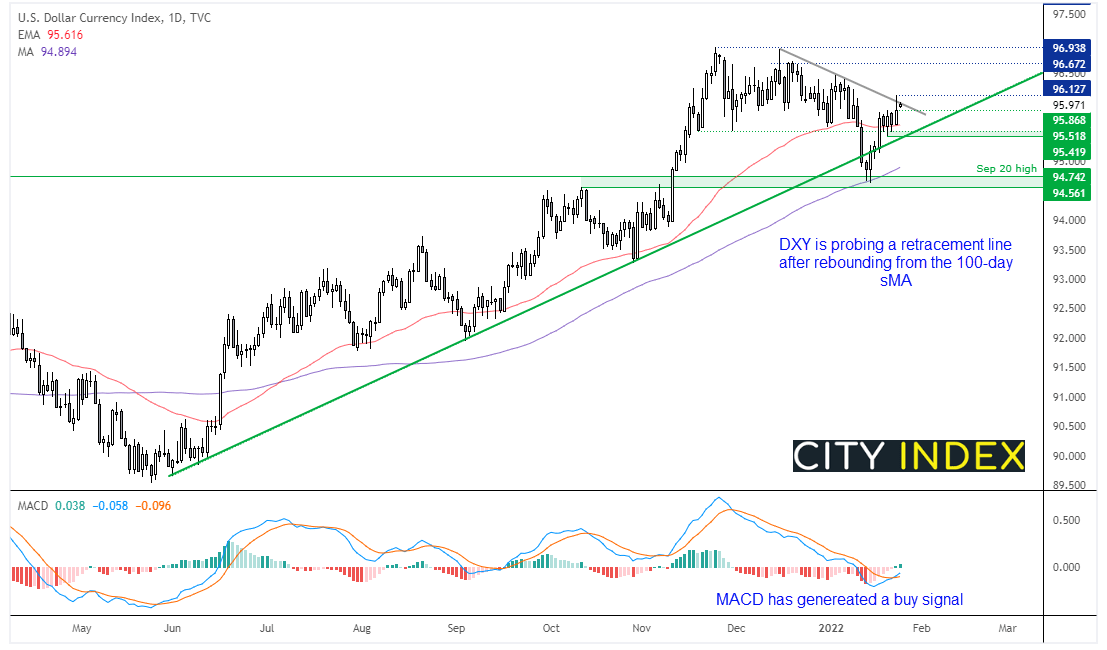
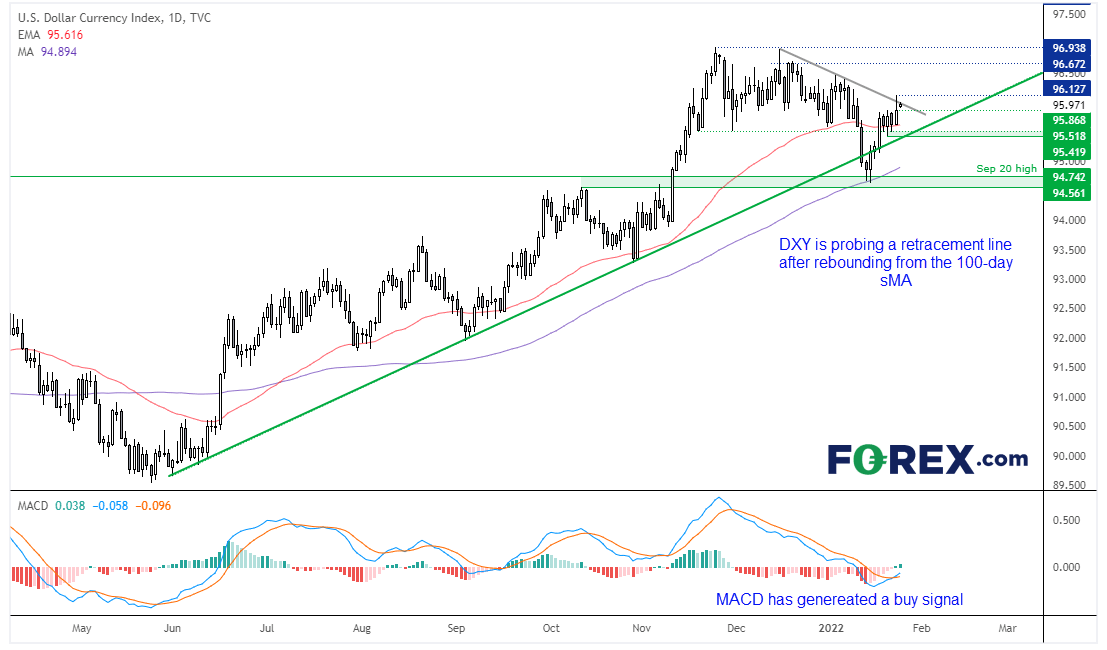
The US dollar index (DXY) is considering a break of a key trendline after spending several days in a small, sideways consolidation. Its correction from the November high seems to have completed with its temporary drop below 95, where support was found at the 100-day sMA and September highs. From here out bias remains bullish above 95.50 (just below the recent consolidation) although tighter risk management could be considered if we see a decent break above yesterday’s high.
Read our guide on the US Dollar Index (DXY)
FTSE 350: Market Internals
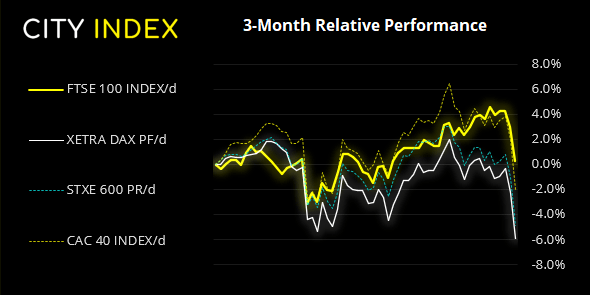
FTSE 350: 4123.56 (-2.63%) 24 January 2022
- 14 (3.99%) stocks advanced and 337 (96.01%) declined
- 4 stocks rose to a new 52-week high, 50 fell to new lows
- 30.48% of stocks closed above their 200-day average
- 22.51% of stocks closed above their 50-day average
- 7.12% of stocks closed above their 20-day average
Outperformers:
- + 7.31% - Unilever PLC (ULVR.L)
- + 4.53% - Vodafone Group PLC (VOD.L)
- + 4.40% - Playtech PLC (PTEC.L)
Underperformers:
- -14.62% - Darktrace PLC (DARK.L)
- -11.58% - Molten Ventures PLC (GROW.L)
- -11.03% - Reach PLC (RCH.L)
Up Next (Times in GMT)
How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.