



European Open: The DAX taps 13k ahead of ECB, Powell speech in focus
ECB day is here and we finally get to find out whether they’ll hike by 50 or 75bp, before handing over the mic to Jerome Powell.
Share this:
Asian Indices:
- Australia's ASX 200 index rose by 105 points (1.56%) and currently trades at 6,834.30
- Japan's Nikkei 225 index has risen by 568.14 points (2.08%) and currently trades at 28,001.19
- Hong Kong's Hang Seng index has fallen by -74.48 points (-0.39%) and currently trades at 18,969.82
- China's A50 Index has risen by 19.02 points (0.14%) and currently trades at 13,250.84
UK and Europe:
- UK's FTSE 100 futures are currently up 7 points (0.1%), the cash market is currently estimated to open at 7,244.83
- Euro STOXX 50 futures are currently up 14 points (0.4%), the cash market is currently estimated to open at 3,516.09
- Germany's DAX futures are currently up 50 points (0.39%), the cash market is currently estimated to open at 12,965.97
US Futures:
- DJI futures are currently up 19 points (0.06%)
- S&P 500 futures are currently up 20.25 points (0.17%)
- Nasdaq 100 futures are currently up 4 points (0.1%)
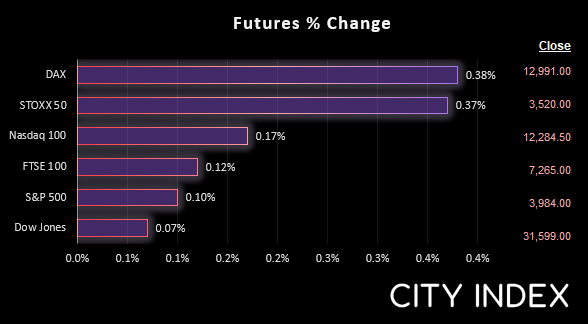

Asian equity markets were mostly higher overnight as they tracked Wall Street’s gains, and Japan’s benchmark took the lead as GDP figures from the region exceeded expectations. US and European futures markets are pointing higher ahead of the open, but we’ll have to wait and see if the current sentiment is maintained after Powell speaks at 14:10 BST today.
AUD falls following RBA Governor speech
RBA Governor Dr Philip Lower Dr Philip Low delivered a speech titled “Inflation and the Monetary Policy Framework” which hinted towards a slower pace of interest rate hikes. At least, that is how the market seemed to interpret it with AUD/USD erasing most of yesterday’s gains and the ASX 200 fully recouping yesterday’s losses.
In his comments, Dr Lowe said “the case for a slower pace of increase in interest rates becomes stronger as the level of the cash rate rises”. Well, I’d argue that is the case if inflation stops rising given the cash rate continue to lag inflation by a wide mile. And as his final comment was saying that how high rates go depends on incoming data, to me it really says Lowe doesn’t know when inflation will come down or what the RBA’s anticipated trajectory really is. So I suspect the Aussie selloff is a bit ahead of itself.
ECB are expected to hike interest rates today
The ECB (European Central Bank) raised rates in July for the first time in a decade. Today they will raise rates again, and the question is whether it will be by 50 or 75bp. With the Europe likely headed for double digit inflation then the case for a hawkish 75bp hike there. And like they did in the July meeting, ECB policy makers are also likely to express concerns over euro weakness – given it has since traded below parity since. But with Europe staring down the barrel of a recession, aggressive tightening won’t help fix high energy prices. So the ECB is caught between a rock and a hard place but on balance I suspect a 75b is on the cards (as it provided more room to cut when the inevitable recession makes its entry).
Jerome Powell in focus at 14:10 BST
With the Fed blackout period kicking in on Saturday, today’s speech by Jerome Powell could be the last chance we get for a mother of all hints ahead of the next FOMC meeting. Not only do we want a conclusion on whether the Fed will hike by 75bp or a ‘mere’ 50, we also want to know how many more of these there are to come. Given the hawkish comments from his colleagues this past week or so, I’m leaning towards a hawkish 75bp hint – as in expect 75bp
DAX (Germany 40 CFD) 4-hour chart:
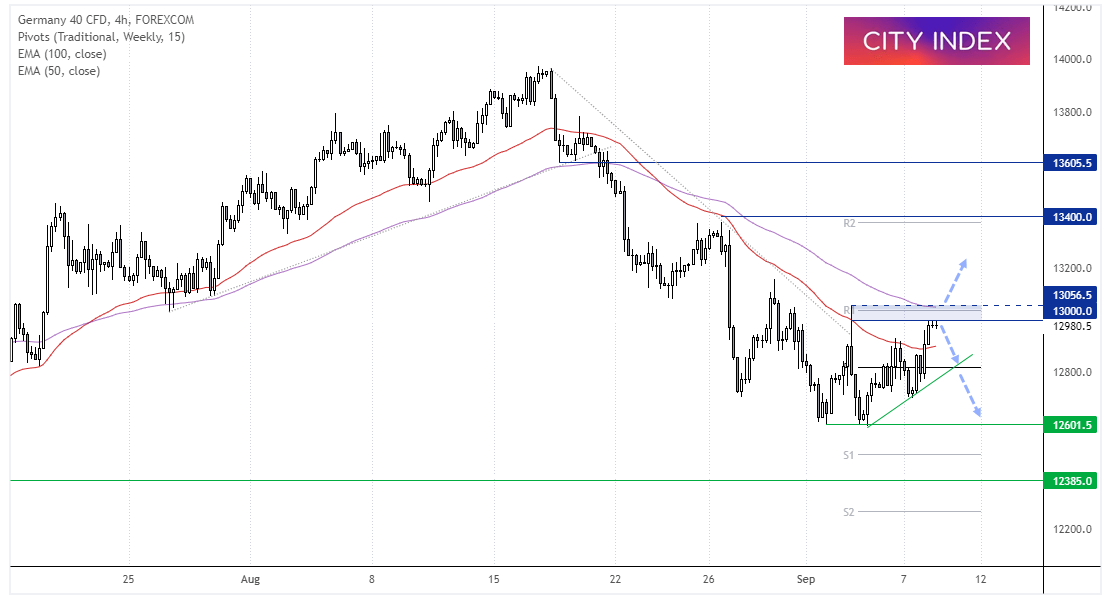

The 4-hour chart shows the DAX has risen to the 13,000 resistance zone ahead of today’s ECB meeting. It has also formed in three waves which suggests it is corrective, so we’re on the lookout for a potential swing high to signal the end of the correction. Also note that the 100-bar EMA and weekly R1 pivot are in the resistance zone, which adds extra weight to the area. Should we see evidence of a swing high then the initial downside target becomes 12,800 – near the weekly pivot point and trend support, a break beneath which brings 12,600 into focus.
The bias remains bearish beneath the 13,056 high – a break above which invalidates the 100-bar eMA and assumes bullish continuation.
FTSE 350 – Market Internals:


FTSE 350: 4011.63 (-0.86%) 07 September 2022
- 155 (44.29%) stocks advanced and 183 (52.29%) declined
- 5 stocks rose to a new 52-week high, 18 fell to new lows
- 22.86% of stocks closed above their 200-day average
- 96% of stocks closed above their 50-day average
- 2.86% of stocks closed above their 20-day average
Outperformers:
- + 10.61% - NCC Group PLC (NCCG.L)
- + 5.98% - Drax Group PLC (DRX.L)
- + 4.88% - Auction Technology Group PLC (ATG.L)
Underperformers:
- -5.90% - Marks and Spencer Group PLC (MKS.L)
- -5.87% - Investec PLC (INVP.L)
- -5.71% - WH Smith PLC (SMWH.L)
Economic events up next (Times in BST)
How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.