



European Open: Yields continue higher overnight, futures point lower
It was another day of red for equity traders as upside pressures on yields showed no signs of abating.
Share this:

Asian Indices:
- Australia's ASX 200 index fell by -76.3 points (-1.03%) and currently trades at 7,332.50
- Japan's Nikkei 225 index has fallen by -790.02 points (-0.28%) and currently trades at 27,467.23
- Hong Kong's Hang Seng index has fallen by -93.26 points (-0.39%) and currently trades at 24,019.52
- China's A50 Index has fallen by -113.61 points (-0.74%) and currently trades at 15,183.66
UK and Europe:
- UK's FTSE 100 futures are currently down -33 points (-0.44%), the cash market is currently estimated to open at 7,530.55
- Euro STOXX 50 futures are currently down -24.5 points (-0.58%), the cash market is currently estimated to open at 4,233.32
- Germany's DAX futures are currently down -77 points (-0.49%), the cash market is currently estimated to open at 15,695.56
US Futures:
- DJI futures are currently down -156 points (-0.44%)
- S&P 500 futures are currently down -103.5 points (-0.68%)
- Nasdaq 100 futures are currently down -24.5 points (-0.54%)

Asian equities were lower overnight as upside pressure on global bond yields persisted. The Australian 2-year bond rose 16 basis points to a two-year high, whilst the 5-year rose 23 bps. The Nikkei bared the brunt of selling as it fell -3%, taking a leaf from Nasdaq’s bearish book which fell -2.7% yesterday. China’s CSI300 and Australia’s ASX 200 were down around -1%.
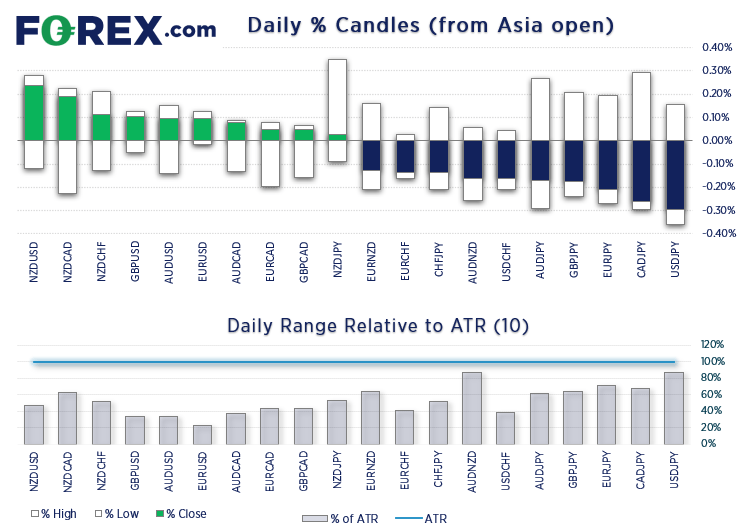
The yen caught a late-session bid
Currency markets were mostly quiet despite weak sentient for equities, yet in the past hour we’ve seen the Japanese yet move broadly higher against its forex major peers. USD/JPY has broken beneath yesterday’s lows and EUR/JPY broke key support.
UK inflation data is at 07:00 GMT
UK inflation rose to 5% according to December’s report which piled even more pressure on the BOE to raise rates. At the time, it was still unclear whether Omicron would derail the economy and the potential for the BOE to hike rates, yet the market have since decided all is fine and driven the British pound to a five-week high, as of last week during a short-covering rally. Unless we see some notably weak inflation numbers today (which we very much doubt) then the BOE are likely to be forced to hike rates in the coming weeks. Yet what is driving the pound lower this week is the markets renewed appetite for the dollar thanks to a hawkish Fed and bond-market sell-off.
EUR/GBP probes cycle low
A large bearish engulfing candle formed on the daily chart of EUR/GBP yesterday. Yield differentials between the two regions points to a downside break and trader have tried to push hit lower overnight. Yet we are urging caution at these lows given potential support levels nearby which diminish the potential reward/risk. The weekly S1 pivot sits at 0.8320, the monthly S1 at 0.8312 and historical support at 0.8304 (not to mention 0.8300 being a round number).
Of course, another potential catalyst is the ousting of Boris Johnson. But he was to be “out by Christmas” yet still clings on to power. And should he last the week it may even give the pound another boost.
GBP/CAD in focus for Canadian inflation
Just after lunch at 13:30 Canada will release their inflation report. Given the UK release theirs earlier in the day and GBP/CAD sits below a key resistance level, GBP/CAD is of interest. The daily chart has produced a head and shoulders top pattern which projects a target around 1.6823 and remains in play, so long as prices stay below the 1.7065 neckline.


However, and alternative scenario is a countertrend rally within a bearish channel. A Doji and bullish hammer have formed on this timeframe so if we see momentum turn higher then a swing low has formed. Yet a minor rally from current levels (and respect of 1.0765 resistance) suggests the H&S top is in play.
FTSE 350: Market Internals
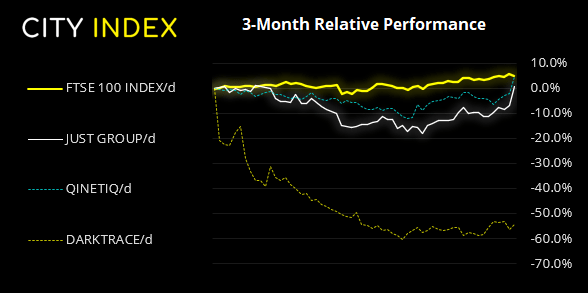

FTSE 350: 4287.22 (-0.68%), 19 January 2022
- 14 stocks rose to a new 52-week high, 20 fell to new lows
- 89 (25.36%) stocks advanced, 250 (71.23%) stocks declined
Outperformers:
- +8.237% - Just Group PLC (JUSTJ.L)
- +6.869% - Qinetiq Group PLC (QQ.L)
- +4.985% - Darktrace PLC (DARK.L)
Underperformers:
- ·-11.5% - Petropavlovsk PLC (POG.L)
- ·-8.07% - Trustpilot Group PLC (TRST.L)
- ·-7.583% - Chrysalis Investments Ltd (CHRY.L)
Up Next (Times in GMT)
How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.
DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.