



FOMC Recap: Warsh the Reformer as the Committee Shifts Hawkish
The FOMC was more hawkish than anticipated, with interest rates rising across the curve, stock indices edging lower, and the US dollar rallying - see what Chairman Kevin Warsh said and what it means!
Share this:
Federal Reserve, FOMC Key Points
- The Federal Reserve’s FOMC held interest rates in the 3.50-3.75% range, as expected.
- Nine of the 18 FOMC members now expect at least one interest rate increase this year, with six of those expecting multiple interest rate increases
- Traders are viewing the meeting as more hawkish than anticipated, with interest rates rising across the curve, stock indices edging lower, and the US dollar rallying.
FOMC Interest Rate Decision
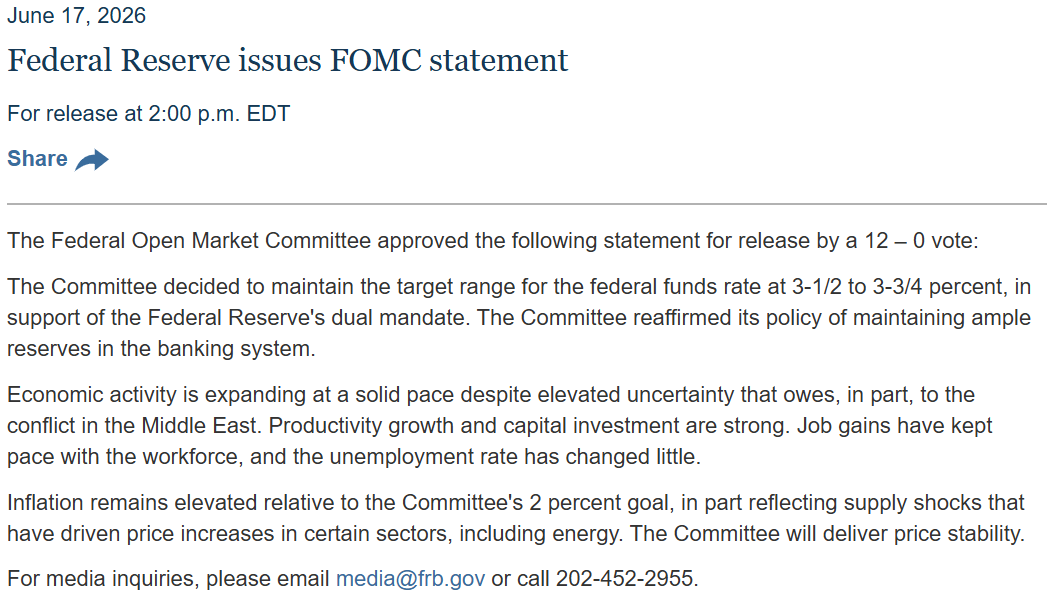
In a unanimous vote, the Federal Reserve’s FOMC kept interest rates unchanged in the 3.50-3.75% range, as expected.
There were no other changes to monetary policy at today’s meeting.
FOMC Monetary Policy Statement
In its accompanying monetary policy statement, the FOMC removed the controversial reference to “additional rate adjustments,” signaling a shift to a more balanced outlook for interest rates, while emphasizing elevated inflation and the importance of price stability.
More to the point, the statement was dramatically shorter in Chairman Kevin Warsh’s first meeting, down to just 130 words (from 400 under Powell), reflecting his push for less communication from the central bank:
Source: Federal Reserve
FOMC Summary of Economic Projections
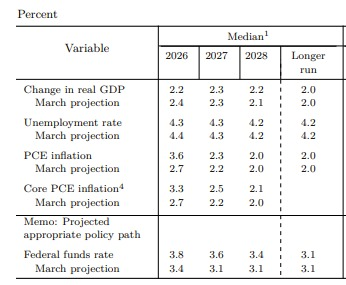
The median FOMC member made the following near-term adjustments to their quarterly economic forecasts, reflecting economic data and geopolitical developments over the last three months:
- 2026 GDP forecast revised DOWN from 2.4% to 2.2%
- 2026 Unemployment forecast revised DOWN from 4.4% to 4.3%
- 2026 Core PCE inflation forecast revised UP from 2.7% to 3.3%
The median FOMC member also revised their 2027 and 2028 inflation forecasts to 2.5% and 2.1% respectively.
Source: Federal Reserve
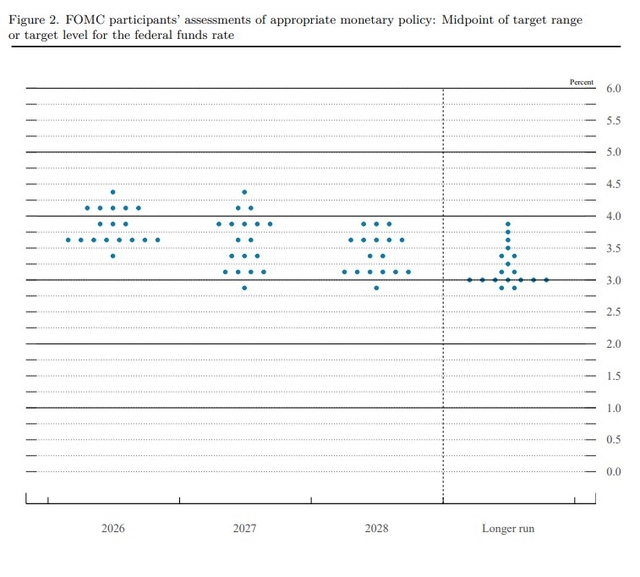
Not to bury the lede, the “dot plot” of interest rate expectations were the most market-moving development from the central banks economic projections. Nine of the 18 FOMC members now expect at least one interest rate increase this year, with six of those expecting multiple interest rate increases. The median FOMC member expects interest rates to average 3.8% at the end of this year (up from 3.4% in March), 3.6% at the end of 2027 (up from 3.1%), and 3.4% at the end of 2028 (up from 3.1%).
Source: Federal Reserve
Notably, Chairman Warsh did not submit economic projections, again reflecting his skepticism toward the whole endeavor.
In short, the committee appears to be broadly endorsing the market’s expectation for higher interest rates this year, and traders are accordingly pricing in about 34bps’ worth of hikes by the December FOMC meeting.
FOMC Chairman Warsh’s Press Conference
In his inaugural press conference as Chairman, Kevin Warsh positioned himself as reform-oriented, specifically announcing five new task forces to review everything from the central bank’s communication strategy to economic data sources to inflation frameworks. The Chairman also appeared to pour cold water on the necessity for continued press conferences after every meeting, implying that they might only be conducted “when there’s something important to say.”
In terms of the Fed’s dual mandate, Warsh stuck to the script, emphasizing “price stability” throughout the Q&A and only briefly mentioning the labor market when prompted at the end, contributing to the market’s hawkish interpretation of the meeting as a whole.
Highlights from his comments follow [emphasis mine]:
- WE RECOGNIZE INFLATION WELL AHEAD OF FED'S 2% GOAL
- PERSISTENTLY HIGH PRICES ARE A BURDEN TO THE AMERICAN PEOPLE
- RECENT PAST NEED NOT BE PROLOGUE ON INFLATION
- WE AGREED FORWARD GUIDANCE ISN'T WELL SUITED TO CURRENT JUNCTURE
- APPOINTING TASK FORCE IN FIVE AREAS OF MONETARY POLICY: 1. FED COMMUNICATIONS 2. FED'S BALANCE SHEET 3. USE AND RELIANCE ON EXISTING DATA SOURCES 4. PRODUCTIVITY AND JOBS 5. FED'S INFLATION FRAMEWORKS
- EXPECT TASK FORCES WILL BEGIN WORK IN NEXT COUPLE WEEKS, MOST WILL CONCLUDE BY YEAR END
- I SEE NO REASON TO REVISIT 2% INFLATION TARGET
- FED POLICY APPEARS TO BE RESTRICTIVE VIS A VIS HOUSING MARKET, BUT NOT FINANCIAL MARKETS
- WE'LL FIX FIVE YEARS OF MISSES ON INFLATION
- WANT TO HAVE SOMETHING IMPORTANT TO SAY FOR PRESSERS
- SOME CHANGES TO COME MAY BE WORTHY OF PRESS CONFERENCES
- FINANCIAL MARKET PRICES ARE THE MOST IMPORTANT SOURCE OF INFORMATION TO GUIDE CENTRAL BANKERS
- SOME ECON DATA WE RECEIVE MIGHT BE AN 'ECHO OF HISTORY'
- WE NEED TO MAKE SURE RISING PRICES DON'T BROADEN THROUGH THE ECONOMY
- WARSH DECLINES TO COMMENT ON ANY INTERACTIONS WITH TRUMP SINCE CONFIRMATION
- AI IS FILLED WITH OPPORTUNITY, RISKS
- NONE OF 19 AT TABLE FELT WE NEEDED TO TIGHTEN TODAY
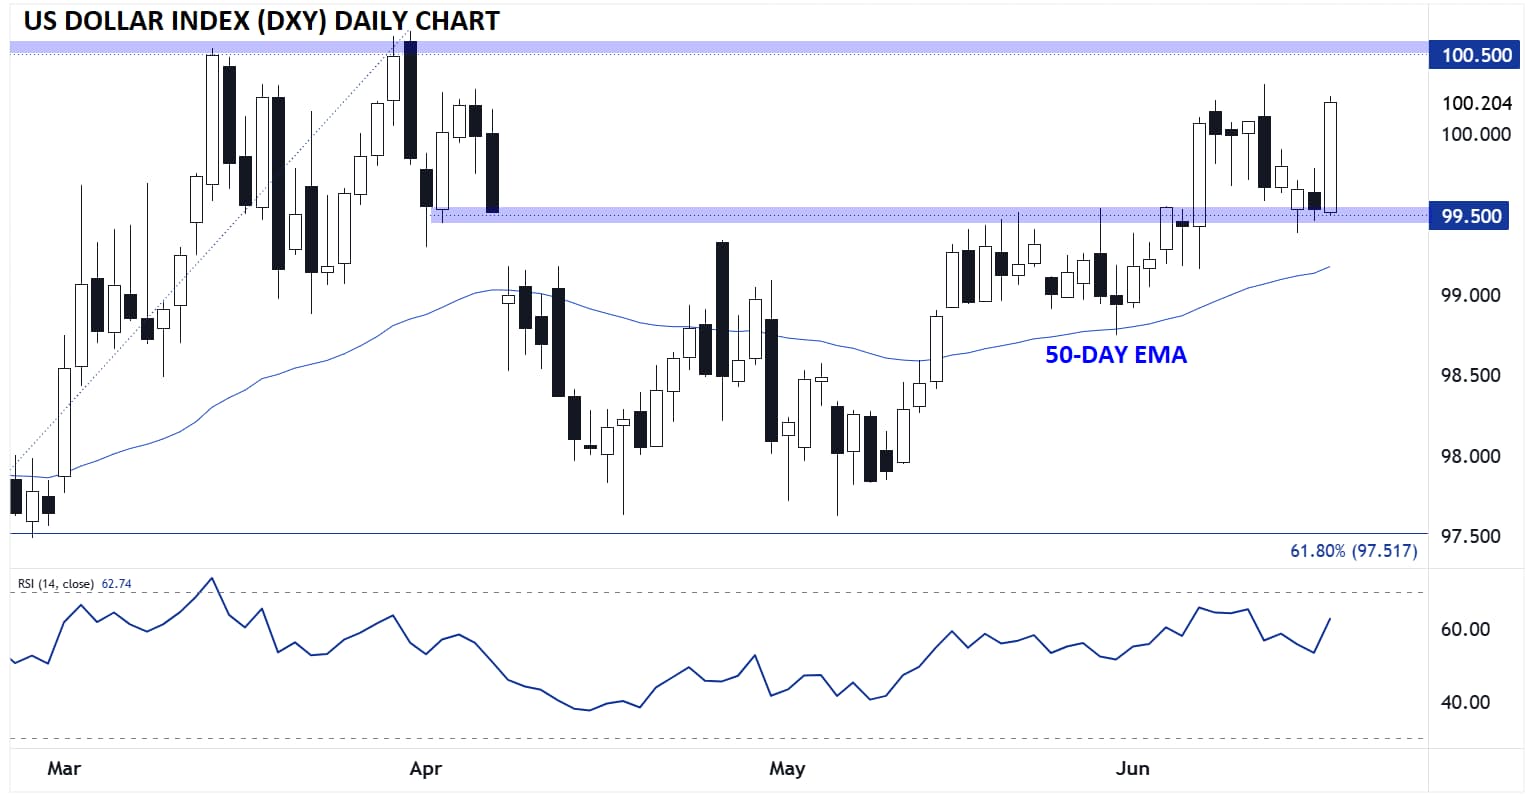
US Dollar Technical Analysis – DXY Daily Chart
Source: StoneX, TradingView
In terms of the market’s reaction, traders are viewing the meeting as more hawkish than anticipated, with interest rates rising across the curve, stock indices edging lower, and the US dollar rallying.
Focusing in on the latter, the US Dollar Index (DXY) has bounced strongly off 99.50 support to rally toward its highest level since the end of March. The 13-month high sits within striking distance at 100.50 and could serve as strong resistance if the greenback continues to rally in the coming days, a reasonable expectation given the more-hawkish-than-anticipated guidance in the SEP.
-- Written by Matt Weller, Global Head of Research
Check out Matt’s Daily Market Update videos on YouTube and be sure to follow Matt on Twitter: @MWellerFX
Latest market news

Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Price Action Setups: EUR/USD, USD/JPY, GBP/USD, USD/CAD
In a wide ranging webinar multiple USD pairs were in focus, continuing last week’s rally in DXY as EUR/USD tests 1.1000 and USD/JPY tests the 160.00 level.
EUR/USD outlook: euro back above 1.1000 as dollar rally loses steam
EUR/USD has recovered back above 1.1000 after a brief break lower, a sign the dollar's inflation-driven rally may be losing momentum. With a December Fed hike largely priced in and oil a potential tailwind for the euro, the risks are starting to tilt to the upside.

USD/CAD Forecast: Canadian Dollar Remains Under Pressure After Inflation Data
As the end of 2026 draws closer, one of the most notable themes in the currency market remains the weakness of the Canadian dollar against its U.S. counterpart. Over the past five trading sessions alone, USD/CAD has gained nearly 0.8%, highlighting the consistent strength that the U.S. dollar has continued to display.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.