



FTSE 100 forecast: Technical Tuesday August 12, 2025
n this version of Technical Tuesday, we’re looking at the key drivers shaping global markets, UK economic data, and what technical signals are telling us about the near-term FTSE 100 forecast. Markets were quite quiet in the early parts of Tuesday’s trade, awaiting the release of key US CPI report, which later came in slightly lower than expected and that was enough to send US futures sharply higher....
Share this:
Markets were quite quiet in the early parts of Tuesday’s trade, awaiting the release of key US CPI report, which later came in slightly lower than expected and that was enough to send US futures sharply higher. Despite a weaker start to the day, sentiment was overall positive, as Trump extended the pause on China’s tariffs for another 90. In the UK, we had some mixed data earlier, which kept the FTSE and pound supported, while the weakness in German ZEW data hurt both the DAX and the euro. In this version of Technical Tuesday, we’re looking at the key drivers shaping global markets, UK economic data, and what technical signals are telling us about the near-term FTSE 100 forecast.
Chinese tariffs pause extended
The big news overnight was that Donald Trump has indeed extended the pause on higher tariffs on Chinese goods for another 90 days, until November 10. This was hardly surprising truth be told. The extension gives both sides more time to negotiate and aims to stabilise trade relations between the world’s two largest economies. Had this truce not been extended, the consequences for China and the markets would have been dire. US tariffs on Chinese goods would have jumped to at least 54% today. So, this is clearly a relief for markets. Yet, the lack of a more meaningful rally in global markets overnight suggests the move was priced in. But is the extension really good news? On the one hand, the extension does provide relief that another trade war is averted. But on the other, some would argue it prolongs uncertainty. So, markets didn’t know how to react to the news, although the lack of volatility suggests calm remains the order of the day.
What about inflation concerns?
Since April, markets worldwide, including the FTSE 100, have rallied strongly. This is partly due to easing fears around the trade war and central banks gradually cutting interest rates, which has further fuelled the rally. Inflation concerns, however, have not gone away. Many economists believe Trump’s tariffs will eventually be passed on to consumers. But this wasn’t clearly evidenced in yet another inflation report from the US, released moments ago.
US CPI came in unchanged at 2.7% on a year-over-year basis compared to 2.8% expected, while the month-over-month rate was in line at 0.2% in July. Core measure of CPI was little bit higher than expected, with a print of 0.3% m/m, which helped to push up the y/y rate to 3.1% from 3.0%.
If US and global inflation starts to accelerate again in the coming months, consumers’ purchasing power will be squeezed even more. Meanwhile, central banks might have to keep interest rates higher than they’d like to, which means borrowing costs remain high.
This combination could hit consumer spending hard, ultimately hurting company profits and their share prices.
UK wages fall more than expected
Earlier today, we had some mixed data from the UK following last week’s Bank of England rate cut, which was a very close call when policymakers were sharply divided but ultimately agreed to cut rates.
Today’s data showed average earnings increased by 4.6% in the three months to June compared to a year ago — weaker than the 5.0% rise we saw the previous month. On the jobs front, employment has now fallen eight times in the past nine months. However, the latest drop of 8,000 jobs is the smallest decline so far, suggesting the labour market may be stabilising.
A weakening jobs market could ease wage inflation pressures and open the door to further rate cuts, but whether this happens at November’s meeting remains uncertain following that hawkish cut last week, meaning the chance of another cut in November is now lower.
Meanwhile, a UK data dump is scheduled for Thursday when we will have Q2 GDP as well as monthly data on construction output, manufacturing production and a few other indicators to look forward to. The odds of a further BoE rate cut this year will continue to tumble in the event we see stronger data from the UK this week. Whether this will weigh on the FTSE 100 forecast is difficult to say, given that the index’s components are major global corporations that rely more on sales out of the UK.
FTSE 100 forecast: Key levels to watch
From a technical point of view, the FTSE 100 forecast remains positive for now. The FTSE is holding steady inside a short-term consolidation pattern near its recent record high of 9,191.
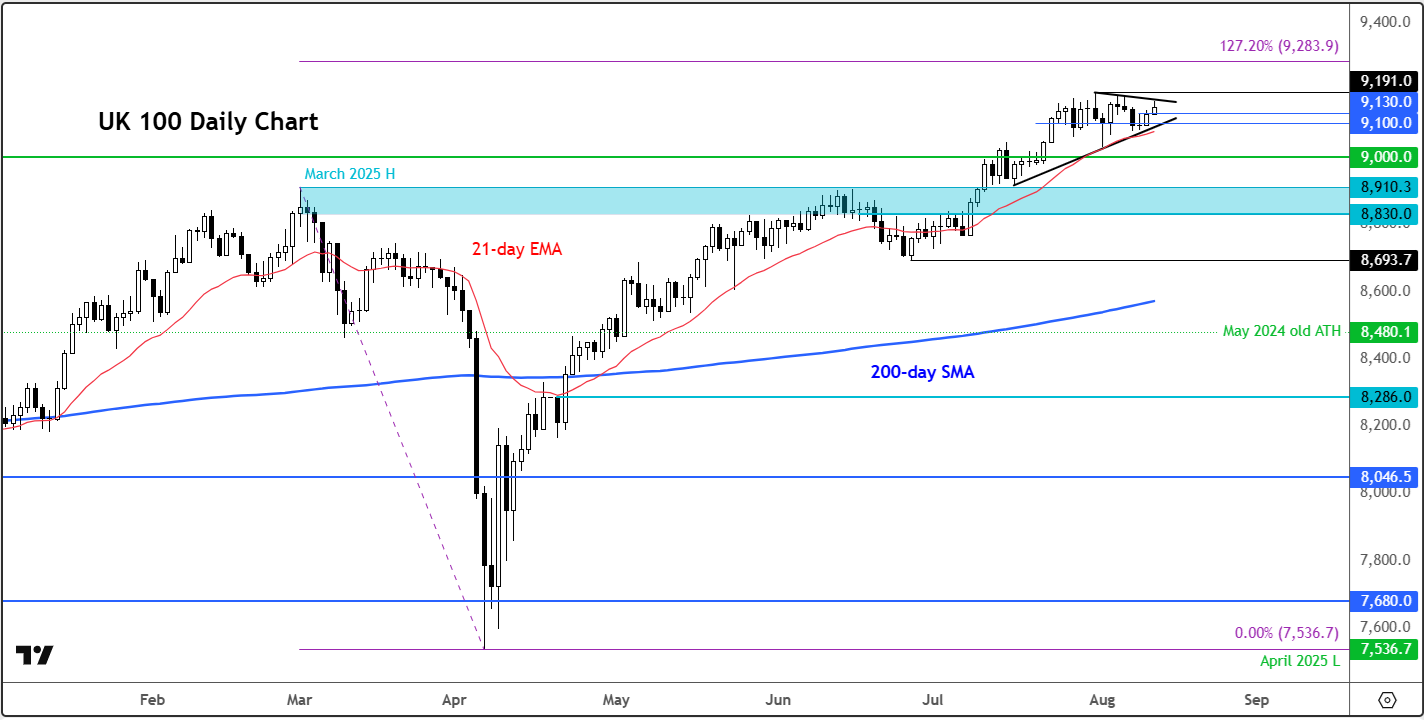
This consolidation is helping to ease overbought conditions on short-term indicators — which is generally a bullish sign.
The FTSE remains above its main moving averages and has broken through several resistance levels.
This means the path of least resistance points clearly upwards.
Until we see clear signs of a market top, the strategy remains to look for dip-buying opportunities and target new highs.
Key short-term support levels to watch are 9,135, 9,100, and 9,050. Longer-term support is seen around 9,000 and the area between 8,830 to 8,910 (shaded in blue on the chart).
On the upside, resistance comes in at 9,165/75, marking the bearish trend line of the consolidation pattern, then the all-time high of 9,191 will be in focus next.
-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.

EUR/USD forecast: Dollar strength puts 1.1000 support in the spotlight | Currency Pair of the Week
The dollar extended its recent advance at the start of the week, with weakness across risk-sensitive assets reinforcing demand for the US currency. US equity futures slipped ahead of Nvidia’s earnings on Tuesday and an expected stock market debut by Anthropic later this week. Both events represent important tests for an AI trade that has become increasingly vulnerable to shifts in sentiment. In FX, EUR/USD nearly tested the psychologically important 1.1000 level, before bouncing modestly off its lows.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.