




FTSE breaks higher on dovish BoE
The BoE echoed the views of several other major banks which have provided similar views or even more dovish outlook on their respective monetary policies i.e. global interest rates will remain at or near record low levels for the foreseeable future.
Share this:

Following the BoE’s policy announcement earlier, which was deemed to be more dovish than anticipated, the pound dropped and this helped to lift the FTSE to a fresh high for the week after the index had spent several days in consolidation. The BoE echoed the views of several other major banks which have provided similar views or even more dovish outlook on their respective monetary policies i.e. global interest rates will remain at or near record low levels for the foreseeable future. For that reason, equity indices continue to remain supported, keeping the bears at bay despite raised geopolitical tensions and concerns over global demand hurting company earnings.
Speaking of geopolitics, the FTSE was also supported by rising shares of oil majors which tracked crude prices higher. Raised geopolitical tensions continue to support oil prices at the moment, even if Saudi Arabia’s crude output could return to normal sooner than expected. But following Saturday’s attacks, investors have realised that production even in Saudi is at risk of outages due to rebel fighting or terrorist activity — something which looked almost impossible last week. This is why oil prices have been hesitant to quickly close their gaps created at the open this week.
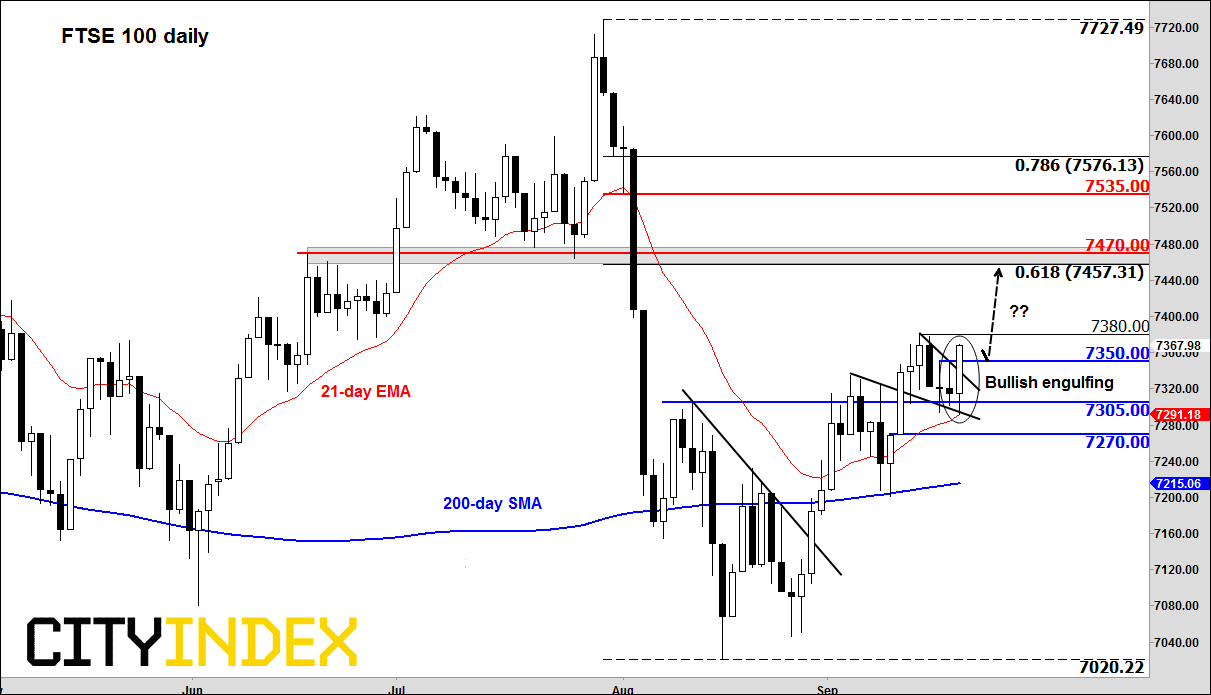
As mentioned, the FTSE has moved to a new high for the week after breaking out of its consolidation. It is currently displaying a bullish engulfing candle on its daily chart, suggesting that the bears have been defeated after their attempt to move the index below the 200-day moving average, failed. With the bears apparently defeated, they may now move out of the way and consequently the index could accelerate to the upside over the coming days. Yesterday’s high at 7350 could be the key short term support to watch moving forward. Beyond last week’s high at 7375/80, the next major bullish objective is around 7455/70, an area which was previously support and where the 61.8% Fibonacci level converges.
Source: eSignal and City Index. Please note this product may not be available to trade in all regions.
Following the BoE’s policy announcement earlier, which was deemed to be more dovish than anticipated, the pound dropped and this helped to lift the FTSE to a fresh high for the week after the index had spent several days in consolidation. The BoE echoed the views of several other major banks which have provided similar views or even more dovish outlook on their respective monetary policies i.e. global interest rates will remain at or near record low levels for the foreseeable future. For that reason, equity indices continue to remain supported, keeping the bears at bay despite raised geopolitical tensions and concerns over global demand hurting company earnings.
Speaking of geopolitics, the FTSE was also supported by rising shares of oil majors which tracked crude prices higher. Raised geopolitical tensions continue to support oil prices at the moment, even if Saudi Arabia’s crude output could return to normal sooner than expected. But following Saturday’s attacks, investors have realised that production even in Saudi is at risk of outages due to rebel fighting or terrorist activity — something which looked almost impossible last week. This is why oil prices have been hesitant to quickly close their gaps created at the open this week.
As mentioned, the FTSE has moved to a new high for the week after breaking out of its consolidation. It is currently displaying a bullish engulfing candle on its daily chart, suggesting that the bears have been defeated after their attempt to move the index below the 200-day moving average, failed. With the bears apparently defeated, they may now move out of the way and consequently the index could accelerate to the upside over the coming days. Yesterday’s high at 7350 could be the key short term support to watch moving forward. Beyond last week’s high at 7375/80, the next major bullish objective is around 7455/70, an area which was previously support and where the 61.8% Fibonacci level converges.
Source: eSignal and FOREX.com. Please note this product may not be available to trade in all regions.
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 forecast: Why US stocks have largely defied gravity and what could trigger a correction
Though we have seen some weakness in US stock markets recently, this has been nothing compared to the percentage drops we have seen this year for Bitcoin, silver and several major Asia pacific equity markets. The divergence raises an important question: is S&P 500 genuinely insulated from the forces weighing on other assets, or is it simply taking longer for the weakness to spread?


VIX Short Covering Surges as Traders Reassess Stock Market Risk
VIX futures shorts tumble as S&P 500 bearish bets rise. The latest COT report reveals significant shifts in equity and commodity positioning.


Nikkei swings harder than Nasdaq as AI fears deepen
Nikkei 225 volatility is running well ahead of Nasdaq 100, with the index construction and Japan's heavy exposure to AI manufacturing potentially explaining the difference.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.