




Lloyds flags uncertainty for outlook warning
Beyond Lloyds Banking Group's missed forecasts, the weakening outlook weighs more
Share this:

A last-minute surge of PPI costs damped the quarter but that is the least of the bank’s worries
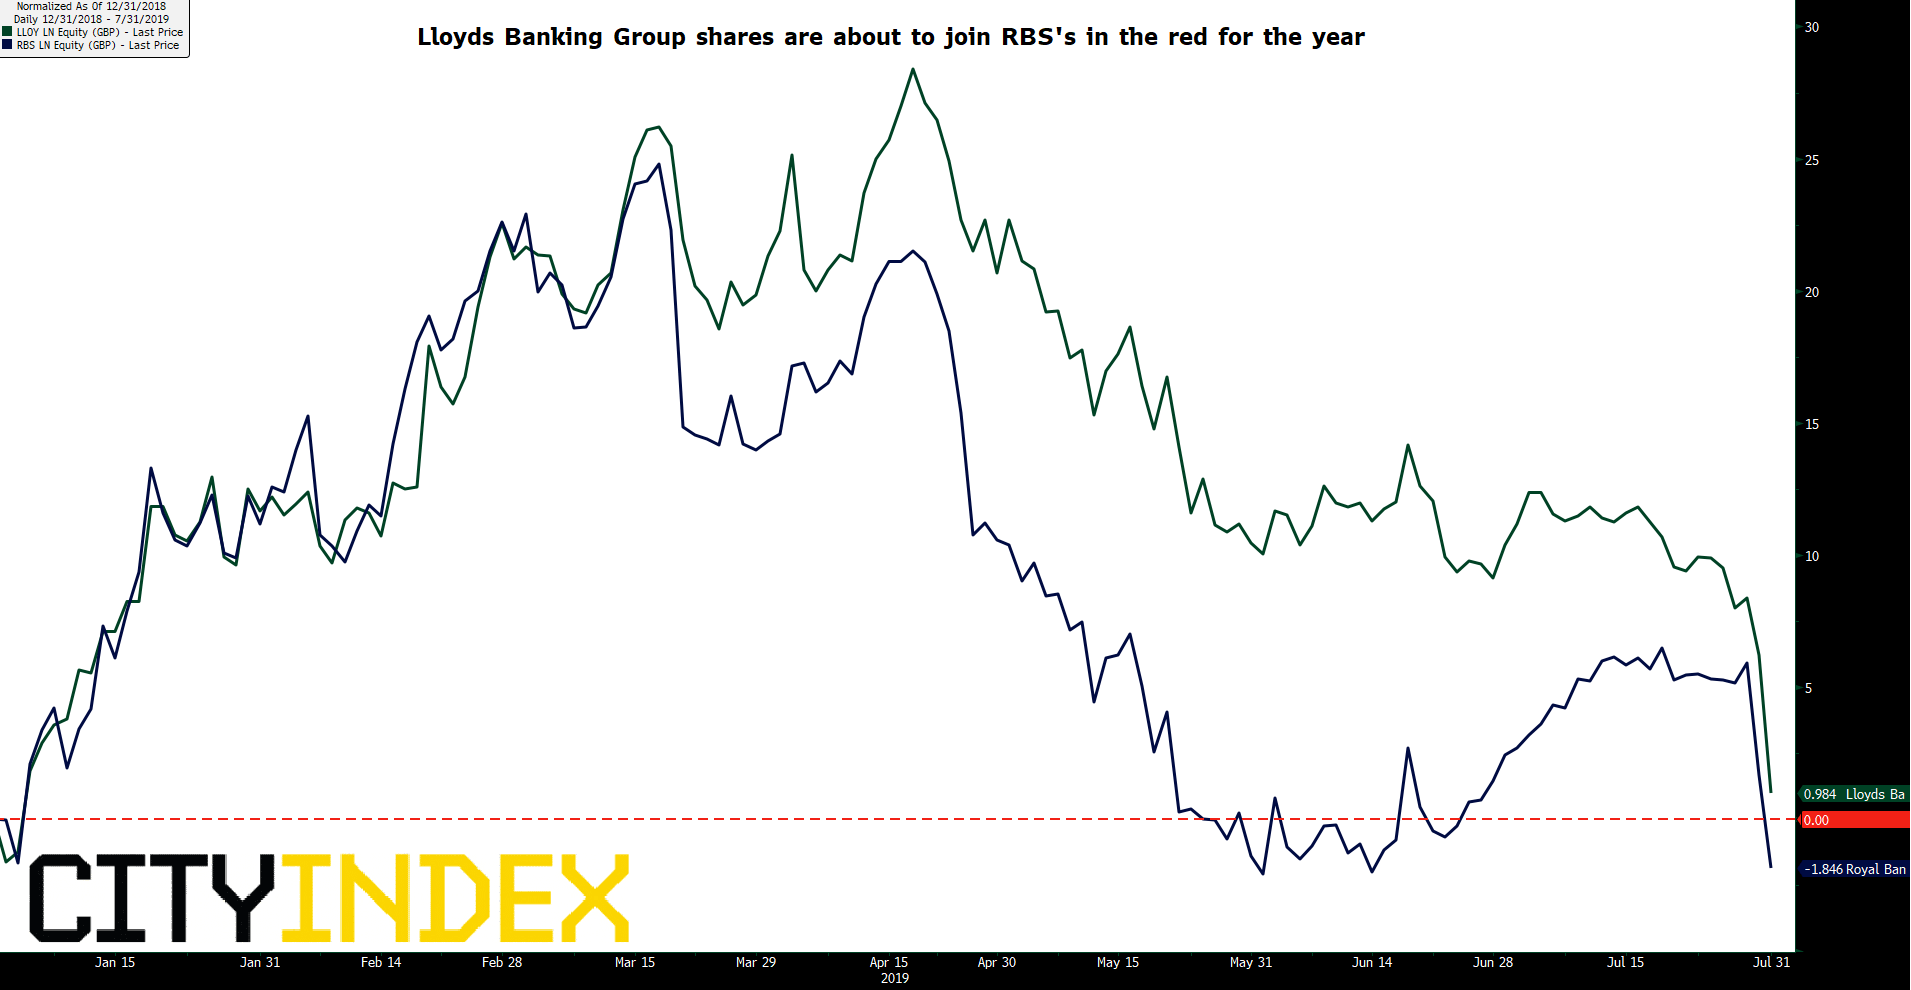
It’s difficult to see how Lloyds Banking Group could have performed more robustly given the specific challenges of the quarter. Looked at this way, perhaps the accelerated downturn of its shares on Wednesday is not entirely justified. The bigger picture helps explain why investor confidence continues to ebb. At last check, the shares had trimmed 4% more off a 2019 advance that stood almost 30% higher at mid-April. Now, they’re barely up 2% for the year and looking likely to turn negative.
The bank points to a fresh charge of £500m linked to payment protection insurance (PPI) as primarily responsible for missed second-quarter expectations.
The key misses
- Statutory pre-tax profit: £1.294bn vs. £1.76bn estimate
- 2Q net interest income: £3.06bn vs. £3.16bn consensus
- 2Q underlying profit: £2.03bn, below company-compiled £2.05bn consensus
- 2Q net interest margin: 2.89% vs. 2.94% estimate
Bloomberg consensus unless specified
But beyond the headline misses, the outlook weighs more. Hopes were pinned on the possibility that rising efficiency and lower regulatory and business capital needs, could enable swifter dividends rises and share buybacks. The interim dividend rose 5% to 1.12 pence; in line with expectations, which is exactly the point.
“Below the line charges”, including the last-minute wave of PPI costs have scuppered those hopes for now. Lloyds’ boast of sufficient capital for growth, regulatory requirements, uncertainty and a ‘management buffer’, have come a cropper as it now expects 2019 leeway to be at the lower end of a 170-200 basis point range. It implies that’s the reason why it’s holding back from a nearer term increase of capital returns. A fairly solid first-half despite misses adds a random variable.
- Total costs fell a more than forecast 5%, operating costs -3%
- Cost: income ratio on course for low 40% levels by end-2020, better than comparable rivals
- The wealth management push is bearing early fruit whilst insurance is stable
“Continued economic uncertainty could impact” the outlook as clarified on Wednesday, the bank says. Despite economic “resilience” it is nodding to Brexit risks for a decision to hang fire on pay-outs, perhaps for even longer than the first quarter of 2020.
More broadly, if the first half was sobering for Lloyds investors, it should be more worrying for RBS holders. They will find out how that bank fared in the first half on Friday. RBS faces a sharper delta from declining economic confidence and is the runner-up in Britain’s mortgage market. The stock was down 3% at time of writing and is slightly weaker for the year than Lloyds’. On the basis of results from its bigger rival, it’s set to continue leading the downside.
Normalised: Lloyds Banking Group, RBS – year-to-date [31/07/2019 13:14:42]
Source: Bloomberg/FOREX.com
A last-minute surge of PPI costs damped the quarter but that is the least of the bank’s worries
It’s difficult to see how Lloyds Banking Group could have performed more robustly given the specific challenges of the quarter. Looked at this way, perhaps the accelerated downturn of its shares on Wednesday is not entirely justified. The bigger picture helps explain why investor confidence continues to ebb. At last check, the shares had trimmed 4% more off a 2019 advance that stood almost 30% higher at mid-April. Now, they’re barely up 2% for the year and looking likely to turn negative.
The bank points to a fresh charge of £500m linked to payment protection insurance (PPI) as primarily responsible for missed second-quarter expectations.
The key misses
- Statutory pre-tax profit: £1.294bn vs. £1.76bn estimate
- 2Q net interest income: £3.06bn vs. £3.16bn consensus
- 2Q underlying profit: £2.03bn, below company-compiled £2.05bn consensus
- 2Q net interest margin: 2.89% vs. 2.94% estimate
Bloomberg consensus unless specified
But beyond the headline misses, the outlook weighs more. Hopes were pinned on the possibility that rising efficiency and lower regulatory and business capital needs, could enable swifter dividends rises and share buybacks. The interim dividend rose 5% to 1.12 pence; in line with expectations, which is exactly the point.
“Below the line charges”, including the last-minute wave of PPI costs have scuppered those hopes for now. Lloyds’ boast of sufficient capital for growth, regulatory requirements, uncertainty and a ‘management buffer’, have come a cropper as it now expects 2019 leeway to be at the lower end of a 170-200 basis point range. It implies that’s the reason why it’s holding back from a nearer term increase of capital returns. A fairly solid first-half despite misses adds a random variable.
- Total costs fell a more than forecast 5%, operating costs -3%
- Cost: income ratio on course for low 40% levels by end-2020, better than comparable rivals
- The wealth management push is bearing early fruit whilst insurance is stable
“Continued economic uncertainty could impact” the outlook as clarified on Wednesday, the bank says. Despite economic “resilience” it is nodding to Brexit risks for a decision to hang fire on pay-outs, perhaps for even longer than the first quarter of 2020.
More broadly, if the first half was sobering for Lloyds investors, it should be more worrying for RBS holders. They will find out how that bank fared in the first half on Friday. RBS faces a sharper delta from declining economic confidence and is the runner-up in Britain’s mortgage market. The stock was down 3% at time of writing and is slightly weaker for the year than Lloyds’. On the basis of results from its bigger rival, it’s set to continue leading the downside.
Normalised: Lloyds Banking Group, RBS – year-to-date [31/07/2019 13:14:42]
Source: Bloomberg/City Index
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nvidia Earnings Preview: NVDA’s First Test of the Post Jenson Huang Era
Nvidia is expected to report $2.47 in EPS on $108.8B in revenue this quarter, but investors will be more interested in the company's guidance after the unexpected departure of founder and CEO Jenson Huang.

Nvidia Holds Support Ahead of Earnings as Nasdaq 100 Rebounds
Nvidia shares approach major support as selling pressure eases, while the Nasdaq 100 rebounds. Could upcoming earnings fuel a broader recovery?

S&P 500 Analysis: Earnings Uncertainty Continues to Weigh on the SPX
The trading week is coming to an end, and a phase of weakness remains evident across the S&P 500 in the short term. Recent price action reflects this dynamic, with SPX losing more than 2.00% over the last two trading sessions, bringing selling pressure back into focus.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.