




Market Brief GBP Walloped as NoDeal Brexit Fears Return
See a summary of the top market themes and trends from today's US trading session!
Share this:

View our guide on how to interpret the FX Dashboard.
- US data: US Industrial Production (Nov) came in at +1.1%, above expectations of a 0.8% rise. US Housing Starts (Nov) also beat expectations at 1.365M annualized vs. 1.345M expected. The JOLTS report showed a higher-than-expected 7.267M job openings.
- The Atlanta Fed’s GDPNow estimate of Q4 growth rose to 2.3% as a result of recent solid data out of the US. The next report comes out on Friday.
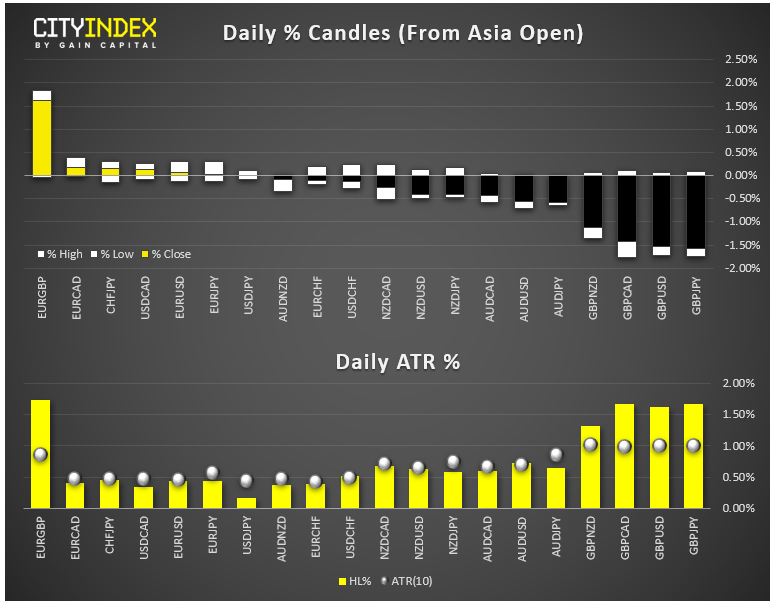
- FX: The British pound was by far the weakest major currency as PM Boris Johnson put a no-deal Brexit back on the table. GBP/USD has now retraced its entire election surge from last week to trade back near 1.31.
- The New Zealand dollar also fell after the biweekly GDT auction showed prices of dairy products, a key export, fell -5.1%. The Swiss franc was the strongest major currency on the day.
- Commodities: Oil gained 1% on the day while gold was essentially flat.

- US indices closed modestly higher on the day. European indices closed mixed, with the UK FTSE 100 flat, while bourses in Germany and France fell. Italy’s FTSE MIB bucked the trend to close the day higher.
- Financials (XLF) were the strongest major sector today; REITs (XLRE) brought up the rear.
- Stocks on the move:
- Netflix (NFLX) gained 4% after revealing strong growth data in overseas economies
- UK healthcare provider NMC Health (NMC) dumped -32% as noted short seller Muddy Waters Research revealed a bearish position in the stock.

View our guide on how to interpret the FX Dashboard.
- US data: US Industrial Production (Nov) came in at +1.1%, above expectations of a 0.8% rise. US Housing Starts (Nov) also beat expectations at 1.365M annualized vs. 1.345M expected. The JOLTS report showed a higher-than-expected 7.267M job openings.
- The Atlanta Fed’s GDPNow estimate of Q4 growth rose to 2.3% as a result of recent solid data out of the US. The next report comes out on Friday.
- FX: The British pound was by far the weakest major currency as PM Boris Johnson put a no-deal Brexit back on the table. GBP/USD has now retraced its entire election surge from last week to trade back near 1.31.
- The New Zealand dollar also fell after the biweekly GDT auction showed prices of dairy products, a key export, fell -5.1%. The Swiss franc was the strongest major currency on the day.
- Commodities: Oil gained 1% on the day while gold was essentially flat.

- US indices closed modestly higher on the day. European indices closed mixed, with the UK FTSE 100 flat, while bourses in Germany and France fell. Italy’s FTSE MIB bucked the trend to close the day higher.
- Financials (XLF) were the strongest major sector today; REITs (XLRE) brought up the rear.
- Stocks on the move:
- Netflix (NFLX) gained 4% after revealing strong growth data in overseas economies
- UK healthcare provider NMC Health (NMC) dumped -32% as noted short seller Muddy Waters Research revealed a bearish position in the stock.

Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.