






Market Brief Mixed Repsonse From Trade Developments
A summary of news and snapshot of moves from today’s Asia session.
Share this:

- US and China are to resume in person trade talks in September, after Trump said discussion were already on the way later today. On Sunday, the US is set to collect a further 15% on Chinese imports worth over $125 billion.
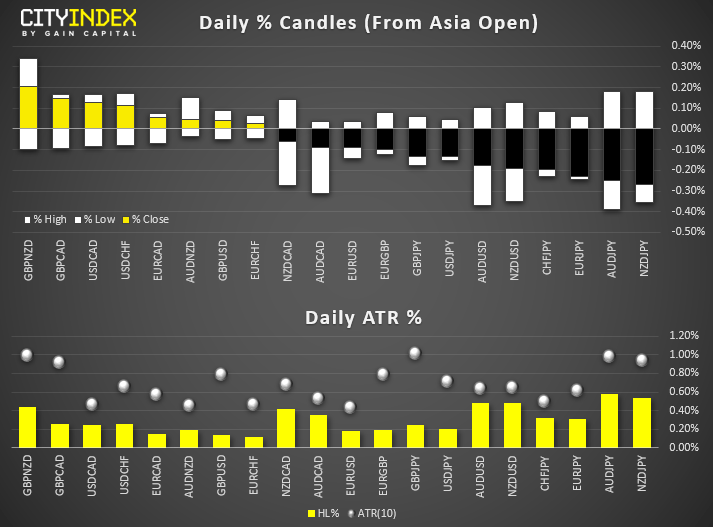
- Whilst this provided a slight tailwind for equities, currency markets were less convinced. AUD and NZD trading firmly lower and are today’s weakest majors (JPY and UD are the strongest). Still, NZD is still reeling form yesterday’s dire business confidence reads, and AUD is under the added pressure of weaker building approvals and housing credit. And looking tariffs which kick on Sunday, along with lower iron ore prices for AUD are also piling on the pressure.
- Mixed data from Japan saw industrial production rebound and retail sales slump. Production rose 1.3% in July (although is -1% % YoY) with expectations for the next 1-2 months at 2.7% and 0.6% respectively, despite concerns over the trade war. Whilst this is good for the business sector, retail sales slumped by 2.5% (fastest contraction since November 2015) to take the YoY rate to -2%. Unemployment fell to 2.2%, its lowest rate since August 1992.
- Asian stock indices have continued to recoup last week’s losses on the theme of “U.S/China trade deal optimism’” where China’s commerce ministry commented yesterday that a Sep meeting was being discussed but added it was important for Washington to cancel a tariff increase. A new round of U.S. tariffs, 15% on US$550 billion worth of Chinese goods is scheduled to take effect on this Sun.
- The best performers are Kospi 200, ASX 200 and Nikkei 225 which have gained by more than 1.00% as at today’s Asian mid-session.
- Interestingly, China A50 has underperformed against the rest where it has inched up only by 0.30%. A firm USD/CNH could be the reason that prevent traders from taking aggressive long positions. The USD/CNH (offshore yuan) has started to recoup yesterday’s losses where it rebounded by 196 pips at the 7.1400/1300 key short-term support to print a current intraday high of 7.1602 in today’s Asia session.
- Hong Kong’s Hang Seng Index’s gains have been lacklustre due to on-going localised social unrest. It has been reported that local police have arrested three prominent protest leaders ahead of planned mass demonstrations this weekend. Key property developer stocks underperformed where Sun Hung Kai Properties, Swire Pacific and CK Assets have traded down by -2.65%, -1.22% and -1.28% respectively.
Up Next
- Hong Kong Retail Sales for Jul out later today at 0830 GMT. Data for Jun came in at -7.6% y/y/ where another round of weak data for Jul is likely to reinforce a technical recession in Q3 for Hong Kong. Q2 GDP came in at -0.4% q/q.
- Canadian GDP is expected to rebound from 0.4% YoY to 3%. Whilst data overall continues to favour BoC not easing, a miss for GDP later today could rattle CAD crosses. However, hittig or exceeding expectations could provide a tailwind for their stock index (TSX 60) which appears to the first of the major indices to break higher form its range.

- US and China are to resume in person trade talks in September, after Trump said discussion were already on the way later today. On Sunday, the US is set to collect a further 15% on Chinese imports worth over $125 billion.
- Whilst this provided a slight tailwind for equities, currency markets were less convinced. AUD and NZD trading firmly lower and are today’s weakest majors (JPY and UD are the strongest). Still, NZD is still reeling form yesterday’s dire business confidence reads, and AUD is under the added pressure of weaker building approvals and housing credit. And looking tariffs which kick on Sunday, along with lower iron ore prices for AUD are also piling on the pressure.
- Mixed data from Japan saw industrial production rebound and retail sales slump. Production rose 1.3% in July (although is -1% % YoY) with expectations for the next 1-2 months at 2.7% and 0.6% respectively, despite concerns over the trade war. Whilst this is good for the business sector, retail sales slumped by 2.5% (fastest contraction since November 2015) to take the YoY rate to -2%. Unemployment fell to 2.2%, its lowest rate since August 1992.
- Asian stock indices have continued to recoup last week’s losses on the theme of “U.S/China trade deal optimism’” where China’s commerce ministry commented yesterday that a Sep meeting was being discussed but added it was important for Washington to cancel a tariff increase. A new round of U.S. tariffs, 15% on US$550 billion worth of Chinese goods is scheduled to take effect on this Sun.
- The best performers are Kospi 200, ASX 200 and Nikkei 225 which have gained by more than 1.00% as at today’s Asian mid-session.
- Interestingly, China A50 has underperformed against the rest where it has inched up only by 0.30%. A firm USD/CNH could be the reason that prevent traders from taking aggressive long positions. The USD/CNH (offshore yuan) has started to recoup yesterday’s losses where it rebounded by 196 pips at the 7.1400/1300 key short-term support to print a current intraday high of 7.1602 in today’s Asia session.
- Hong Kong’s Hang Seng Index’s gains have been lacklustre due to on-going localised social unrest. It has been reported that local police have arrested three prominent protest leaders ahead of planned mass demonstrations this weekend. Key property developer stocks underperformed where Sun Hung Kai Properties, Swire Pacific and CK Assets have traded down by -2.65%, -1.22% and -1.28% respectively.
Up Next
- Hong Kong Retail Sales for Jul out later today at 0830 GMT. Data for Jun came in at -7.6% y/y/ where another round of weak data for Jul is likely to reinforce a technical recession in Q3 for Hong Kong. Q2 GDP came in at -0.4% q/q.
- Canadian GDP is expected to rebound from 0.4% YoY to 3%. Whilst data overall continues to favour BoC not easing, a miss for GDP later today could rattle CAD crosses. However, hittig or exceeding expectations could provide a tailwind for their stock index (TSX 60) which appears to the first of the major indices to break higher form its range.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.
DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.


EUR/USD forecast: Dollar strength puts 1.1000 support in the spotlight | Currency Pair of the Week
The dollar extended its recent advance at the start of the week, with weakness across risk-sensitive assets reinforcing demand for the US currency. US equity futures slipped ahead of Nvidia’s earnings on Tuesday and an expected stock market debut by Anthropic later this week. Both events represent important tests for an AI trade that has become increasingly vulnerable to shifts in sentiment. In FX, EUR/USD nearly tested the psychologically important 1.1000 level, before bouncing modestly off its lows.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.