




Market Brief NZD Bulls Shaken Out On Soft Data
A summary of news and snapshot of moves from today’s Asia session.
Share this:

View our guide on how to interpret the FX Dashboard
- Earlier in the session, the NZ government announced further infrastructure spending alongside a boost in fiscal spending in 2020. However, SEEK job advertisements since September’s spike has been lacklustre, which brings doubt to the strength of the employment market as we head into 2020. That said, market reaction may be a little overdone considering the positive news flows seen from NZ of late.
- Markets remain in a holding pattern whilst Trump decides whether to adds tariffs to $160 billion of Chinese goods over the weekend. Whilst there have been mixed reports over a potential delay, advisors are to meet with Trump over the coming days to hopefully finalise the decision (or leave the markets risk to weekend gaps if no decision has been announced before Sunday’s deadline).
- House Democrats formerly announced impeachment charges against President Trump, a move which is likely to result in a Republican-led Senate trial early next year.
Price Action:
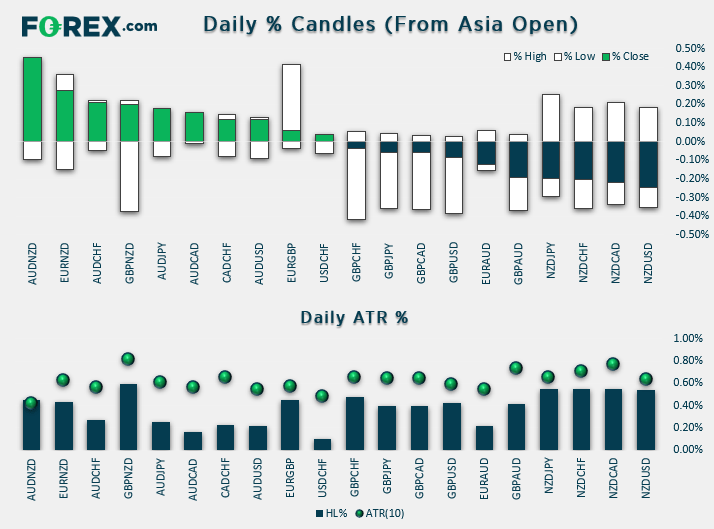
- NZD is the weakest major and the most volatile (as it quiet elsewhere ahead of today’s FOMC meeting and CPI data).
- AUD/NZD is the largest gainer and enjoying its largest daily gain in a month. Having failed to break below a bullish trendline and the 1.40 handle, it likely marks the beginning of a much-needed correction. However, it’s moved 108% of is typical ATR so prone to mean reversion if looking to enter on a lower timeframe.
- NZD/USD and NZD/CAD are the weakest pairs although daily range is yet to meet its ATR. Outside of NZD pairs, volatility remains low, with an average range to ATR around 50%.
Equity Brief:
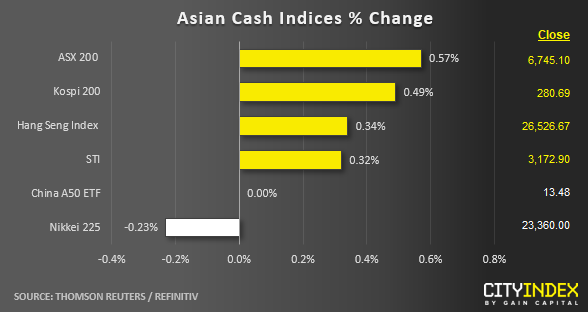
- Key Asian stock markets are again trading in a cautiously optimistic mode where modest gains between 0.25% to 0.50% have been recorded in Singapore, Hong Kong, South Korea and Australia markets while no change in China A50 and Japan’s Nikkei 225 has now traded into the red with a minor loss of -0.23%.
- Yesterday’s we had the usual dose of optimistic U.S-China trade related news headline quoted by media from “unnamed” sources after the initial slide in equities prices seen at the start of the European session. The media stated that U.S. and China officials have planned for a delay on the additional tariffs impose on China’s products that are set to kick in on 15 Dec as talks progress for the finalisation of the Phase One trade deal.
- On the other hand, U.S. White House Trade Adviser, Navarro said that he was not aware of any indication of the 15 Dec tariff delay.
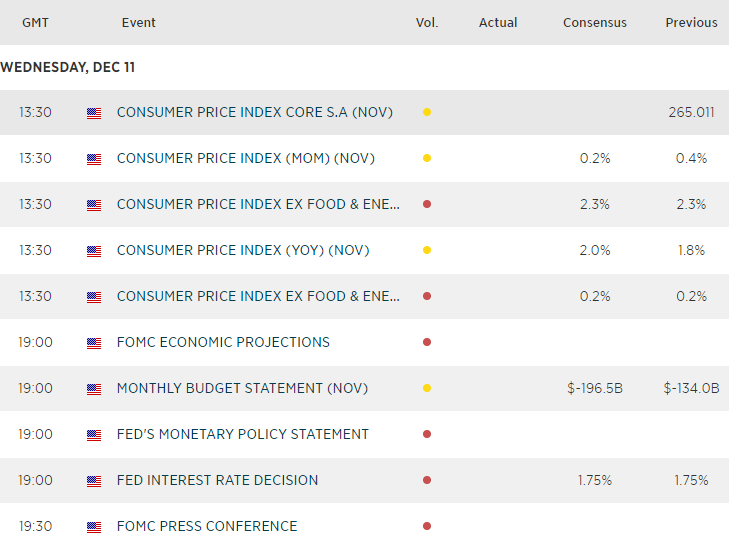
- For the rest of day, do expect more churning and sideways movement as we head into Fed FOCM monetary policy outcome out later at 1900 GMT. Also, do take note of Fed’s Chair Powell press conference at 1930 GMT where he is likely to be “probed” by the media on the state of the short-term funding repo market especially a research report published by Credit Suisse yesterday on the risk of a liquidity squeeze in the repo market and its potential negative ramifications as we head into the upcoming year-end turn.
- Japan 225: Yesterday’s slide has managed to hold at 23250 predefined minor range support (printed a low of 23263 in 10 Dec, European session). No change, still expect sideways movement between 23650 (medium-term range resistance in place since 07 No 2019) and 23250. Only a break below 23250 sees a deeper slide towards the medium-term range support area of 23150/23050 (also the minor ascending trendline in place since 21 Nov 2019 low & 61.8% retracement of the recent push up from 03 Dec low to 09 Dec 2019 high).
- Hong Kong 50: Staged the minor expected slide to retest yesterday, 10 Dec Asian session low of 26264 during the European session (printed a low of 26238). It has now bounced back towards its minor range resistance at 26600. Expect churning within 26238 and 26600. A break below 26238 sees a further slide towards 25920 swing low of 03 Dec 2019.
- Australia 200: Yesterday’s losses have met reversed via a minor V-shaped recovery after it printed an intraday low of 6671 in the European session. Hourly RSI oscillator remains above the 50-level. Expect sideways movement between 6780 (03 Dec minor swing high & 61.8% retracement of the previous slide from 29 Nov high to 03 Dec 2019 low) and 6670.
- Germany 30: Slide down towards 12900 (03 Dec 2019 swing low area) as expected a staged a bounce off from it thereafter. The bounce has stalled below a minor descending trendline from 02 Dec 2019 high now acting as a resistance at 13120. Expect a potential slide back to retest 12960/12900 within a medium-term range resistance in place since 19 Nov 2019.
- US SP 500: Slide/retracement target/support hit at 3120 as expected (printed an intraday low of 3115 in yesterday’s European session). Expect churning within 3147 (minor descending trendline from 02 Dec 2019) and 3115. A break below 3115 sees a further potential slide towards 3106 next (05 Dec 2019 minor swing low & Fibonacci retracement/expansion cluster).
Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
View our guide on how to interpret the FX Dashboard
- Earlier in the session, the NZ government announced further infrastructure spending alongside a boost in fiscal spending in 2020. However, SEEK job advertisements since September’s spike has been lacklustre, which brings doubt to the strength of the employment market as we head into 2020. That said, market reaction may be a little overdone considering the positive news flows seen from NZ of late.
- Markets remain in a holding pattern whilst Trump decides whether to adds tariffs to $160 billion of Chinese goods over the weekend. Whilst there have been mixed reports over a potential delay, advisors are to meet with Trump over the coming days to hopefully finalise the decision (or leave the markets risk to weekend gaps if no decision has been announced before Sunday’s deadline).
- House Democrats formerly announced impeachment charges against President Trump, a move which is likely to result in a Republican-led Senate trial early next year.
Price Action:
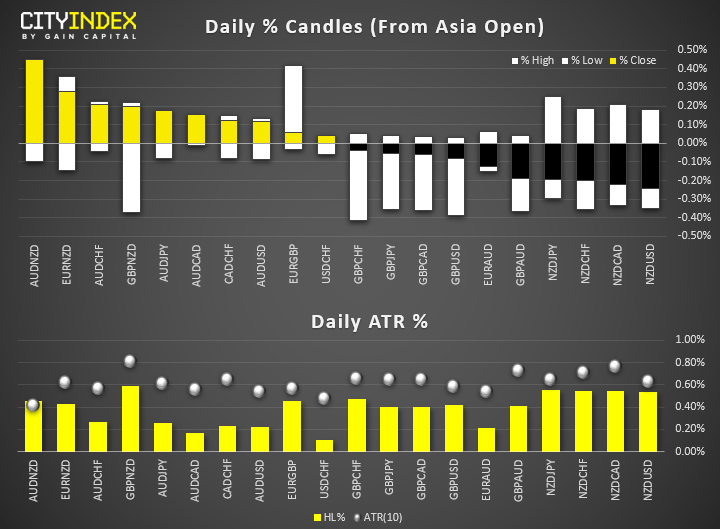
- NZD is the weakest major and the most volatile (as it quiet elsewhere ahead of today’s FOMC meeting and CPI data).
- AUD/NZD is the largest gainer and enjoying its largest daily gain in a month. Having failed to break below a bullish trendline and the 1.40 handle, it likely marks the beginning of a much-needed correction. However, it’s moved 108% of is typical ATR so prone to mean reversion if looking to enter on a lower timeframe.
- NZD/USD and NZD/CAD are the weakest pairs although daily range is yet to meet its ATR. Outside of NZD pairs, volatility remains low, with an average range to ATR around 50%.
Equity Brief:
- Key Asian stock markets are again trading in a cautiously optimistic mode where modest gains between 0.25% to 0.50% have been recorded in Singapore, Hong Kong, South Korea and Australia markets while no change in China A50 and Japan’s Nikkei 225 has now traded into the red with a minor loss of -0.23%.
- Yesterday’s we had the usual dose of optimistic U.S-China trade related news headline quoted by media from “unnamed” sources after the initial slide in equities prices seen at the start of the European session. The media stated that U.S. and China officials have planned for a delay on the additional tariffs impose on China’s products that are set to kick in on 15 Dec as talks progress for the finalisation of the Phase One trade deal.
- On the other hand, U.S. White House Trade Adviser, Navarro said that he was not aware of any indication of the 15 Dec tariff delay.
- For the rest of day, do expect more churning and sideways movement as we head into Fed FOCM monetary policy outcome out later at 1900 GMT. Also, do take note of Fed’s Chair Powell press conference at 1930 GMT where he is likely to be “probed” by the media on the state of the short-term funding repo market especially a research report published by Credit Suisse yesterday on the risk of a liquidity squeeze in the repo market and its potential negative ramifications as we head into the upcoming year-end turn.
- Japan 225: Yesterday’s slide has managed to hold at 23250 predefined minor range support (printed a low of 23263 in 10 Dec, European session). No change, still expect sideways movement between 23650 (medium-term range resistance in place since 07 No 2019) and 23250. Only a break below 23250 sees a deeper slide towards the medium-term range support area of 23150/23050 (also the minor ascending trendline in place since 21 Nov 2019 low & 61.8% retracement of the recent push up from 03 Dec low to 09 Dec 2019 high).
- Hong Kong 50: Staged the minor expected slide to retest yesterday, 10 Dec Asian session low of 26264 during the European session (printed a low of 26238). It has now bounced back towards its minor range resistance at 26600. Expect churning within 26238 and 26600. A break below 26238 sees a further slide towards 25920 swing low of 03 Dec 2019.
- Australia 200: Yesterday’s losses have met reversed via a minor V-shaped recovery after it printed an intraday low of 6671 in the European session. Hourly RSI oscillator remains above the 50-level. Expect sideways movement between 6780 (03 Dec minor swing high & 61.8% retracement of the previous slide from 29 Nov high to 03 Dec 2019 low) and 6670.
- Germany 30: Slide down towards 12900 (03 Dec 2019 swing low area) as expected a staged a bounce off from it thereafter. The bounce has stalled below a minor descending trendline from 02 Dec 2019 high now acting as a resistance at 13120. Expect a potential slide back to retest 12960/12900 within a medium-term range resistance in place since 19 Nov 2019.
- US SP 500: Slide/retracement target/support hit at 3120 as expected (printed an intraday low of 3115 in yesterday’s European session). Expect churning within 3147 (minor descending trendline from 02 Dec 2019) and 3115. A break below 3115 sees a further potential slide towards 3106 next (05 Dec 2019 minor swing low & Fibonacci retracement/expansion cluster).
Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.