



Market Brief Parliamentary Pandemonium Putrid US Manufacturing Data
See a summary of the top market themes and trends from today's US trading session!
Share this:


- A Parliamentary showdown over Brexit drove trade in the FX market today, with the risk of an early election rising as MPs fight to block a no-deal Brexit. See the key Brexit dates we’ll be watching in the weeks to come.
- FX: The aussie was the strongest major currency on the day after the RBA left interest rates unchanged. The loonie brought up the rear as oil prices slumped, taking USD/CAD to 1.3350, its highest level since mid-June (readers should note that the Bank of Canada meets later this week, though an outright cut looks unlikely at present).
- US data: ISM Manufacturing PMI printed weaker-than-expected at 49.1, the first sub-50 reading since early 2016 as US-China trade tensions took a toll.
- Commodities: Gold tacked on 1.5% to test its August highs; Oil (WTI) dropped nearly -2% on the day.
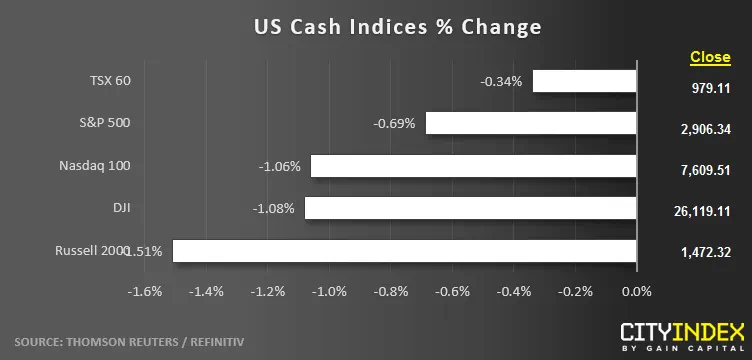
- US indices closed lower by roughly -1% on the first trading day of the month following a long holiday weekend in the US.
- Utilities (XLU) were the strongest major sector on the day, gaining about 1.5%. Industrial stocks (XLI) went from first on Friday to worst today, dropping nearly -1.5%.
- Stocks on the move:
- Chip stocks, which are seen as particularly sensitive to trade tensions, dropped across the board. Among widely-followed stocks, Intel (INTC, -1%), Advanced Micro Devices (AMD, -2%), and Micron (MU, -0%) all dipped.
- Apple (AAPL) shed over -1% as new tariffs hit some products, including the Apple Watch.
- Boeing (BA) lost -3% after a weekend WSJ report suggested the company had encountered further issues with its 737 Max jet.

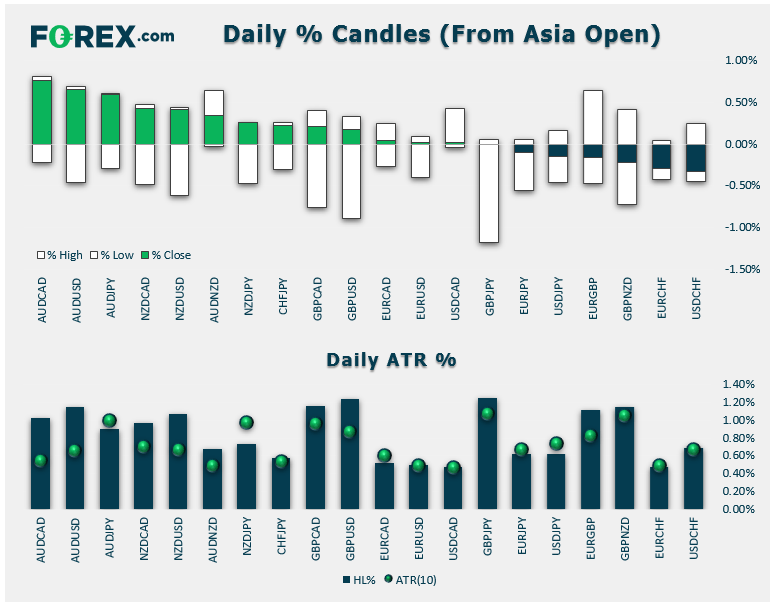
- A Parliamentary showdown over Brexit drove trade in the FX market today, with the risk of an early election rising as MPs fight to block a no-deal Brexit. See the key Brexit dates we’ll be watching in the weeks to come.
- FX: The aussie was the strongest major currency on the day after the RBA left interest rates unchanged. The loonie brought up the rear as oil prices slumped, taking USD/CAD to 1.3350, its highest level since mid-June (readers should note that the Bank of Canada meets later this week, though an outright cut looks unlikely at present).
- US data: ISM Manufacturing PMI printed weaker-than-expected at 49.1, the first sub-50 reading since early 2016 as US-China trade tensions took a toll.
- Commodities: Gold tacked on 1.5% to test its August highs; Oil (WTI) dropped nearly -2% on the day.
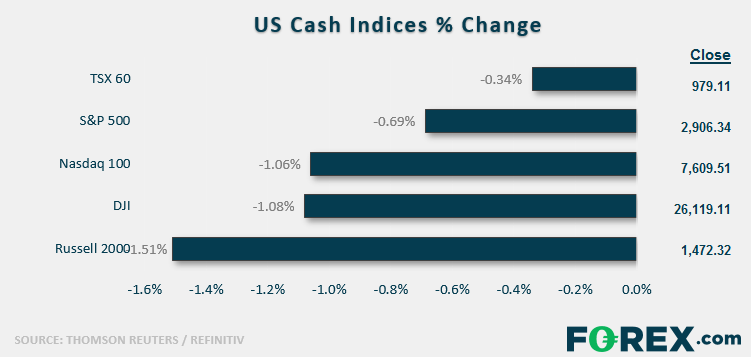
- US indices closed lower by roughly -1% on the first trading day of the month following a long holiday weekend in the US.
- Utilities (XLU) were the strongest major sector on the day, gaining about 1.5%. Industrial stocks (XLI) went from first on Friday to worst today, dropping nearly -1.5%.
- Stocks on the move:
- Chip stocks, which are seen as particularly sensitive to trade tensions, dropped across the board. Among widely-followed stocks, Intel (INTC, -1%), Advanced Micro Devices (AMD, -2%), and Micron (MU, -0%) all dipped.
- Apple (AAPL) shed over -1% as new tariffs hit some products, including the Apple Watch.
- Boeing (BA) lost -3% after a weekend WSJ report suggested the company had encountered further issues with its 737 Max jet.

Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.