






Market Brief Risk On Extends As US Considers Tariff Rollback
A summary of news and snapshot of moves from today’s Asia session.
Share this:

FX Brief:
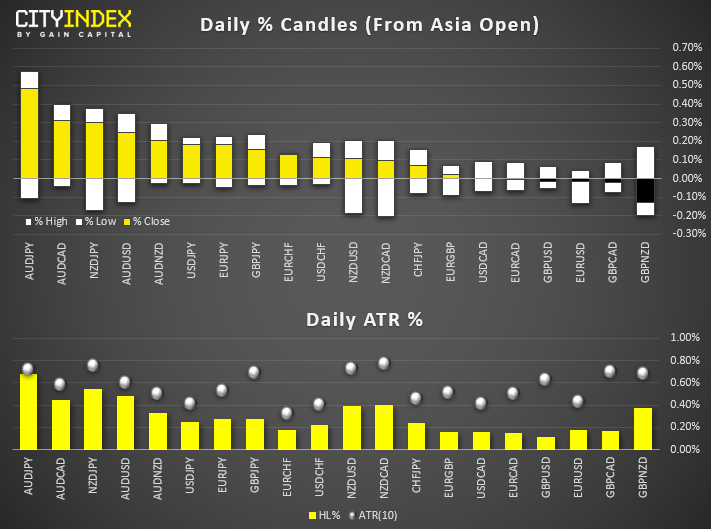
- AUD is today’s strongest major after RBA held rates. AUD/JPY is the biggest mover of the session and its daily range has spanned 95% of its 10-day ATR – given it remains beneath key resistance, we may need another catalyst for risk-on to break higher.
Reports that US was considering remove tariffs on $120 billion of Chinese goods was also supportive for AUD and NZD pairs. - Trade optimism saw the yuan appreciate further, taking USD/CNH to a 60-day low.
- DXY nudged its way to a 4-day high after yesterday’s rebound from key support.
- GBP/USD is stuck at yesterday’s, with potential for further downside given Friday’s bearish pinbar and Monday’s bearish engulfing candle.
Equity Brief:
- Risk on mode has continued to prevail in key Asia stock markets that has recorded modest gains between 0.15% to 0.70% except for Japan’s Nikkei 225 that has surged by 2%, more of a “catch-up play” due to a holiday closure yesterday.
- Continued bout of U.S-China trade deal optimism news flow seems to be the catalyst as a media report has cited that the White House is considering rolling back the 01 Sep tariffs imposed on $112 billon of Chinese imports, one of the sticking points that China has requested before any trade deal is being finalised.
- Also, China central bank PBOC has continued to provide liquidity by cutting its medium-term lending facility (MLF) by 5 bps to 3.25%, the first cut since early 2016. Perhaps such liquidity injection has managed to offset the expected negative reaction from China’s weak services sector activities. The Caixin China Services PMI has slipped unexpectedly to 51.1 in Oct (versus consensus forecast of 52.8) from 51.3 recorded in Sep; the weakest pace of growth in the services sector since Feb 2019.
- Technology sector has led the gains in the Hong Kong stock market for today where AAC Technologies, a supplier of Apple has surged by 3.5% to hit a 6-month high of HKD 53.30; the stock has rallied by 60% from its Aug 2019 low of 32.85.
- The performance of Australia’s ASX 200 was tepid due to a dent in overall sentiment by Westpac Banking Corp, one of the “Big 4” banks that plummeted as much as -5.1% to A$26.46 after a trading halt was lifted from yesterday, the biggest drop since Nov 2018. Westpac had completed a discounted A$2 billion equity placement where the issue price was at A$25.32 per share which was a significant 9% discount to its closing price on last Fri, 01 Nov.
- Oversea-Chinese Banking Corp (OCBC), a major component stock in the Singapore’s Strait Times Index (STI) has shed by -0.36% so far after it has reported a fall of 6% on its Q3 profit due to a one-off charge for Indonesian unit.
Up Next:
- UK manufacturing PMI is expected to contract at the slower rate of 49.7, versus 49.5 prior.
- ISM Non-manufacturing could shed further light on whether the US is headed for recession. The manufacturing counterpart has contracted for three consecutive months, yet services remains expansionary. Given we saw manufacturing’s contraction slow this month, it could leave potential for a positive surprise. USD pairs and US indices are markets to track around this release.

Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
View our guide on how to interpret the FX Dashboard
FX Brief:
- AUD is today’s strongest major after RBA held rates. AUD/JPY is the biggest mover of the session and its daily range has spanned 95% of its 10-day ATR – given it remains beneath key resistance, we may need another catalyst for risk-on to break higher.
Reports that US was considering remove tariffs on $120 billion of Chinese goods was also supportive for AUD and NZD pairs. - Trade optimism saw the yuan appreciate further, taking USD/CNH to a 60-day low.
- DXY nudged its way to a 4-day high after yesterday’s rebound from key support.
- GBP/USD is stuck at yesterday’s, with potential for further downside given Friday’s bearish pinbar and Monday’s bearish engulfing candle.
Equity Brief:
- Risk on mode has continued to prevail in key Asia stock markets that has recorded modest gains between 0.15% to 0.70% except for Japan’s Nikkei 225 that has surged by 2%, more of a “catch-up play” due to a holiday closure yesterday.
- Continued bout of U.S-China trade deal optimism news flow seems to be the catalyst as a media report has cited that the White House is considering rolling back the 01 Sep tariffs imposed on $112 billon of Chinese imports, one of the sticking points that China has requested before any trade deal is being finalised.
- Also, China central bank PBOC has continued to provide liquidity by cutting its medium-term lending facility (MLF) by 5 bps to 3.25%, the first cut since early 2016. Perhaps such liquidity injection has managed to offset the expected negative reaction from China’s weak services sector activities. The Caixin China Services PMI has slipped unexpectedly to 51.1 in Oct (versus consensus forecast of 52.8) from 51.3 recorded in Sep; the weakest pace of growth in the services sector since Feb 2019.
- Technology sector has led the gains in the Hong Kong stock market for today where AAC Technologies, a supplier of Apple has surged by 3.5% to hit a 6-month high of HKD 53.30; the stock has rallied by 60% from its Aug 2019 low of 32.85.
- The performance of Australia’s ASX 200 was tepid due to a dent in overall sentiment by Westpac Banking Corp, one of the “Big 4” banks that plummeted as much as -5.1% to A$26.46 after a trading halt was lifted from yesterday, the biggest drop since Nov 2018. Westpac had completed a discounted A$2 billion equity placement where the issue price was at A$25.32 per share which was a significant 9% discount to its closing price on last Fri, 01 Nov.
- Oversea-Chinese Banking Corp (OCBC), a major component stock in the Singapore’s Strait Times Index (STI) has shed by -0.36% so far after it has reported a fall of 6% on its Q3 profit due to a one-off charge for Indonesian unit.
Up Next:
- UK manufacturing PMI is expected to contract at the slower rate of 49.7, versus 49.5 prior.
- ISM Non-manufacturing could shed further light on whether the US is headed for recession. The manufacturing counterpart has contracted for three consecutive months, yet services remains expansionary. Given we saw manufacturing’s contraction slow this month, it could leave potential for a positive surprise. USD pairs and US indices are markets to track around this release.
Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.