



Market Brief Risk On Upset By US Chip Maker Woes Brexit Delay
A summary of news and snapshot of moves from today’s Asia session.
Share this:

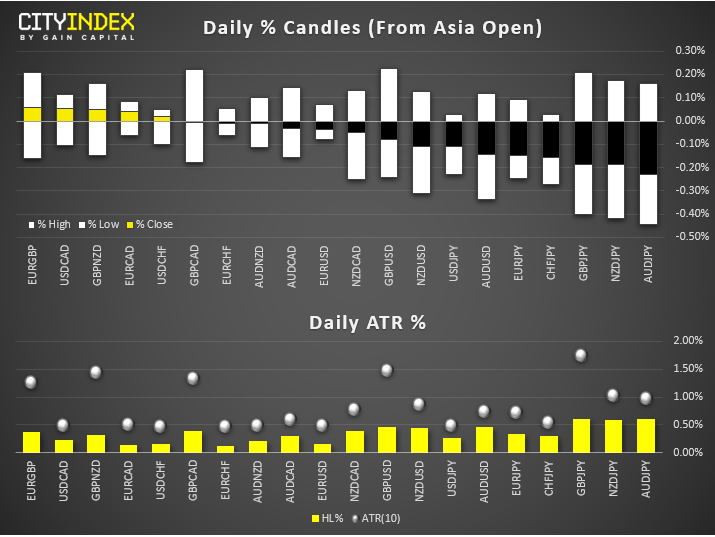
View our guide on how to interpret the FX Dashboard
FX Brief:
- With British parliament still unsure of how or when Brexit could go through, it was a mild risk-off session in Asia overall yet volatility remained contained. All pairs from the FX dashboard remaining below their daily ATRs. JPY is the strongest major whilst AUD and GBP are the weakest.
- RBNZ’s Hawkesby “very happy” with how cuts have fed through to the economy, adding that inflation could be fuelled by higher house prices (so long as this leads to consumption).
- DXY and USD/CHF nudged their way to a 3 and 4-day high respectively as the greenback extends yesterday’s correction.
- AUD/USD and NZD/USD also retreated earlier in the session, with AUD finding support just above the June ’19 low. EUR/USD also edged lower yet key support resides 1.110.
- GBP/UD also tested a 4-day low but we’re waiting for Brexit headlines from the UK or US session to really get this one moving.
Equity Brief:
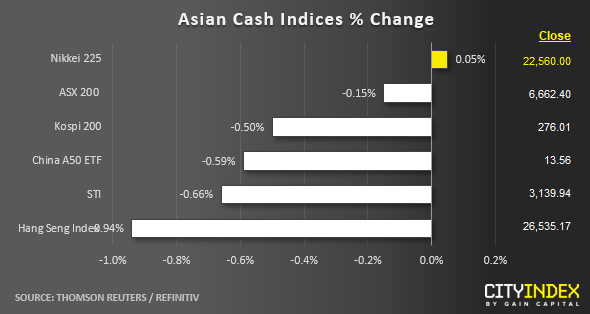
- A sea of red for Asian stock markets today after soft earnings numbers from a bellwether U.S. semiconductor firm, Texas Instruments also the 3rd largest component stock in the PHLX Semiconductor Sector Index.
- After the close of yesterday’s U.S. session, the share price of Texas Instruments has tumbled by close to -10% to print an intraday low of 114.40 in after-hour trading after it reported Q3 revenue that came in below expectations (US$3.77 billion versus US$3.8 billion consensus) and offer a lacklustre Q4 earnings guidance. It has closed yesterday at $128.57.
- The worst performer so far today is the Hong Kong’s Hang Seng Index which has declined by -0.94% where major technology related stocks took the brunt today. ACC Technologies and Tencent Holdings have plummeted by -3.70% and -1.89% respectively. In addition, there is media report that stated that the Chinese government is drafting a plan to replace the current Hong Kong’s Chief Executive Lam with an “interim” chief executive and Lam’s successor is likely to be installed in March. Perhaps such action will be not be able to alleviate the 5-month long of street demonstrations as the chief executive is still picked by the central government rather than local Hong Kong votes.
- Japan’s Nikkei 225 has managed to escape the carnage where losses in technological related stocks have been offset by gains seen in health care and industrial related stocks, Sumitomo Heavy Industrials has recorded a gain of 3.09%.
- Nikkei 225 heavy weightage stock, Softbank Group has tumbled by -2.6%; dragged down by its investment related woes in embattled start-up WeWork. Softbank has agreed to cough up a US$9.5 billion rescue package in exchange for a 80% stake in WeWork.
- The S&P 500 E-Mini futures has extended a modest decline of -0.19% in today’s Asian session to print a current intraday low of 2982 after it reintegrated back below the 3000 psychological level at the close of yesterday’s U.S. session.
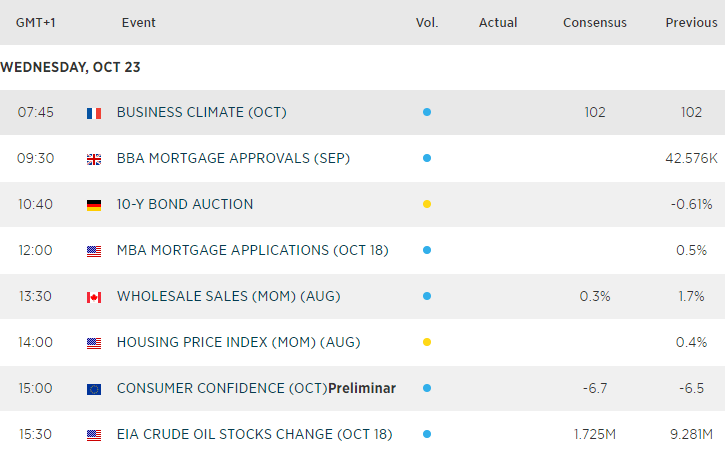
Economic Calendar
Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions

Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.