





Market Brief Stocks Ignore Weak China Trade Data
A summary of news and snapshot of moves from today’s Asia session.
Share this:

FX Brief:
- China’s exports to the US declined -10.7% from a year earlier (USD terms), whilst imports from the US fell -26.4%. The broader read saw exports fall -3.2% YoY and imports also decline -8.5% YoY. A trade spokesman said trade will remain complicated and severe, despite much hype about phase-1 of the trade deal circling western media. The Yuan strengthened to see USD/CHF fall to a 1-month low.
- Singapore’s central bank (MAS) eased policy for the first time in three years, by slightly lowering the slope of the SGD currency band whilst maintaining the width and centre of the band. Inflation is expected to remain subdued in the year ahead. The Singapore dollar strengthened and saw USD/SGD fall to a 3-month low.
- FX majors and crosses were mostly rangebound through Asia, with AUD/NZD being the only cross to achieve its typical daily range. GBP/USD is treading water around 1.2600, after posting a 4% bullish range over Thursday and Friday. EUR/USD is also holding steady just off its highs around 1.1030.
Equity Brief:
- Asian stock markets have continued to post solid gains on the backdrop of easing trade tension between U.S and China after a verbal agreement struck last Fri by trade officials from both sides where U.S. President Trump coined as Phase 1 of major trade deal despite no concrete details are put in writing. For now, the U.S. administration will put on hold the 25% to 30% increase of tariffs on US$250 billion worth Chinese imports in exchange for bulk purchases of U.S. agricultural products by China.
- U.S. President Trump has added the Phase 1 trade deal agreement may be signed in Chile where Trump and China President Xi attend the APEC Summit on 16-17 Nov 2019. In contrast, China media outlets have painted a less optimistic tone on last Fri’s trade meeting and even did not mention any trade deal was being agreed.
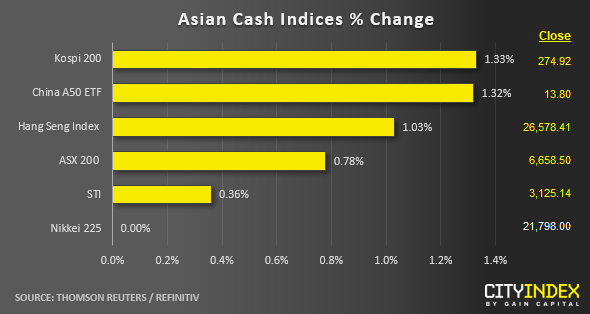
- Today’s Asian session top gainers are China’s A50 and South Korean’s Kospi 200 where both rallied by 1.30%. Japan stock market is closed for a national holiday today and will resume trading tomorrow.
- Singapore central bank, MAS has eased monetary policy in its biannual monetary policy review as expected for the first time in three years by lowering slightly the slope of an undisclosed Singapore dollar’s policy band after two rounds of tightening in 2018. The Singapore’s STI has rallied only modestly by 0.36% on the backdrop weaker than expected China trade data for Sep; exports fell -3.2% y/y versus consensus of -3.0% y/y/ and imports declined significantly to -8.5% y/y versus consensus of -5.2% y/y.
- The S&P 500 E-Mini futures has continued to hold onto last Fri’s gains as it inched up by 0.17% to print a current intraday high of 2982 in today’s Asia session.
Up Next
- Eurozone Industrial Production for Aug where expectation is set at -2.5% y/y and 0.3% m/m over -2.0% y/y and -0.4% m/m recorded in Jul.

Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
FX Brief:
- China’s exports to the US declined -10.7% from a year earlier (USD terms), whilst imports from the US fell -26.4%. The broader read saw exports fall -3.2% YoY and imports also decline -8.5% YoY. A trade spokesman said trade will remain complicated and severe, despite much hype about phase-1 of the trade deal circling western media. The Yuan strengthened to see USD/CHF fall to a 1-month low.
- Singapore’s central bank (MAS) eased policy for the first time in three years, by slightly lowering the slope of the SGD currency band whilst maintaining the width and centre of the band. Inflation is expected to remain subdued in the year ahead. The Singapore dollar strengthened and saw USD/SGD fall to a 3-month low.
- FX majors and crosses were mostly rangebound through Asia, with AUD/NZD being the only cross to achieve its typical daily range. GBP/USD is treading water around 1.2600, after posting a 4% bullish range over Thursday and Friday. EUR/USD is also holding steady just off its highs around 1.1030.
Equity Brief:
- Asian stock markets have continued to post solid gains on the backdrop of easing trade tension between U.S and China after a verbal agreement struck last Fri by trade officials from both sides where U.S. President Trump coined as Phase 1 of major trade deal despite no concrete details are put in writing. For now, the U.S. administration will put on hold the 25% to 30% increase of tariffs on US$250 billion worth Chinese imports in exchange for bulk purchases of U.S. agricultural products by China.
- U.S. President Trump has added the Phase 1 trade deal agreement may be signed in Chile where Trump and China President Xi attend the APEC Summit on 16-17 Nov 2019. In contrast, China media outlets have painted a less optimistic tone on last Fri’s trade meeting and even did not mention any trade deal was being agreed.
- Today’s Asian session top gainers are China’s A50 and South Korean’s Kospi 200 where both rallied by 1.30%. Japan stock market is closed for a national holiday today and will resume trading tomorrow.
- Singapore central bank, MAS has eased monetary policy in its biannual monetary policy review as expected for the first time in three years by lowering slightly the slope of an undisclosed Singapore dollar’s policy band after two rounds of tightening in 2018. The Singapore’s STI has rallied only modestly by 0.36% on the backdrop weaker than expected China trade data for Sep; exports fell -3.2% y/y versus consensus of -3.0% y/y/ and imports declined significantly to -8.5% y/y versus consensus of -5.2% y/y.
- The S&P 500 E-Mini futures has continued to hold onto last Fri’s gains as it inched up by 0.17% to print a current intraday high of 2982 in today’s Asia session.
Up Next
- Eurozone Industrial Production for Aug where expectation is set at -2.5% y/y and 0.3% m/m over -2.0% y/y and -0.4% m/m recorded in Jul.
Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.