





Market brief Swissy breaks through parity
A summary of news and snapshot of moves ahead of the US session.
Share this:

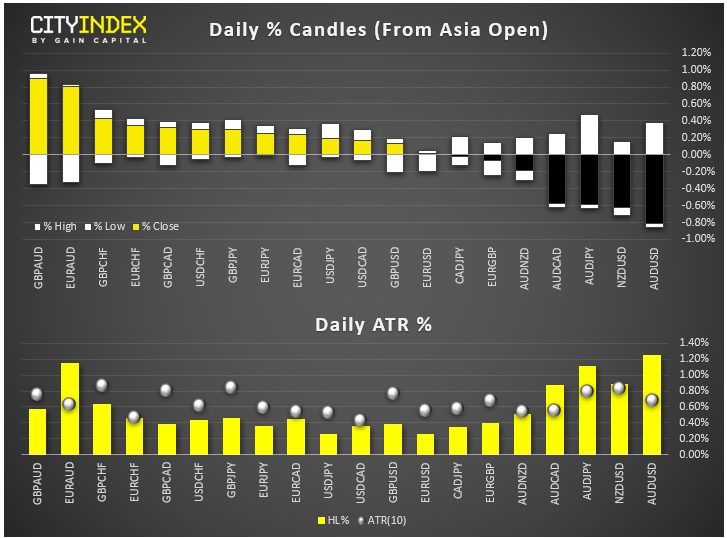
- At midday in London the GBP and EUR were among the strongest while the AUD, NZD and CHF were the weakest
- The economic calendar is full of data today and so far, the biggest event was the RBA’s rate cut, a decision which was mostly priced in - although the central bank still surprised the markets by providing a more dovish assessment of the economy and indicated rates could be loosened further if needed.
- The EUR rose even though the Eurozone headline CPI fell further in September to 0.9% y/y, when an unchanged reading of 1.0% was expected. Core CPI rose however to 1.0% from 0.9%, in line with expectations. Meanwhile, the latest Manufacturing PMIs from the UK (48.3 vs. 47.0 expected) and Japan (Tankan) both beat, while those from Italy (47.8 vs. 48.2), Spain (47.7 vs. 48.2) and Switzerland (44.6 vs. 46.5) all disappointed. Still, Eurozone final PMI was revised a touch higher (to 45.7) thanks to a small positive revision for Germany. Nevertheless, all the above-mentioned PMIs remained below the boom/bust level of 50.0, pointing to falling economic activity and underscoring the need for further monetary stimulus by major central banks. Among the notable movers in FX, the USD/CHF broke above parity as Switzerland’s retail sales printed -1.4% y/y vs. +1.6% expected and the manufacturing PMI also disappointed as per above.
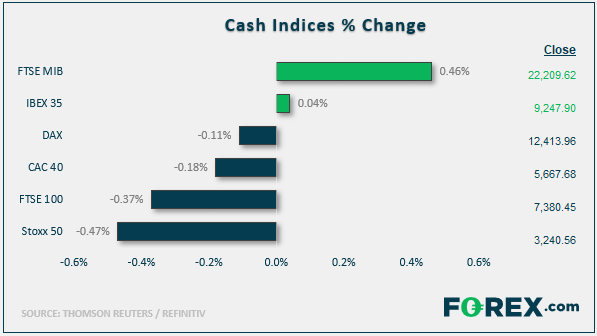
- The Swiss franc and other safe haven assets such as gold and Japanese yen have been weighed down in recent days by ongoing risk-on trade with stocks remaining overall supported (even if the EU indices started today’s session on the back foot) amid US-China trade optimism and central bank support.
- Is today’s weak start for European stocks due to fund managers rebalancing their portfolios? After all, Q3 ended with a bang for global indices. The S&P 500 recovered from a bad August to record its biggest year-to-date gain in more than 20 years. In Europe, too, the indices recovered to end Q3 noticeably higher. With central banks remaining in expansionary policy mode, and optimism rising that a US-China deal might be imminent, the stock market bulls are happy to keep buying every dip – for now.

- At midday in London the GBP and EUR were among the strongest while the AUD, NZD and CHF were the weakest
- The economic calendar is full of data today and so far, the biggest event was the RBA’s rate cut, a decision which was mostly priced in - although the central bank still surprised the markets by providing a more dovish assessment of the economy and indicated rates could be loosened further if needed.
- The EUR rose even though the Eurozone headline CPI fell further in September to 0.9% y/y, when an unchanged reading of 1.0% was expected. Core CPI rose however to 1.0% from 0.9%, in line with expectations. Meanwhile, the latest Manufacturing PMIs from the UK (48.3 vs. 47.0 expected) and Japan (Tankan) both beat, while those from Italy (47.8 vs. 48.2), Spain (47.7 vs. 48.2) and Switzerland (44.6 vs. 46.5) all disappointed. Still, Eurozone final PMI was revised a touch higher (to 45.7) thanks to a small positive revision for Germany. Nevertheless, all the above-mentioned PMIs remained below the boom/bust level of 50.0, pointing to falling economic activity and underscoring the need for further monetary stimulus by major central banks. Among the notable movers in FX, the USD/CHF broke above parity as Switzerland’s retail sales printed -1.4% y/y vs. +1.6% expected and the manufacturing PMI also disappointed as per above.
- The Swiss franc and other safe haven assets such as gold and Japanese yen have been weighed down in recent days by ongoing risk-on trade with stocks remaining overall supported (even if the EU indices started today’s session on the back foot) amid US-China trade optimism and central bank support.
- Is today’s weak start for European stocks due to fund managers rebalancing their portfolios? After all, Q3 ended with a bang for global indices. The S&P 500 recovered from a bad August to record its biggest year-to-date gain in more than 20 years. In Europe, too, the indices recovered to end Q3 noticeably higher. With central banks remaining in expansionary policy mode, and optimism rising that a US-China deal might be imminent, the stock market bulls are happy to keep buying every dip – for now.
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.