



Market Brief Trade Deal Optimism Eases Off
A summary of news and snapshot of moves from today’s Asia session.
Share this:

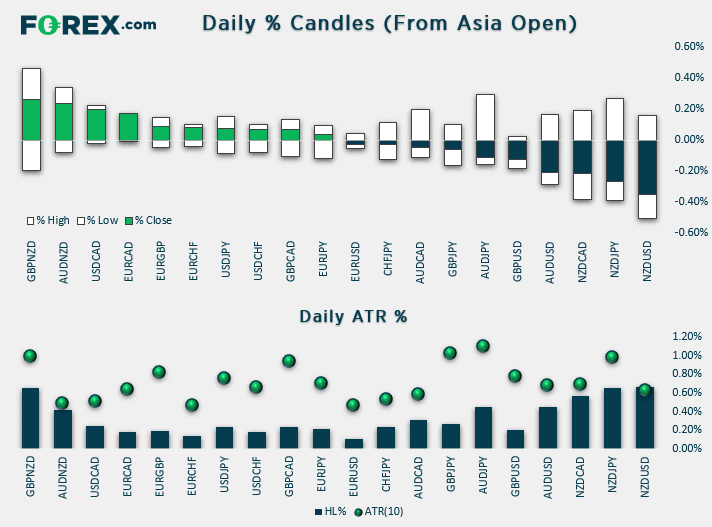
- Ranges were painfully small with a lack of news throughout most of the Asia session, although NZD and AUD went on to be the weakest majors and provided the most volatility later on. USD is the strongest major.
- The yield curve inversion slightly soured sentiment to help with JPY inflows, and weighing on most Asian FX pairs.
- Australian construction work contracted by -3.8%, it’s worst year over year quarter since December 2017. And if PMI data is anything to go by, could set be weaken further with the sector contracting at -39.1, it’s month since 2013.
- RBNZ’s Greame Orr echoed concerns of his peers that monetary policy has its limits and needs to be partnered with broader, fiscal and structural economic policy.
- The PBOC are reported to be releasing their own crypto currency as early as November, according to Forbes.
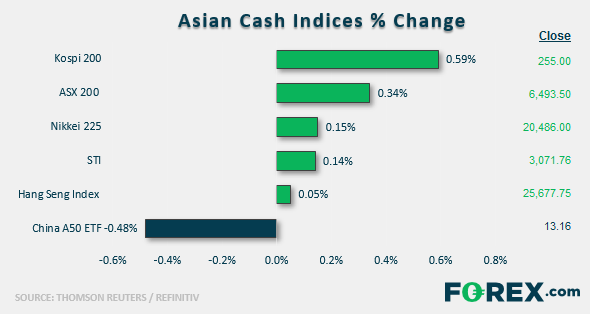
- Ahead of the European session open, China and Hong Kong stock markets have underperformed as at today’s Asian mid-session where China policy makers and media cast doubts on the credibility of the U.S. administration on getting a trade deal done ahead of the 2020 U.S. election after U.S. President Trump’s “flip flop” antics.
- The China A50 has dropped by -0.48% while the Hang Seng Index (HSI) is almost unchanged. Tencent Holdings, the biggest weightage component stock in the HSI and major China property developer, Country Garden have underperformed; down by -1.29% and -2.38% respectively.
- Negative news flow is the main catalyst that drives Tencent’s share price down today where it has been reported that China’s antitrust regulator is investigating Tencent’s music streaming subsidiary over several exclusive licensing deals with major records labels such as Universal and Sony. These agreements have forced rival music streaming providers; Alibaba and Baidu to sublicense content from Tencent at higher prices.
- The Kospi 200 and ASX 200 have recorded modest gains where the ASX 200 has inched higher by 0.35% supported by the technology and materials stocks.
- The S&P E-mini futures has started to consolidate in today’s Asian session, inched up by 0.28% so far after an intraday decline of -1.35% in yesterday’s 27 Aug U.S. session from its high of 2899.
Up Next
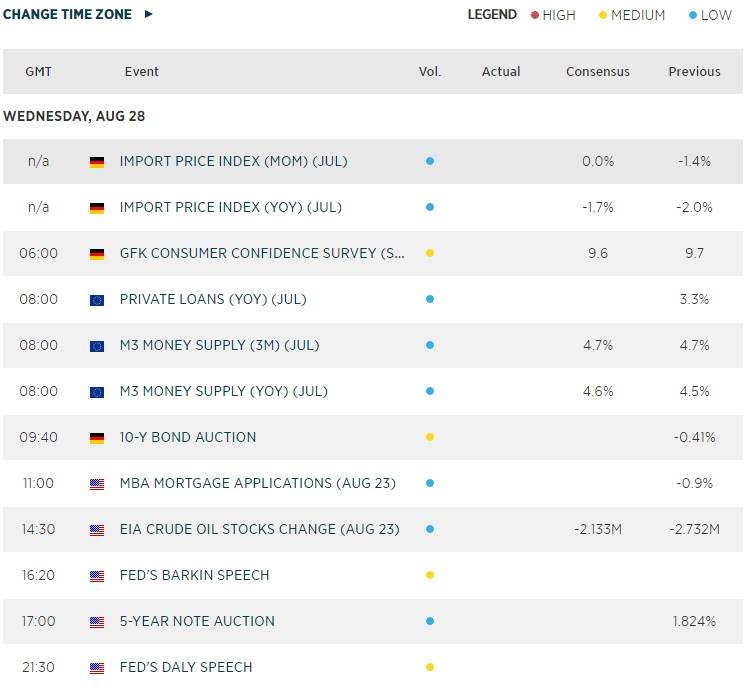
- Germany Gfk Consumer Confidence survey where consensus is pegged at 9.6, slightly down from the previous reading of 9.7
Macroeconomic Calendar
*Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
- Ranges were painfully small with a lack of news throughout most of the Asia session, although NZD and AUD went on to be the weakest majors and provided the most volatility later on. USD is the strongest major.
- The yield curve inversion slightly soured sentiment to help with JPY inflows, and weighing on most Asian FX pairs.
- Australian construction work contracted by -3.8%, it’s worst year over year quarter since December 2017. And if PMI data is anything to go by, could set be weaken further with the sector contracting at -39.1, it’s month since 2013.
- RBNZ’s Greame Orr echoed concerns of his peers that monetary policy has its limits and needs to be partnered with broader, fiscal and structural economic policy.
- The PBOC are reported to be releasing their own crypto currency as early as November, according to Forbes.

- Ahead of the European session open, China and Hong Kong stock markets have underperformed as at today’s Asian mid-session where China policy makers and media cast doubts on the credibility of the U.S. administration on getting a trade deal done ahead of the 2020 U.S. election after U.S. President Trump’s “flip flop” antics.
- The China A50 has dropped by -0.48% while the Hang Seng Index (HSI) is almost unchanged. Tencent Holdings, the biggest weightage component stock in the HSI and major China property developer, Country Garden have underperformed; down by -1.29% and -2.38% respectively.
- Negative news flow is the main catalyst that drives Tencent’s share price down today where it has been reported that China’s antitrust regulator is investigating Tencent’s music streaming subsidiary over several exclusive licensing deals with major records labels such as Universal and Sony. These agreements have forced rival music streaming providers; Alibaba and Baidu to sublicense content from Tencent at higher prices.
- The Kospi 200 and ASX 200 have recorded modest gains where the ASX 200 has inched higher by 0.35% supported by the technology and materials stocks.
- The S&P E-mini futures has started to consolidate in today’s Asian session, inched up by 0.28% so far after an intraday decline of -1.35% in yesterday’s 27 Aug U.S. session from its high of 2899.
Up Next
- Germany Gfk Consumer Confidence survey where consensus is pegged at 9.6, slightly down from the previous reading of 9.7
- No first-tier data to mull over for the European or US session, which again keeps any updates and / or setbacks surrounding the trade war as a possible market driver. Basically, keep an eye on Trump’s tweets.
*Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.