



Market Brief Trade Deal Optimism Lift Stocks
A summary of news and snapshot of moves from today’s Asia session.
Share this:

View our guide on how to interpret the FX Dashboard
FX Brief:
- Volumes were lighter due to the public holiday in Japan today.
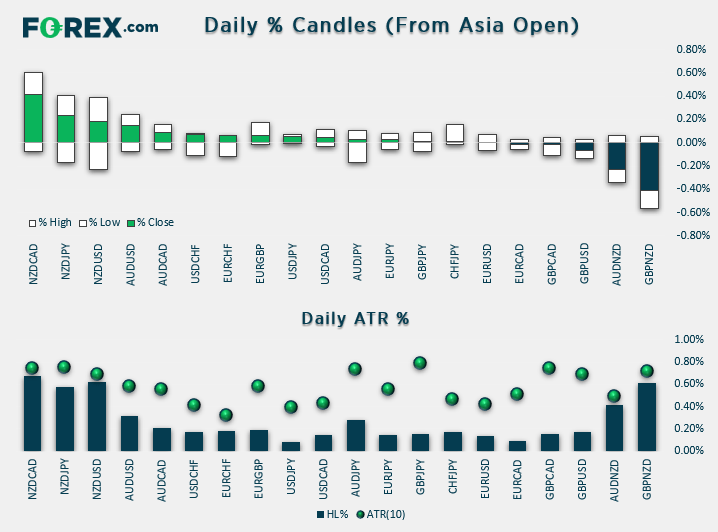
- NZD is the strongest major on the announcement that New Zealand has concluded its negotiations to upgrade their free trade deal with China. NZDCAD is today’s biggest gainer, and its daily range has hit 91% of its 10-day ATR. NZD/USD touched a fresh 3-month high.
- Trade optimism has seen the Yuan strengthen and send USD/CNH to it lowest level in 3-months.
- Australian retail sales declines -0.1% in Q3, showing further signs that tax brakes and record low interest rates are failing to prop up the economy. ANZ job adverts also declined by -1%. Take note that AUD/USD has paused beneath a long-term bearish trendline ahead of tomorrow’s RBA meeting. Whilst there’s no expectation of a cut, a dovish statement could topple the Aussie.
- EUR/USD is trading in a tight range just off last week’s highs ahead of European PMI data and a speech from ECB’s Christine Lagarde. USD/JPY is trapped between the 20 and 50-day eMA, near Friday’s high.
Equity Brief:
- Another bout of U.S-China trade deal optimism news flow coupled with a strong U.S. job/non-farm payroll data for Oct reported on last Fri, 01 Nov have continued to lift Asian stock markets at the start of a new trading week.
- U.S. Commerce Secretary Wilbur Ross expressed optimism over at a media interview over the weekend that U.S. would reach an agreement on the “Phase 1 of the trade deal” with China by this month and mentioned licenses would be issued very shortly for U.S. companies to sell components to “blacklisted” Huawei Technologies Co.
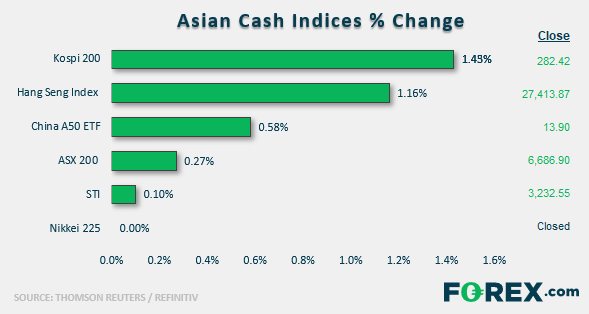
- The best performers today are South Korea’s Kospi 200 and Hong Kong’s Hang Seng Index as both have rallied by around 1.30%. Japan’s Nikkei 225 is closed today for a public holiday. The Kospi 200 has hit a 4-moth high of 282.49 led by the financials and industrials sectors that have gained by 2.31% and 1.79% respectively.
- Hong Kong’s stock market has shrugged off a series of violent street protests over the weekend that caused two people in critical conditions. More demonstrations are planned for this week that includes Guy Fawkes Day on 05 Nov by putting on banned face masks in the streets of Hong Kong.
- Both Singapore’s Straits Times Index (STI) and Australia’s ASX 200 has only gained modestly by 0.13% and 0.20% respectively. The ASX 200 has been dragged down by financial shares again where the big 4 banks; CBA, NAB and ANZ have dropped by -1.72%, -3.03% and -0.65% respectively. Westpac shares are halted for trading after it has announced a A$2.5 billion capital raising in fresh equity to bolster its balance sheet. In addition, Westpac also reported a 15% decline in full-year cash earnings and cut its dividend pay-out for the first time in a decade.
- The S&P 500 E-mini futures has continued to inch higher by 0.22% in today’s Asian session to print another fresh all-time high of 3071 with a current intraday low of 3064.
Up Next:
- The Euro will be in focus as new ECB head Christine Lagarde delivers her first official speech.
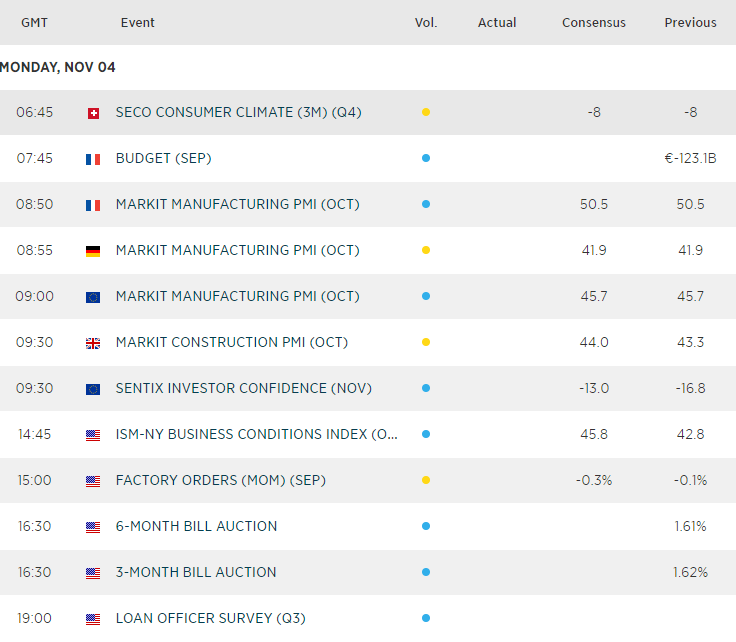
- German PMI data is expected to remain firmly within contraction (below 50) at 41.9. The broader EZ read is also expected to remain within contraction at 45.7, with France bucking the trend to remain slightly expansive at 50.5. So Euro pairs have plenty to keep an eye on later this session.
- UK construction PMI is expected to weaken further to 44 versus 43.3 prior.
Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
View our guide on how to interpret the FX Dashboard
FX Brief:
- Volumes were lighter due to the public holiday in Japan today.
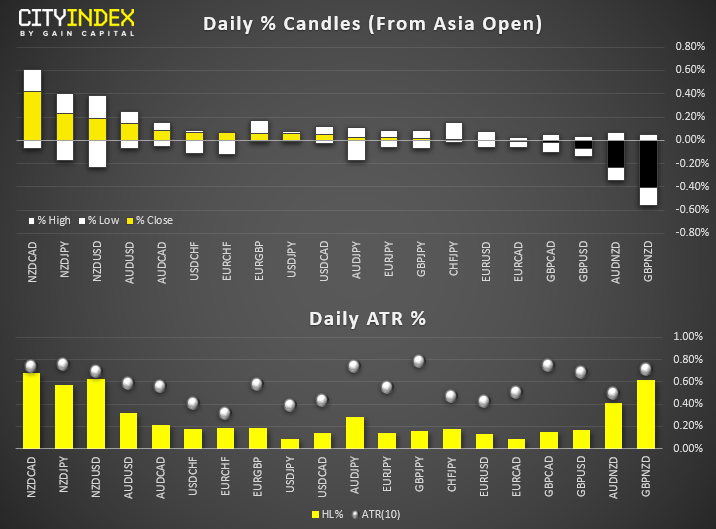
- NZD is the strongest major on the announcement that New Zealand has concluded its negotiations to upgrade their free trade deal with China. NZDCAD is today’s biggest gainer, and its daily range has hit 91% of its 10-day ATR. NZD/USD touched a fresh 3-month high.
- Trade optimism has seen the Yuan strengthen and send USD/CNH to it lowest level in 3-months.
- Australian retail sales declines -0.1% in Q3, showing further signs that tax brakes and record low interest rates are failing to prop up the economy. ANZ job adverts also declined by -1%. Take note that AUD/USD has paused beneath a long-term bearish trendline ahead of tomorrow’s RBA meeting. Whilst there’s no expectation of a cut, a dovish statement could topple the Aussie.
- EUR/USD is trading in a tight range just off last week’s highs ahead of European PMI data and a speech from ECB’s Christine Lagarde. USD/JPY is trapped between the 20 and 50-day eMA, near Friday’s high.
Equity Brief:
- Another bout of U.S-China trade deal optimism news flow coupled with a strong U.S. job/non-farm payroll data for Oct reported on last Fri, 01 Nov have continued to lift Asian stock markets at the start of a new trading week.
- U.S. Commerce Secretary Wilbur Ross expressed optimism over at a media interview over the weekend that U.S. would reach an agreement on the “Phase 1 of the trade deal” with China by this month and mentioned licenses would be issued very shortly for U.S. companies to sell components to “blacklisted” Huawei Technologies Co.
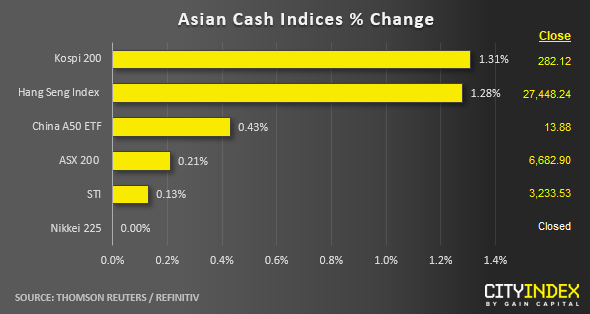
- The best performers today are South Korea’s Kospi 200 and Hong Kong’s Hang Seng Index as both have rallied by around 1.30%. Japan’s Nikkei 225 is closed today for a public holiday. The Kospi 200 has hit a 4-moth high of 282.49 led by the financials and industrials sectors that have gained by 2.31% and 1.79% respectively.
- Hong Kong’s stock market has shrugged off a series of violent street protests over the weekend that caused two people in critical conditions. More demonstrations are planned for this week that includes Guy Fawkes Day on 05 Nov by putting on banned face masks in the streets of Hong Kong.
- Both Singapore’s Straits Times Index (STI) and Australia’s ASX 200 has only gained modestly by 0.13% and 0.20% respectively. The ASX 200 has been dragged down by financial shares again where the big 4 banks; CBA, NAB and ANZ have dropped by -1.72%, -3.03% and -0.65% respectively. Westpac shares are halted for trading after it has announced a A$2.5 billion capital raising in fresh equity to bolster its balance sheet. In addition, Westpac also reported a 15% decline in full-year cash earnings and cut its dividend pay-out for the first time in a decade.
- The S&P 500 E-mini futures has continued to inch higher by 0.22% in today’s Asian session to print another fresh all-time high of 3071 with a current intraday low of 3064.
Up Next:
- The Euro will be in focus as new ECB head Christine Lagarde delivers her first official speech.
- German PMI data is expected to remain firmly within contraction (below 50) at 41.9. The broader EZ read is also expected to remain within contraction at 45.7, with France bucking the trend to remain slightly expansive at 50.5. So Euro pairs have plenty to keep an eye on later this session.
- UK construction PMI is expected to weaken further to 44 versus 43.3 prior.
Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.