




Market Brief Trumps Tariff TimeOut Triggers Triumph for Risk Assets
See a summary of the top market themes and trends from today's US trading session!
Share this:

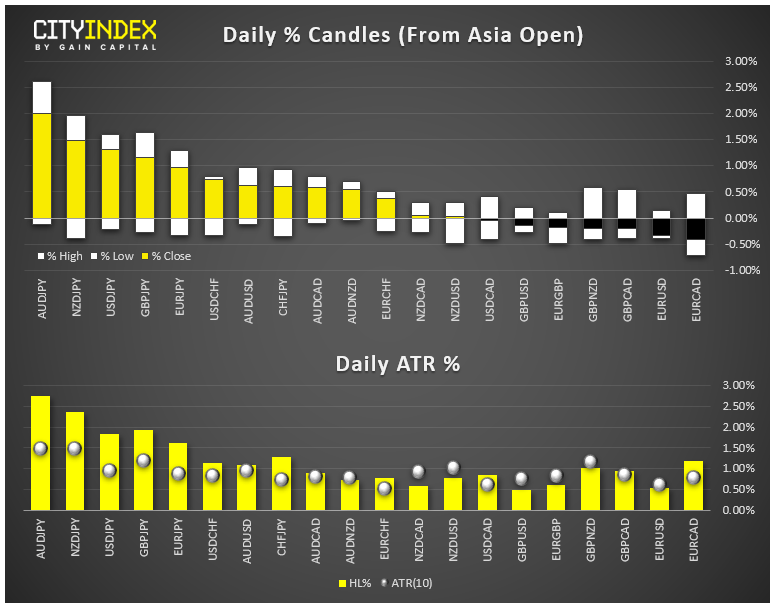
- FX:Risk trades were in demand, despite escalating protests in Hong Kong, making the aussie the day’s strongest major currency and the yen the weakest performer.
- US CPI figures printed a tick hotter than expected at 1.8% y/y, perhaps decreasing the likelihood of aggressive Fed rate cuts in the coming months.
- Commodities: Gold ticked lower on improving risk appetite, while oil (WTI) tacked on another 4% today.
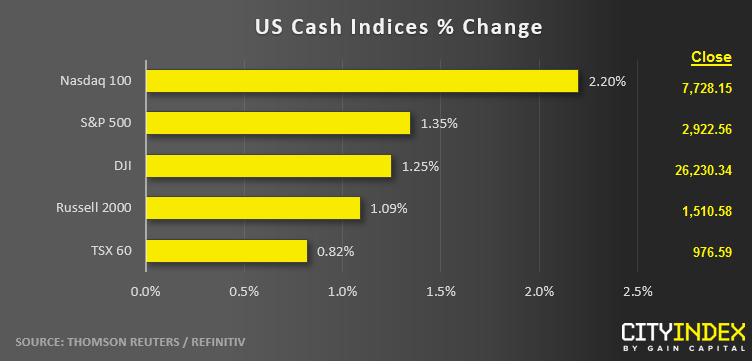
- US indices saw a big bullish turnaround on news that the US would delay 10% tariffs on certain goods, including cell phones, “to help a lot of people” ahead of the Christmas shopping season.
- Technology stocks (XLK) were the strongest sector on the risk asset revival; utilities (XLU) brought up the rear today.
- Traders will be keeping a close eye on tonight’s release of Chinese industrial production, retail sales and fixed asset investment data for any negative impact from the ongoing trade tensions with the US.
- Stocks on the Move:
- Big tariff delay winners today include Apple (AAPL, +4%) and Best Buy (BBY, +6%)
- US-listed shares of JD.com (JD) surged 13% following a better-than-expected earnings report from the Chinese online retailer.
- Insurer Genworth Financial (GNW) gained 16% after announcing a deal to sell a majority stake in its Canadian subsidiary.

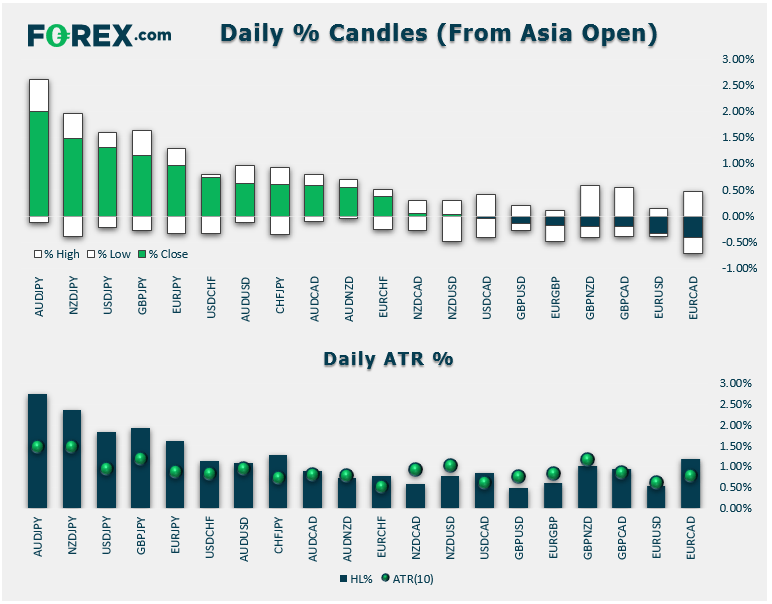
- FX: Risk trades were in demand, despite escalating protests in Hong Kong, making the aussie the day’s strongest major currency and the yen the weakest performer.
- US CPI figures printed a tick hotter than expected at 1.8% y/y, perhaps decreasing the likelihood of aggressive Fed rate cuts in the coming months.
- Commodities: Gold ticked lower on improving risk appetite, while oil (WTI) tacked on another 4% today.
- US indices saw a big bullish turnaround on news that the US would delay 10% tariffs on certain goods, including cell phones, “to help a lot of people” ahead of the Christmas shopping season.
- Technology stocks (XLK) were the strongest sector on the risk asset revival; utilities (XLU) brought up the rear today.
- Traders will be keeping a close eye on tonight’s release of Chinese industrial production, retail sales and fixed asset investment data for any negative impact from the ongoing trade tensions with the US.
- Stocks on the Move:
- Big tariff delay winners today include Apple (AAPL, +4%) and Best Buy (BBY, +6%)
- US-listed shares of JD.com (JD) surged 13% following a better-than-expected earnings report from the Chinese online retailer.
- Insurer Genworth Financial (GNW) gained 16% after announcing a deal to sell a majority stake in its Canadian subsidiary.

Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.