



Markets update Risk ON
The first day of the new month has started positively for equities and risk-sensitive yen pairs, while commodity dollars have also shown relative strength so far in the session.
Share this:

The first day of the new month has started positively for equities and risk-sensitive yen pairs, while commodity dollars have also shown relative strength so far in the session. At the time of writing, the German DAX index, for example, was up a solid 1.1% while the UK’s FTSE 100 was up 0.5 percent. US index futures were all trading higher ahead of the open.
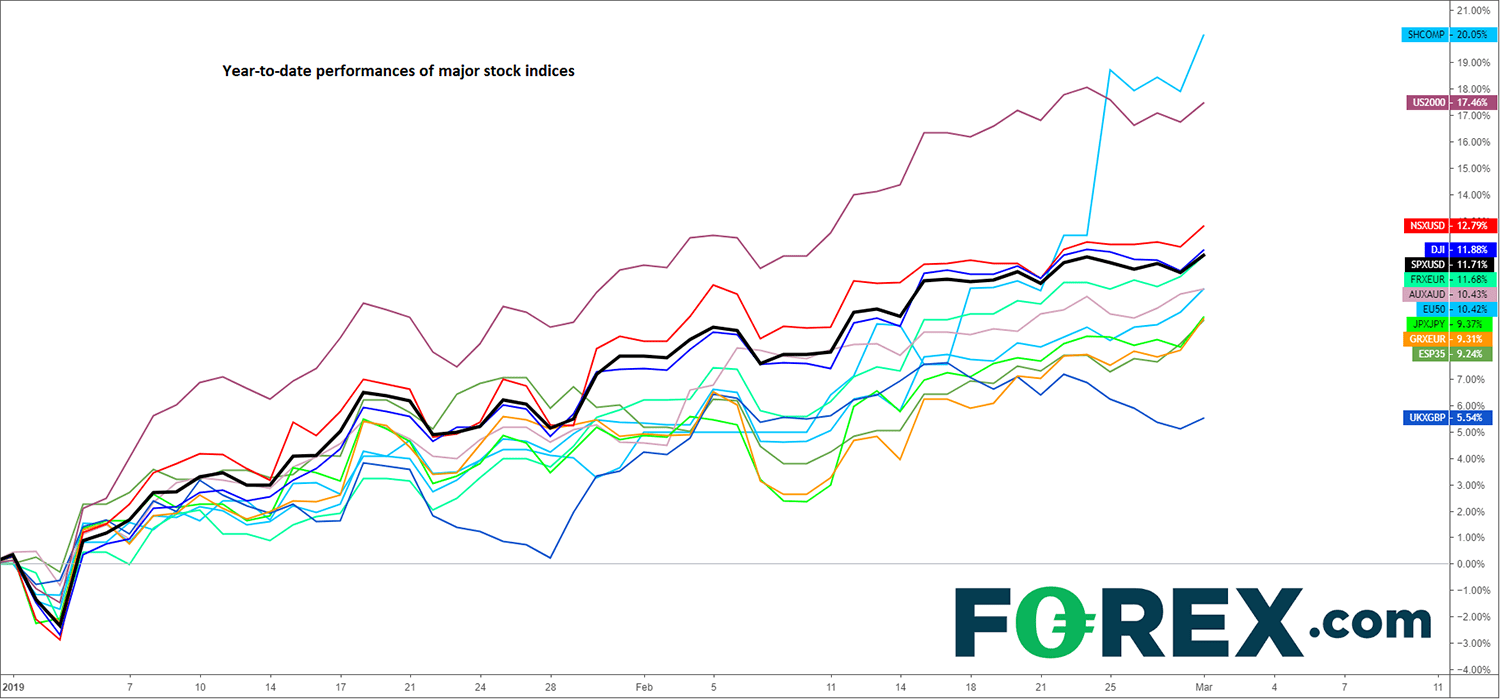
Thursday marked the last day of the month of February, a month which saw the major global equity indices extend their gains for the second consecutive month after they had tumbled at the end of last year. Sentiment improved on the back of positive US-China trade talks and as major central banks have re-iterated the need for interest rates to remain low for longer. For these reasons, we have seen the Shanghai Composite outperform her peers on a year-to-date basis, while ongoing Brexit uncertainty has held back the UK’s FTSE 100 (figure 1).
The key risk now is if no trade deal is achieved at the end of it all, although that looks increasingly unlikely. For now, therefore, momentum appears to be on the upside. But sooner or later, stock market investors will start focusing on something else.
Today's data releases have been overall positive, aiding the ongoing risk-rally, as can be seen below:
Data recap: mostly better-than-expected numbers:
- Caixin China Manufacturing PMI 49.9 vs. 48.5 expected and 48.3 last
- German Retail Sales +3.3% m/m vs. 1.9% expected (previous moth revised to -3.1% from -4.3%) and Unemployment Change -21K vs. -5K expected
- Swiss retail sales -0.4% vs. +0.3% expected
- Eurozone CPI 1.5% as expected, up from 1.4% last; Core CPI 1.0% vs. 1.1% expected and last; unemployment rate 7.8% vs. 7.9% expected (previous revised to 7.8% from 7.9%), and Final Manufacturing PMI 49.3 vs. 49.2 last
- UK Manufacturing PMI 52.0, in line with expectations; Mortgage Approvals 67K vs 63K expected
Coming up during North American session:
- Canadian GDP +0.0% expected
- US Core PCE Price Index +0.2% expected
- US Personal Spending -0.2% expected
- US ISM Manufacturing PMI 55.6 expected
- Today’s other not-so-important US data include: Personal Income, Revised UoM Consumer Sentiment, Revised UoM Inflation Expectations and Total Vehicle Sales
Figure 1: Shanghai Composite outperforming peers on a year-to-date basis
Source: TradingView and FOREX.com. Please note, this product is not available to US clients
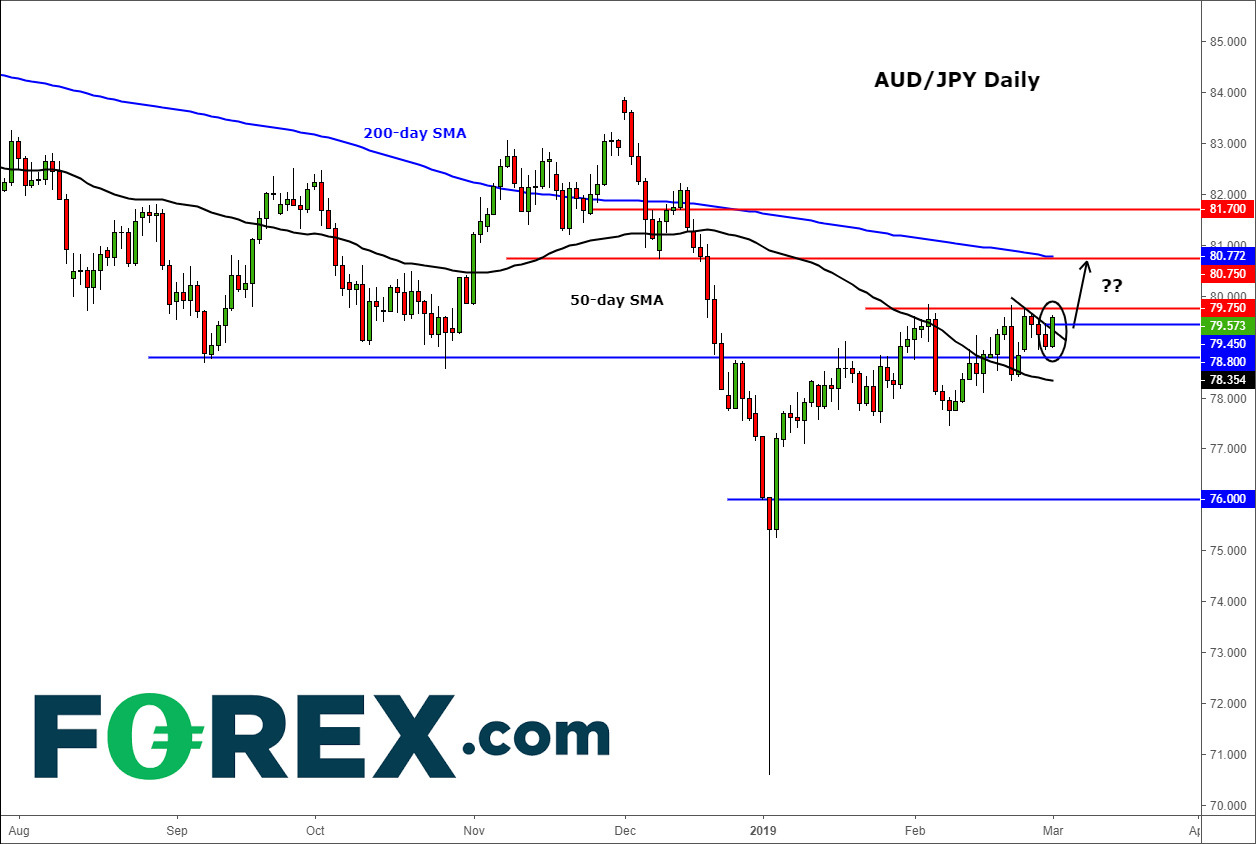
Figure 2: AUD/JPY could pop higher
With commodity dollars outperforming and the safe-haven Japanese yen being out of favour, the AUD/JPY could be the next JPY pair to break higher. It has consolidated bullishly since making a quick recovery in early January following a mini flash crash. Now tie has broken above a short-term bullish trend line. If it goes on to take out its 2019 high at 79.85 next, then this could pave the way for a rally towards the 200-day moving average next, at 80.70ish.
Source: TradingView and FOREX.com. Please note, this product is not available to US clients
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.
EUR/USD forecast: Dollar strength puts 1.1000 support in the spotlight | Currency Pair of the Week
The dollar extended its recent advance at the start of the week, with weakness across risk-sensitive assets reinforcing demand for the US currency. US equity futures slipped ahead of Nvidia’s earnings on Tuesday and an expected stock market debut by Anthropic later this week. Both events represent important tests for an AI trade that has become increasingly vulnerable to shifts in sentiment. In FX, EUR/USD nearly tested the psychologically important 1.1000 level, before bouncing modestly off its lows.


Forex & Gold Outlook: Dollar Dominates, Crosses Diverge
The US dollar rally gathers momentum as forex crosses develop contrasting technical setups. Matt Simpson examines eight FX markets and gold for potential trading opportunities.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.