



Sterling recovers election tougher and tougher to call
Sterling actually turned higher into the second half of Europe’s Wednesday session
Share this:

Boris Johnson’s hopes for a large majority that will enable the Tories to ‘get Brexit done look’ show signs of fading, with terrible timing for sterling. The earlier eye-catching dip suggests that persistent risks of an inconclusive outcome are nowhere near priced appropriately after the pound gained as much as 9% versus the dollar since August.
Still, sterling actually turned higher into the second half of Europe’s Wednesday session. A combination of profit taking after GBP/USD’s 114-odd pip drop from Tuesday’s near 9-month highs, plus pre-Fed statement caution probably accounts for easing pressure. Sentiment wafting back from the final day of campaigning might be playing a part, though it would be peripheral.
Wednesday’s most recent opinion poll, by Opinium looks a likelier prop. It showed the Tory-Labour gap was still narrowing, but the Conservatives were only down 1 point, at 45% with Labour up 2 to 33%. That points to a less drastic outcome than YouGov’s latest multi-level regression and “post-stratification” study. Conducted early this week, YouGov’s data crunch predicted a Conservative majority of 28, down from as much as 68 around a week ago
A broader look at UK assets shows that sterling and a relatively narrow group of domestically focused shares is still where the impact of any market upsets will be focused.
- Demand for sterling hedges and speculation has risen. The standard one-week ‘risk reversal’ option strategy shows bearish puts are favoured more than bearish calls by the most since 2016.
- The drop coincides with a FTSE 250 slide of 1.4%. The index is Europe’s worst-performer on Wednesday, on rekindled concerns over mid-cap companies’ greater exposure to sterling than those on the FTSE 100. Property shares remained the most sensitive sector to Brexit and election developments, with commercial property firms falling the hardest. Great Portland Street, workspace firm IWG and Hammerson fell 0.8% to 1%
- UK gilts tell a more nuanced tale. They have not priced the wave of optimism over a possible Conservative majority in the same way that sterling and other assets. 10-year yields continued to trade close to the top of their recent range on Wednesday afternoon, suggesting any safety-seeking sell-off won’t be drastic in the event of a market-unfriendly election outcome. 10-year gilt yields stood at 0.786% at the time of writing down one basis point on Monday’s close
Chart points
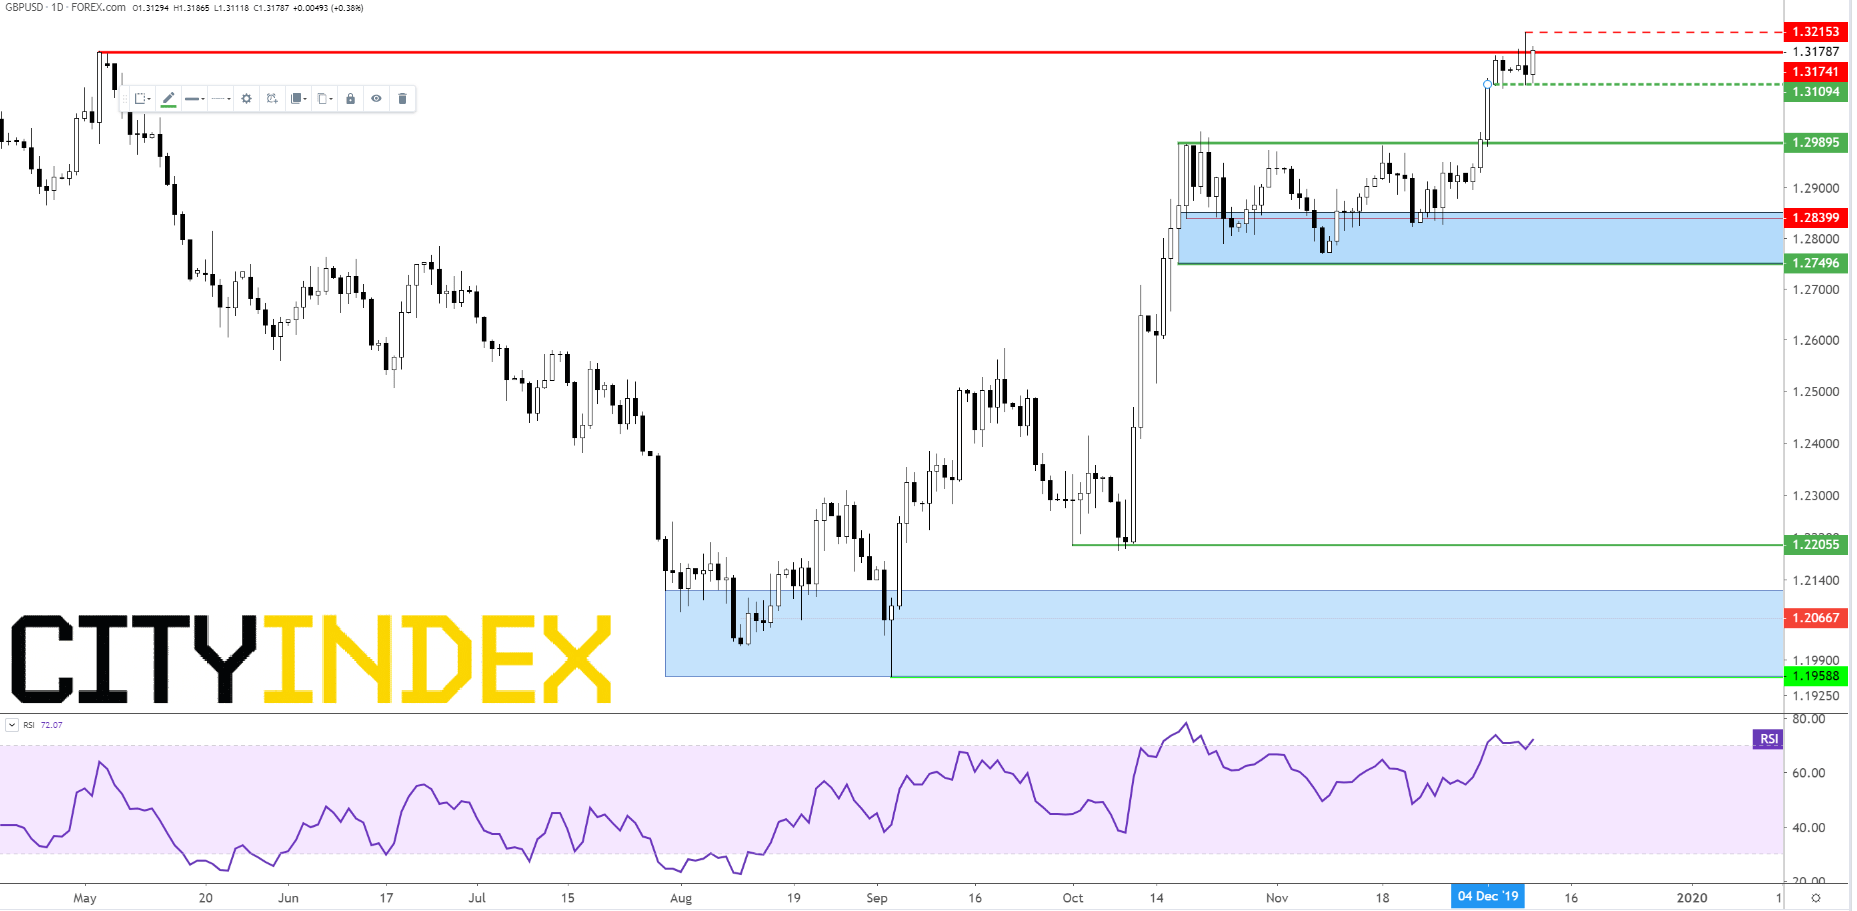
GBP/USD’s chart is by no means ominous heading into the biggest sterling risk event of the year. Tuesday’s 1.32 top in context was a first attempt to break May’s $1.3174 high. The rate was marginally above it at last look. Assuming caution returns as the voting begins tomorrow morning, traders will rely on $1.3109, 4th December high and implied support as rough divider of market friendly or unfriendly outcomes. The news blackout that will begin tonight, after at least one further poll, may see the pound drift around current prices and $1.31s ahead of early exit polls on Thursday night. A drop below the next important support region largely referenced by 17th October’s $1.2989 high, would be the final verdict that Boris Johnson has failed to secure a viable majority. With lots of shades of grey in between, GBP/USD should still operate above late 1.29s in the case of a smaller majority than the Conservatives hope for, though the $1.338 March peak (not pictured) probably requires a solid win by the incumbents.
GBP/USD – Daily [11/12/2019 17:07:25]
Boris Johnson’s hopes for a large majority that will enable the Tories to ‘get Brexit done look’ show signs of fading, with terrible timing for sterling. The earlier eye-catching dip suggests that persistent risks of an inconclusive outcome are nowhere near priced appropriately after the pound gained as much as 9% versus the dollar since August.
Still, sterling actually turned higher into the second half of Europe’s Wednesday session. A combination of profit taking after GBP/USD’s 114-odd pip drop from Tuesday’s near 9-month highs, plus pre-Fed statement caution probably accounts for easing pressure. Sentiment wafting back from the final day of campaigning might be playing a part, though it would be peripheral.
Wednesday’s most recent opinion poll, by Opinium looks a likelier prop. It showed the Tory-Labour gap was still narrowing, but the Conservatives were only down 1 point, at 45% with Labour up 2 to 33%. That points to a less drastic outcome than YouGov’s latest multi-level regression and “post-stratification” study. Conducted early this week, YouGov’s data crunch predicted a Conservative majority of 28, down from as much as 68 around a week ago
A broader look at UK assets shows that sterling and a relatively narrow group of domestically focused shares is still where the impact of any market upsets will be focused.
- Demand for sterling hedges and speculation has risen. The standard one-week ‘risk reversal’ option strategy shows bearish puts are favoured more than bearish calls by the most since 2016.
- The drop coincides with a FTSE 250 slide of 1.4%. The index is Europe’s worst-performer on Wednesday, on rekindled concerns over mid-cap companies’ greater exposure to sterling than those on the FTSE 100. Property shares remained the most sensitive sector to Brexit and election developments, with commercial property firms falling the hardest. Great Portland Street, workspace firm IWG and Hammerson fell 0.8% to 1%
- UK gilts tell a more nuanced tale. They have not priced the wave of optimism over a possible Conservative majority in the same way that sterling and other assets. 10-year yields continued to trade close to the top of their recent range on Wednesday afternoon, suggesting any safety-seeking sell-off won’t be drastic in the event of a market-unfriendly election outcome. 10-year gilt yields stood at 0.786% at the time of writing down one basis point on Monday’s close
Chart points
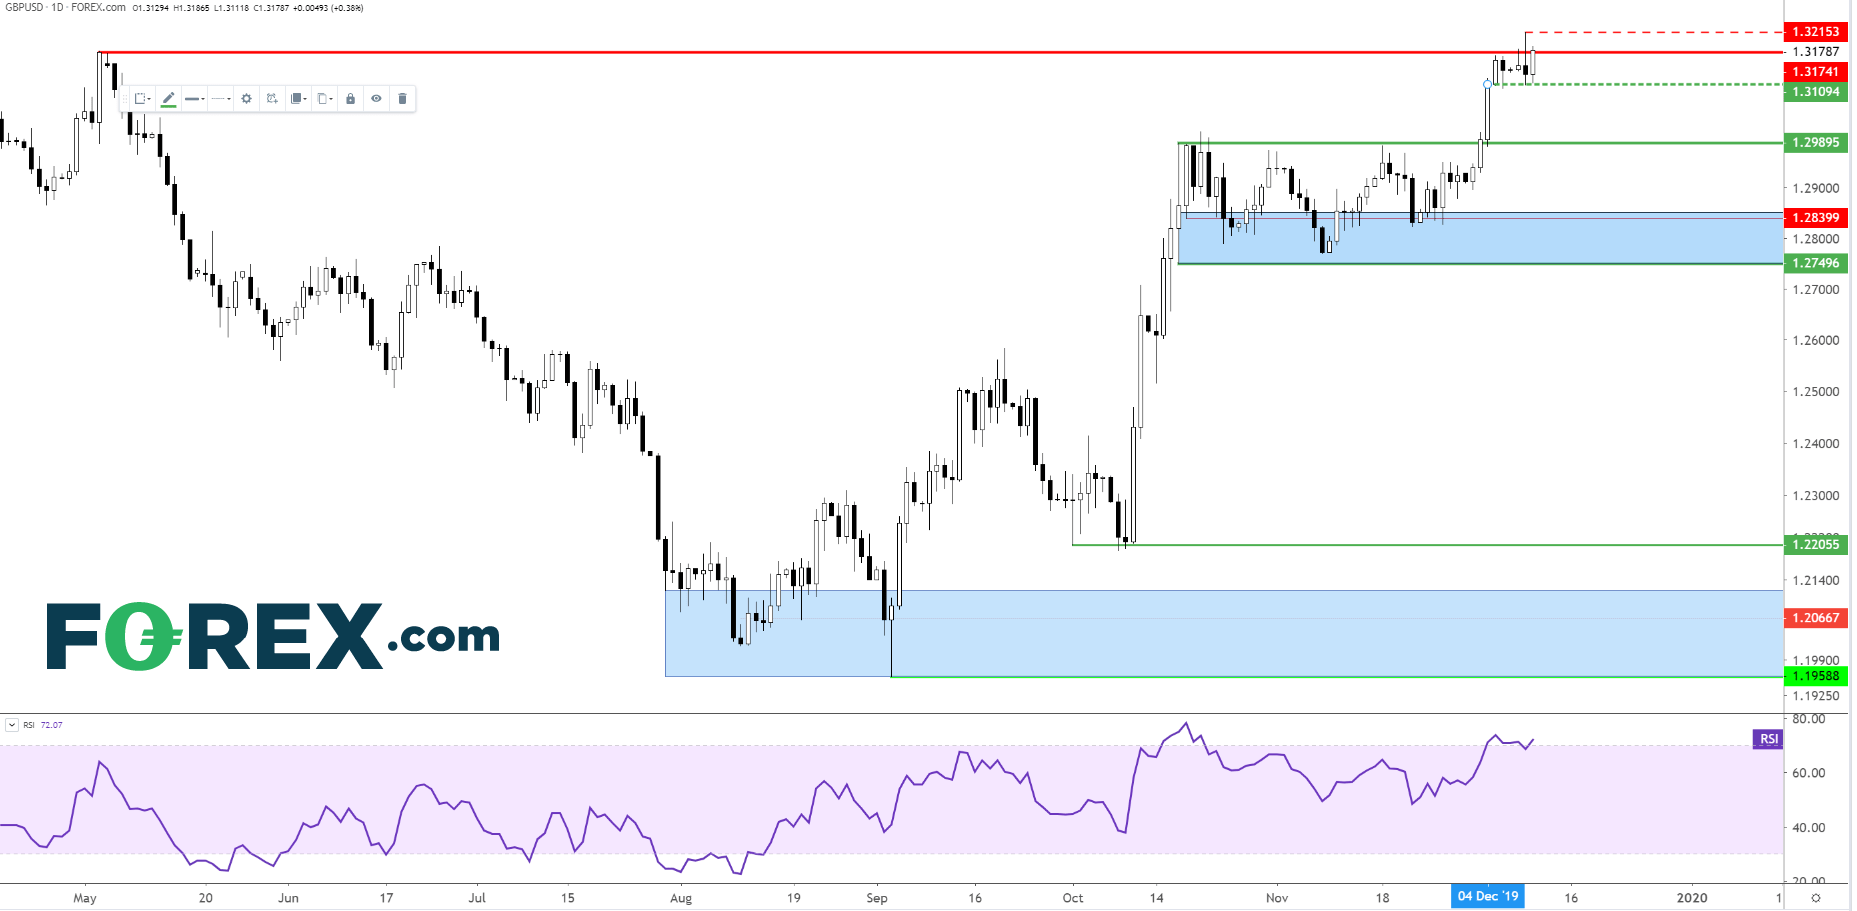
GBP/USD’s chart is by no means ominous heading into the biggest sterling risk event of the year. Tuesday’s 1.32 top in context was a first attempt to break May’s $1.3174 high. The rate was marginally above it at last look. Assuming caution returns as the voting begins tomorrow morning, traders will rely on $1.3109, 4th December high and implied support as rough divider of market friendly or unfriendly outcomes. The news blackout that will begin tonight, after at least one further poll, may see the pound drift around current prices and $1.31s ahead of early exit polls on Thursday night. A drop below the next important support region largely referenced by 17th October’s $1.2989 high, would be the final verdict that Boris Johnson has failed to secure a viable majority. With lots of shades of grey in between, GBP/USD should still operate above late 1.29s in the case of a smaller majority than the Conservatives hope for, though the $1.338 March peak (not pictured) probably requires a solid win by the incumbents.
GBP/USD – Daily [11/12/2019 17:07:25]

Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.