



Traders hedge the Nasdaq’s rally during a typically volatile month
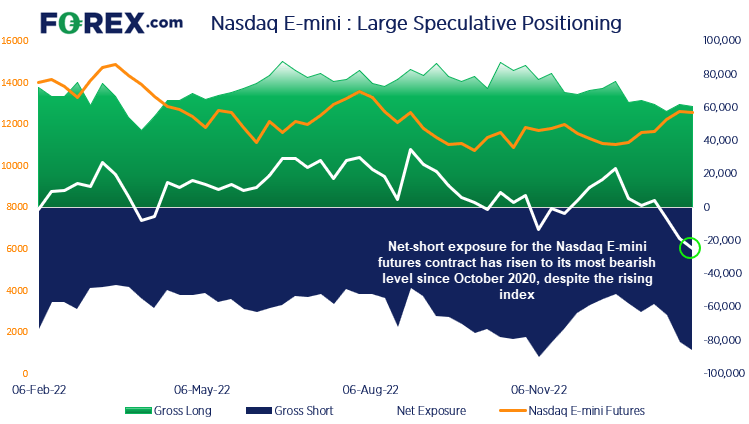
We noted that futures traders are increasingly net-short the Nasdaq, and that February has been the most volatile months for the index over the past five years.
Share this:

Traders increase bearish exposure to the Nasdaq whilst prices rise
It’s been a great start to the year for the Nasdaq 100, which has risen over 14% so far and has outperformed the Dow Jones and S&P 500. Yet after such strong moves, there comes a point where mean reversion must surely kick in. And looking at the market positioning of large speculators, they’re either erring on the side of caution or betting that the index will fall over.
The most recent COT report (commitment of traders) shows that net-short exposure for the Nasdaq 100 E-mini futures contract is at its most bearish level since October 2020. This means the market has to fall to justify the net-short exposure, otherwise a break higher could trigger some short-covering and add fuel to a bullish fire.

Seasonality has favoured bears in February, over the past thirty years
We like to see seasonality on a market as it can sometimes provide a tendency for prices to move one way or another. So it is interesting to note that the Nasdaq has averaged negative returns in February over the past 30-years.
- The Nasdaq 100 has posted a negative average return of -0.28% in February over the past 30 years
- It has also closed lower 55.2% of the time.
- The average winning month has been 6.05%
- The average negative month has been -5.4%
However, more recent years this seasonal tendency has been less reliable, with a positive average return over the past 10 and 15 years yet a negative avg, return over the past five. So whilst this muddies the water for seasonally-generated bias for February we have noted something of interest for potential volatility.
February has been the most volatile month (on average) over the past five years
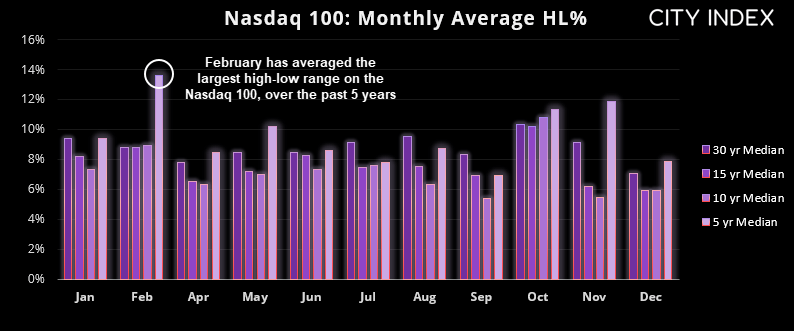
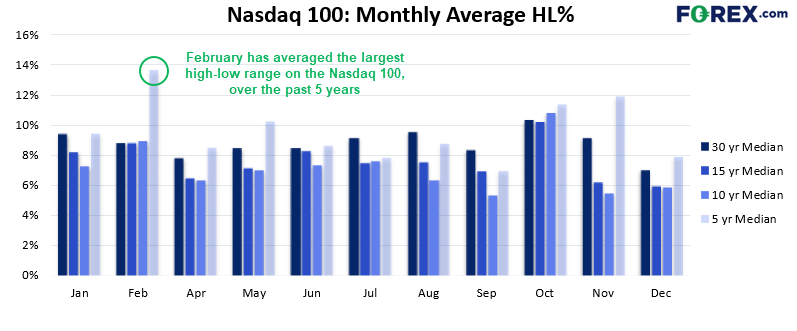
Over the past five years, the high-to-low range (HLR) of the Nasdaq’s monthly candle has been 13.6% - and the most volatile month of the year. Yet the prior 10, 15 and 30-years averaged a high-to-low month around 8.8%. Does this mean we’re in for another volatile month?
So far this month, the Nasdaq has produced a HLR of 3.25%, which is just under a quarter for February’s 5-year average. We’ve had six trading days in Feb so far and 14 to go, which leaves over half of the month left to post a strong move in either direction. Of course, a key driver for market sentiment at the moment is being derived from key US economic data and Fed members speaking, as traders try to decipher if we really will see interest rates ‘higher for longer’ (bearish for stocks), or whether the Fed will cut sooner than later (bullish for stocks).
US inflation is a key data point next week for global markets
The main event next week is the US inflation report at 00:30 AEDT on Wednesday morning (Tuesday in the US) and it can easily turn the dial for Fed expectation. A soft print likely lowers the Fed fun futures curve, weighs on the US dollar and send stocks higher. However, the more volatility reaction may come from a hotter-than-expected inflation report, as it is the last thing markets want to hears. And that could topple indices further from their YTD highs, drag gold with it and propel the US dollar higher.
Nasdaq 100 daily chart:
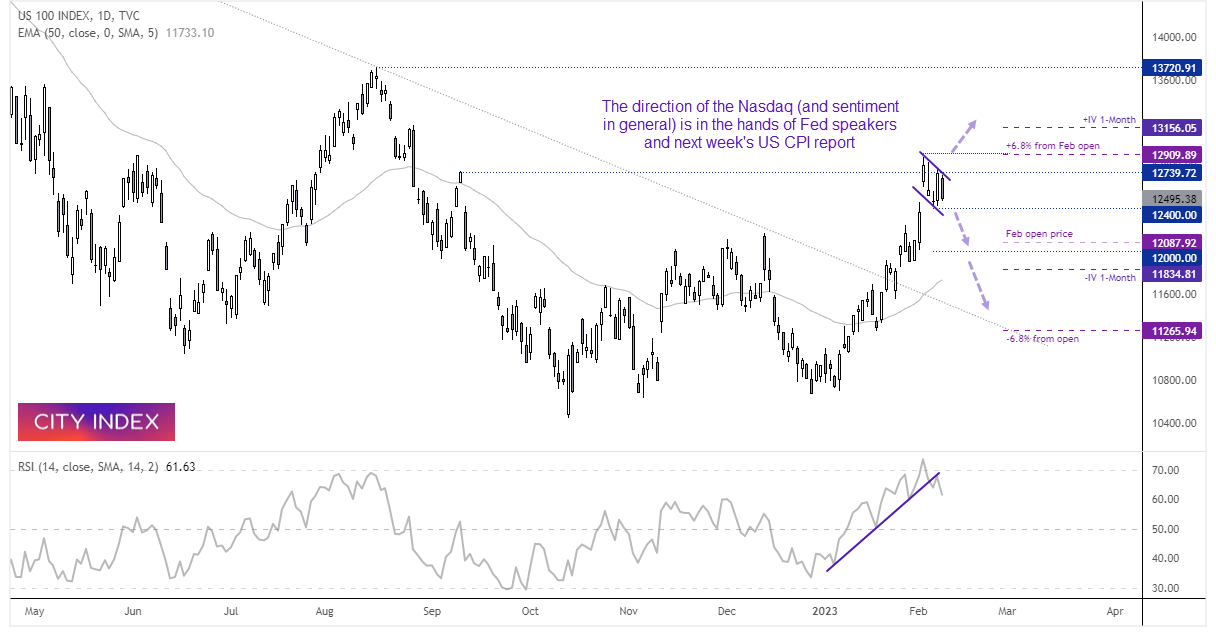
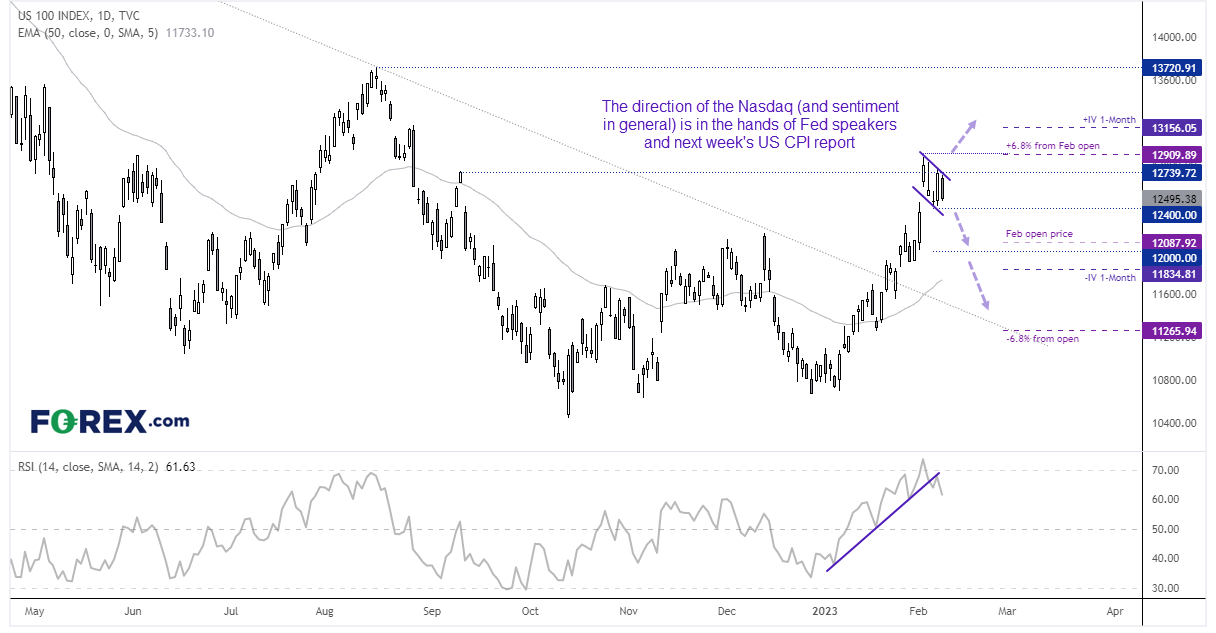
The Nasdaq briefly traded above the September high before pulling back. Momentum has been strong into the current highs with little in the way of a pullback (which a hot CPI report would likely trigger, although RSI (14) recently entered the overbought zone and has since pulled back with prices.
Bearish scenario:
A daily close or break below 12400 suggests a correction is underway, with 12,000 being a viable target due to its round-number status, and it is also near the monthly open price. But if momentum does turn lower and the Fed become increasingly hawkish, note that -6.8% from Feb’s open (half of February’s HLR) is all the way down at 11,265, although the 1-month implied volatility is currently around 11,834.
Bullish scenario:
If any downside break lacks bearish legs, bulls could seek low volatility dips above 12000 – 12,100 and anticipated a break to news highs. Alternatively bulls could wait for a break above the cycle high to assume bullish continuation. And of we project the full HLR average of 13.6% from February’s open, the upper bound sits above 16,000.
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.
S&P, Nasdaq Slide as NVDA, AI Worries Continue to Build
It was a busy weekend in the headlines as a campaign to bring back Jensen Huang atop NVDA gained steam, even with accusations of possible treason and a circular funding model that has started to raise questions.

Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.