



US open: Stocks drop on Fed jitters
Stocks head lower as nerves set in ahead of the Fed's rate decision tomorrow and after the Swedish central bank hiked rates by 1%, ahead of forecasts.
Share this:

US futures
Dow futures -0.6% at 30879
S&P futures -0.67% at 3873
Nasdaq futures -0.7% at 11868
In Europe
FTSE -0.35% at 7211
Dax -1% at 12695
Euro Stoxx -0.8% at 3422
Central banks are the only game in town
US stocks are pointing southwards as investors position themselves for the Federal Reserve’s interest rate decision tomorrow, after a larger-than-expected rate hike in Sweden.
The Swedish central bank hiked rates by a full 1%, its largest hike in 3 decades and above the 75 basis points forecast. Could this be a sign of things to come from the Fed?
The Fed is widely expected to hike rates by 75 basis points, the third straight 75 bps hike, as they look to rein in inflation and will also provide new economic projections. Volumes remain light and the mood cautious, with few looking to take on large positions before hearing what the Fed says and where policymakers see rates going by the end of the hiking cycle. This is what will drive the markets, not the rate hike tomorrow, but what the Fed plan to do next.
Today there are some mid-tier data points due, housing permits, and housing starts. These come as data surrounding the housing market has broadly shown a cooling in the sector as interest rates rise.
Corporate news:
Ford is falling some 5% lower pre-market after warning that supplier’s costs were expected to be around $1 billion higher due to inflation and supply chain issues. The automaker reaffirmed full-year guidance, but that hasn’t stemmed the selloff.
Where next for the Nasdaq?
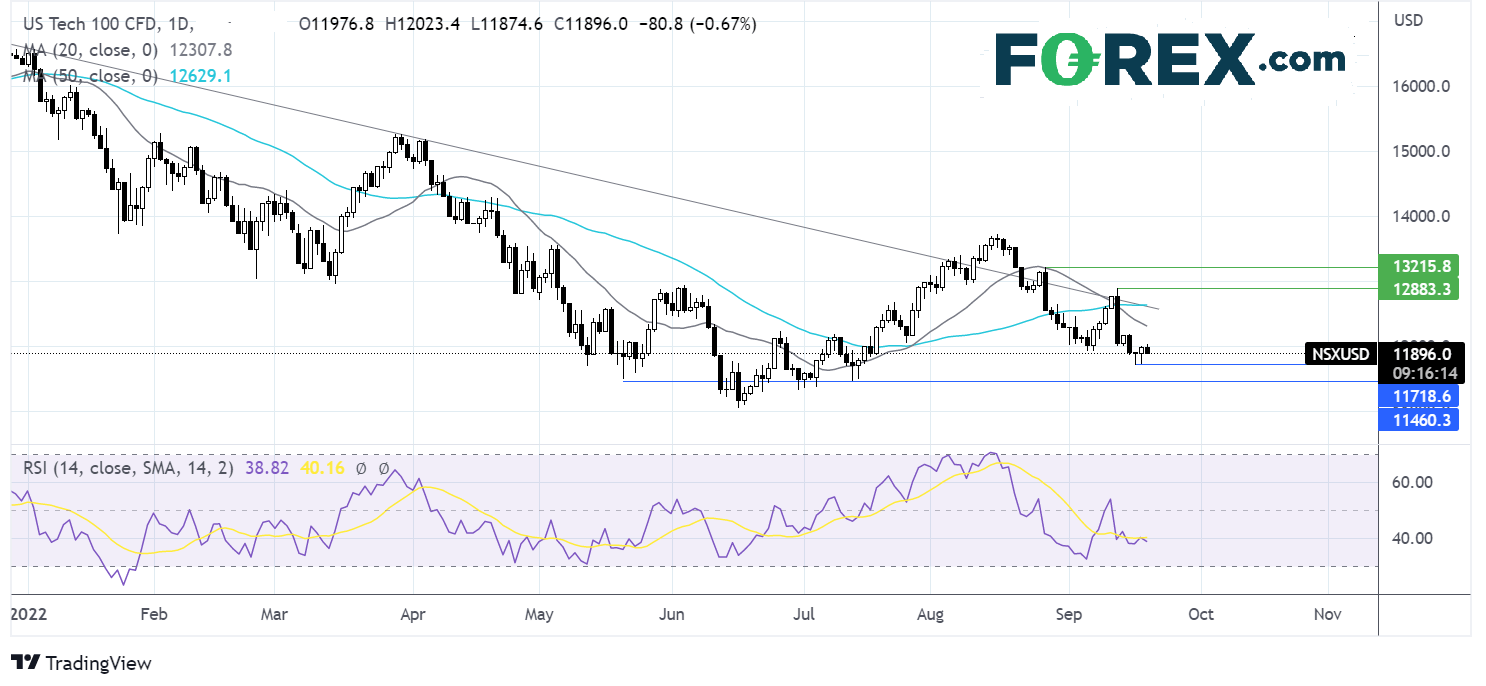
The Nasdaq failed to close over the falling trendline resistance, falling below the 20&50 sma, and took out last week’s low of 11900. This, combined with the 20 sma crossing below the 50 sma and the bearish RSI, suggests that there is more downside to come. Should buyers fail to defend 11700, last week’s low, sellers will look towards support around 11430 ahead of 11036, the 2022 low. On the flip side, a rise above 12300, the 20 sma, and 12620, the falling trendline resistance, would open the door to 12900, the weekly high.
FX markets – USD rises, GBP edges higher.
The USD is rising as attention is focused on the FOMC meeting, which kicks off today. Hawkish Fed bets and safe haven flows to keep the greenback supported.
EUR/USD is falling despite German PPI unexpectedly rising to a record level of 45.3% YoY, up from 37.2%, owing to surging energy costs. ECB Lagarde is due to speak later today. Recent ECB speakers have been in favour of smaller rate hikes after the latest jumbo-sized hike. Will Lagarde follow suit?
GBP/USD is edging higher above 1.14 but looks vulnerable as investors focus on the Fed and BoE monetary policy meetings this week and potential divergence. While the Fed is looking at a 75 basis point or 100 basis point hike, the BoE is looking at a 50 or 75 basis point hike.
GBP/USD +0.12% at 1.1446
EUR/USD -0.13% at 1.00
Oil hovers around 85.00
Oil is edging lower, slipping below 85.00 per barrel and paring modest gains from yesterday. While OPEC+ producing less than the quota is keeping supply challenges under the spotlight, all eyes are on the Fed’s rate decision for the next catalyst.
Even as output by OPEC+ missed the quota by 3.583 million barrels in August, the fact that prices fell anyway says a lot about the demand side of the equation.
The price has fallen 30% from June highs and are on track for the fourth straight month of declines as investors fret over the stronger USD and slowing growth hitting the demand outlook. Both Brent and WTI crude is set for the worst quarterly decline in percentage terms since the start of the pandemic.
WTI crude trades -0.6% at $84.33
Brent trades -0.5% at $91.00
Looking ahead
21:30 API crude oil stockpiles
US futures
Dow futures -0.6% at 30879
S&P futures -0.67% at 3873
Nasdaq futures -0.7% at 11868
In Europe
FTSE -0.35% at 7211
Dax -1% at 12695
Euro Stoxx -0.8% at 3422
Learn more about trading indices
Central banks are the only game in town
US stocks are pointing southwards as investors position themselves for the Federal Reserve’s interest rate decision tomorrow, after a larger-than-expected rate hike in Sweden.
The Swedish central bank hiked rates by a full 1%, its largest hike in 3 decades and above the 75 basis points forecast. Could this be a sign of things to come from the Fed?
The Fed is widely expected to hike rates by 75 basis points, the third straight 75 bps hike, as they look to rein in inflation and will also provide new economic projections. Volumes remain light and the mood cautious, with few looking to take on large positions before hearing what the Fed says and where policymakers see rates going by the end of the hiking cycle. This is what will drive the markets, not the rate hike tomorrow, but what the Fed plan to do next.
Today there are some mid-tier data points due, housing permits, and housing starts. These come as data surrounding the housing market has broadly shown a cooling in the sector as interest rates rise.
Corporate news:
Ford is falling some 5% lower pre-market after warning that supplier’s costs were expected to be around $1 billion higher due to inflation and supply chain issues. The automaker reaffirmed full-year guidance, but that hasn’t stemmed the selloff.
Where next for the Nasdaq?
The Nasdaq failed to close over the falling trendline resistance, falling below the 20&50 sma, and took out last week’s low of 11900. This, combined with the 20 sma crossing below the 50 sma and the bearish RSI, suggests that there is more downside to come. Should buyers fail to defend 11700, last week’s low, sellers will look towards support around 11430 ahead of 11036, the 2022 low. On the flip side, a rise above 12300, the 20 sma, and 12620, the falling trendline resistance, would open the door to 12900, the weekly high.

FX markets – USD rises, GBP edges higher.
The USD is rising as attention is focused on the FOMC meeting, which kicks off today. Hawkish Fed bets and safe haven flows to keep the greenback supported.
EUR/USD is falling despite German PPI unexpectedly rising to a record level of 45.3% YoY, up from 37.2%, owing to surging energy costs. ECB Lagarde is due to speak later today. Recent ECB speakers have been in favour of smaller rate hikes after the latest jumbo-sized hike. Will Lagarde follow suit?
GBP/USD is edging higher above 1.14 but looks vulnerable as investors focus on the Fed and BoE monetary policy meetings this week and potential divergence. While the Fed is looking at a 75 basis point or 100 basis point hike, the BoE is looking at a 50 or 75 basis point hike.
GBP/USD +0.12% at 1.1446
EUR/USD -0.13% at 1.00
Oil hovers around 85.00
Oil is edging lower, slipping below 85.00 per barrel and paring modest gains from yesterday. While OPEC+ producing less than the quota is keeping supply challenges under the spotlight, all eyes are on the Fed’s rate decision for the next catalyst.
Even as output by OPEC+ missed the quota by 3.583 million barrels in August, the fact that prices fell anyway says a lot about the demand side of the equation.
The price has fallen 30% from June highs and are on track for the fourth straight month of declines as investors fret over the stronger USD and slowing growth hitting the demand outlook. Both Brent and WTI crude is set for the worst quarterly decline in percentage terms since the start of the pandemic.
WTI crude trades -0.6% at $85.33
Brent trades -0.8% at $91.00
Learn more about trading oil here.
Looking ahead
21:30 API crude oil stockpiles
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.
DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.