



US open: Stocks extend gains as earnings impress
Stocks rise , adding to yesterday's strong rally as upbeat earnings distract from inflation, recession and hawkish Fed fears.
Share this:

US futures
Dow futures +2% at 30825
S&P futures +2.2% at 3760
Nasdaq futures +2.5% at 11340
In Europe
FTSE +1.3% at 7011
Dax +2% at 12912
Netflix is due after the close
US stocks are set to head higher, extending gains from the previous session as earnings remain in focus.
Stocks posted strong gains yesterday, with the Nasdaq rising 3,4% and the S&P500 booking gains of 2.6% after upbeat banking results and as investors positioned themselves for tech earnings.
Corporate earnings are stealing the show and overshadowing recession concerns. Those same recession fears had meant that the bar was low heading into earnings, raising the likelihood of beating estimates.
The macroeconomic calendar is quiet, with just US industrial output due to be released.
Even though stocks are rising, as earnings provide a welcomed distraction, this move higher is still a bear market rally rather than anything more meaningful. Cheap valuations and positive results have seen investors jump back into the market.
However, with inflation, hawkish central banks, and recession fears still providing headwinds to the market, there are questions about how high this rally can go. Inflation has proved to be stickier than initially expected, and the Fed could still take the terminal interest rate higher, making any meaningful recovery in stocks unlikely at this point.
Corporate news:
Goldman Sachs is rising over 2% pre-market after earnings and revenue beat forecasts. The investment bank also announced that it would be reorganizing its business into three units as part of a significant restructuring.
Netflix is due to report after the market close. Expectations are for 1 million new subscribers. EPS is expected to fall to $2.75 from $3.19 a year earlier. Revenue is expected to rise to $7.84 billion from $7.48 billion a year earlier.
Where next for the S&P500?
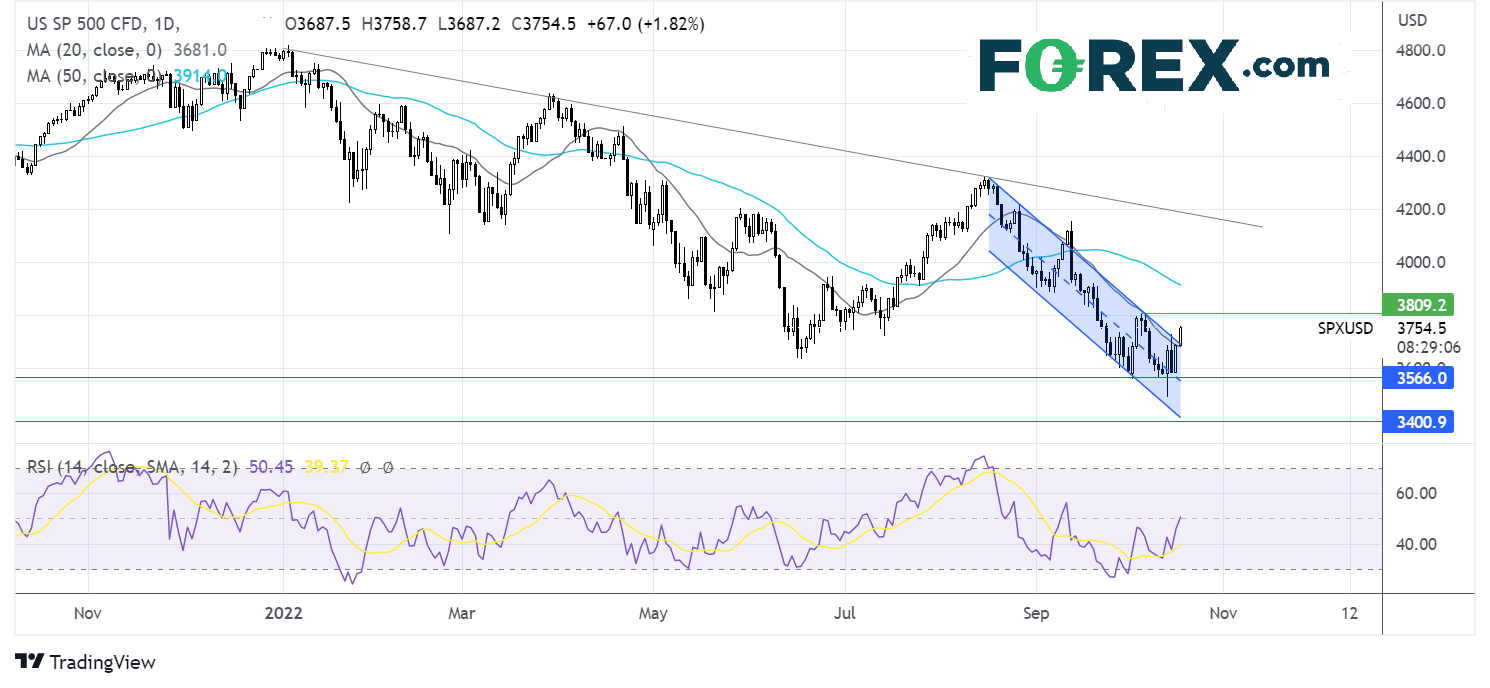
The S&P has risen out of the falling channel within which it has traded since mid-August. The break above the falling trendline, and the 20 sma, combined with the RSI moving back up to the 50 level keeps buyers hopeful of further upside. Buyers will now look to re-take the 3800 October high to expose the 50 sma at 3910. Meanwhile, sellers could look for a move below 3690 to re-entre the falling channel, bringing 3560 The October 3 low back into play.
FX markets – USD rises, GBP falls
The USD is rising after losses in the previous session. The upbeat market mood hit demand for the greenback. However, any falls southwards could be seen as buying opportunities. While the Fed intends to hike rates aggressively and for longer, the USD is likely to remain supported.
EUR/USD is falling as ZEW German economic sentiment remains weak in October. Sentiment did tick higher from September to 59.2, up from 61.9. However, this remains weak on a historical basis as fears over surging energy prices continue to weigh on sentiment.
GBPUSD is coming under pressure to snap a two-day winning as investors start to reprice the possibility of a large rate hike in November after the Chancellor’s U-turn on tax cuts. Earlier in the month BoE Governor Andrew Bailey had said that the central bank could raise rates by 1%, this may not now be necessary. Following high levels of volatility in the pound and the gilt market, things are starting to calm. That said, the outlook for the UK economy is still weak
GBP/USD -0.5% at 1.13
EUR/USD -0.14% at 0.9827
Oil slips for a third day
Oil prices are slipping lower for a third straight session. Oil has fallen around 5% over the past 3 sessions. While OPEC+ cutting oil output has helped to support the price, rising fears of a recession is hurting the demand outlook.
The fall in the USD yesterday failed to lift the price of oil. A weaker USD makes oil cheaper for buyers of other currencies.
Instead, China’s fuel demand outlook was also dragging on the price after the world’s largest oil importer announced that it would not be releasing Q3 GDP, retail sales or trade data. This is most likely due to the 20th Communist National Congress taking place this week.
US crude oil stockpile data is due to be released later and is expected to have risen for a second straight week.
WTI crude trades -1.1% at $84.90
Brent trades -1.2% at $91.10
Looking ahead
N/A
US futures
Dow futures +2% at 30825
S&P futures +2.2% at 3760
Nasdaq futures +2.5% at 11340
In Europe
FTSE +1.3% at 7011
Dax +2% at 12912
Learn more about trading indices
Netflix is due after the close
US stocks are set to head higher, extending gains from the previous session as earnings remain in focus.
Stocks posted strong gains yesterday, with the Nasdaq rising 3,4% and the S&P500 booking gains of 2.6% after upbeat banking results and as investors positioned themselves for tech earnings.
Corporate earnings are stealing the show and overshadowing recession concerns. Those same recession fears had meant that the bar was low heading into earnings, raising the likelihood of beating estimates.
The macroeconomic calendar is quiet, with just US industrial output due to be released.
Even though stocks are rising, as earnings provide a welcomed distraction, this move higher is still a bear market rally rather than anything more meaningful. Cheap valuations and positive results have seen investors jump back into the market.
However, with inflation, hawkish central banks, and recession fears still providing headwinds to the market, there are questions about how high this rally can go. Inflation has proved to be stickier than initially expected, and the Fed could still take the terminal interest rate higher, making any meaningful recovery in stocks unlikely at this point.
Corporate news:
Goldman Sachs is rising over 2% pre-market after earnings and revenue beat forecasts. The investment bank also announced that it would be reorganizing its business into three units as part of a significant restructuring.
Netflix is due to report after the market close. Expectations are for 1 million new subscribers. EPS is expected to fall to $2.75 from $3.19 a year earlier. Revenue is expected to rise to $7.84 billion from $7.48 billion a year earlier.
Where next for the S&P500?
The S&P has risen out of the falling channel within which it has traded since mid-August. The break above the falling trendline, and the 20 sma, combined with the RSI moving back up to the 50 level keeps buyers hopeful of further upside. Buyers will now look to re-take the 3800 October high to expose the 50 sma at 3910. Meanwhile, sellers could look for a move below 3690 to re-entre the falling channel, bringing 3560 The October 3 low back into play.

FX markets – USD rises, GBP falls
The USD is rising after losses in the previous session. The upbeat market mood hit demand for the greenback. However, any falls southwards could be seen as buying opportunities. While the Fed intends to hike rates aggressively and for longer, the USD is likely to remain supported.
EUR/USD is falling as ZEW German economic sentiment remains weak in October. Sentiment did tick higher from September to 59.2, up from 61.9. However, this remains weak on a historical basis as fears over surging energy prices continue to weigh on sentiment.
GBPUSD is coming under pressure to snap a two-day winning as investors start to reprice the possibility of a large rate hike in November after the Chancellor’s U-turn on tax cuts. Earlier in the month BoE Governor Andrew Bailey had said that the central bank could raise rates by 1%, this may not now be necessary. Following high levels of volatility in the pound and the gilt market, things are starting to calm. That said, the outlook for the UK economy is still weak
GBP/USD -0.5% at 1.13
EUR/USD -0.14% at 0.9827
Oil slips for a third day
Oil prices are slipping lower for a third straight session. Oil has fallen around 5% over the past 3 sessions. While OPEC+ cutting oil output has helped to support the price, rising fears of a recession is hurting the demand outlook.
The fall in the USD yesterday failed to lift the price of oil. A weaker USD makes oil cheaper for buyers of other currencies.
Instead, China’s fuel demand outlook was also dragging on the price after the world’s largest oil importer announced that it would not be releasing Q3 GDP, retail sales or trade data. This is most likely due to the 20th Communist National Congress taking place this week.
US crude oil stockpile data is due to be released later and is expected to have risen for a second straight week.
WTI crude trades -1% at $84.90
Brent trades -1.2% at $91.10
Learn more about trading oil here.
Looking ahead
N/A
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

S&P, Nasdaq Slide as NVDA, AI Worries Continue to Build
It was a busy weekend in the headlines as a campaign to bring back Jensen Huang atop NVDA gained steam, even with accusations of possible treason and a circular funding model that has started to raise questions.

Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.