



US open: Stocks flat ahead of PMI data
US stocks hold steady after yesterday's selloff and ahead of PMI data.
Share this:

US futures
Dow futures -0.05% at 33055
S&P futures -0.03% at 4133
Nasdaq futures -0.01% at 12895
In Europe
FTSE -0.63% at 7479
Dax -0.12% at 13206
Euro Stoxx -0.19% at 3650
PMIs expected to be mixed
US stocks are pointed to a muted open after booking steep losses in the previous session and as investors look ahead to the release of PMI data later today.
Stocks sold off sharply yesterday, led lower by the Nasdaq, as the market priced in expectations that the Fed would keep hiking interest rates aggressively. Hopes that the Fed could hint towards a dovish pivot are looking increasingly unlikely at this point. Inflation is still over 4 times higher than the target 2% level and the Fed simply can’t risk it becoming entrenched.
That is not to say that stocks can’t still push higher following Jackson Hole, but the pre-requisite is that Jerome Powell dials back slightly on the hawkish rhetoric, or at least just reiterates the July Fed meeting position.
Looking ahead US PMI data is expected to show that services PMI rose to 49 in August, up from 47 in July. Meanwhile manufacturing PMI is expected to ease to 51.5, down from 52.2. The level 50 separates expansion from contraction.
In corporate news:
Zoom is falling sharply pre-market after reporting EPS of $1.05 on revenue of $1.10 billion, ahead of forecasts of $0.92 on revenue of $1.12 billion. However, guidance for the current quarter was below expectations with EPS forecast at $0.83 down vs. forecasts of $0.93 and revenue is seen at $1.095 billion below the $1.16 billion forecast.
Where next for the Dow Jones?
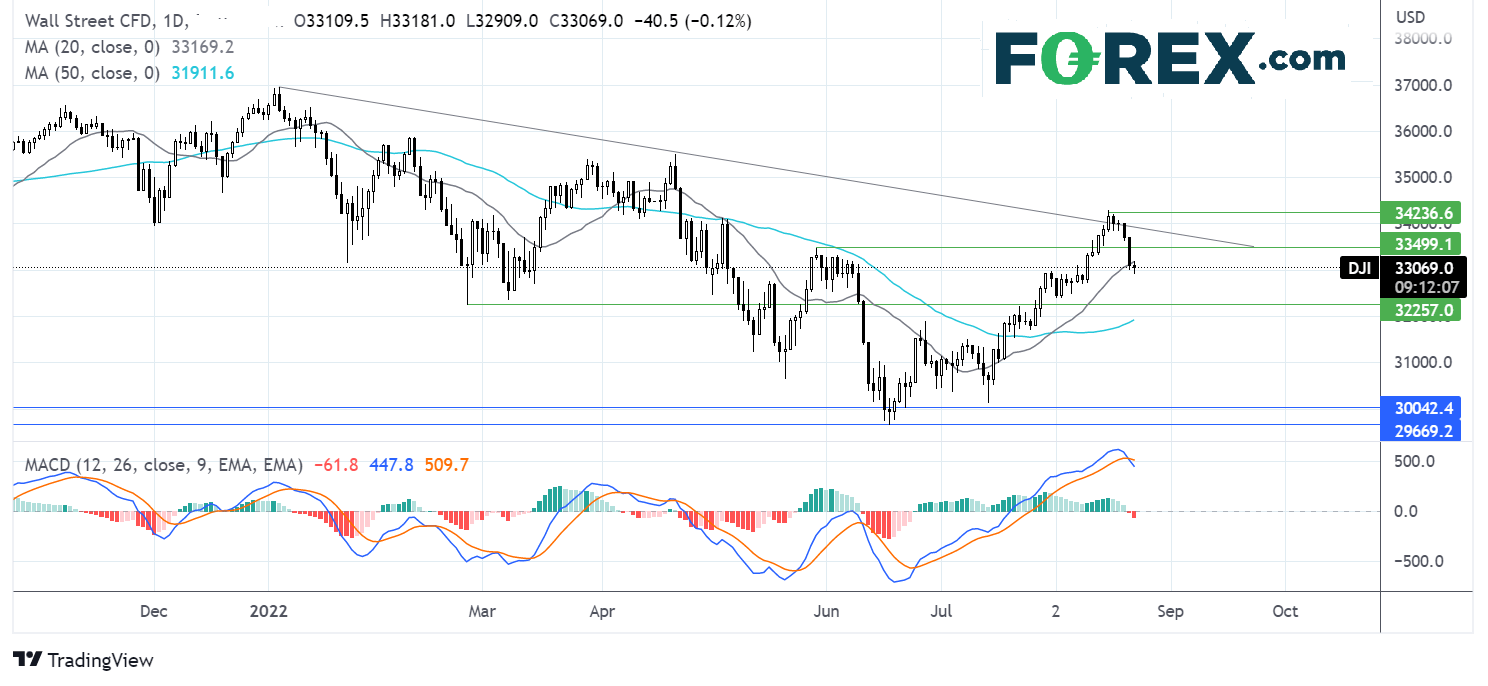
The Dow Jones rebound from the 2022 low ran into resistance at 34200 and is heading southwards. The price trades below the multi-month falling trendline, which combined with the bearish crossover on the MACD keeps sellers hopeful of further losses. Sellers need to break below 33000 round number to head towards 32260 the February low. On the flip side, buyers would look for a move over 33460 the June high to bring 34200 back into focus.
FX markets – USD steadies, EUR falls
The USD is holding steady after strong gains in the previous session. The USD rallied over 0.75% as investors ramped up hawkish Fed bets ahead of the Jackson Hole Symposium later today.
EUR/USD closed below parity yesterday for the first time in 2 decades and continues to trade at 20-year lows after business activity contracted again in August. The composite PMI fell to 49.2, down from 49.9 in July. The energy crisis and rising inflation mean a recession is more likely than not.
GBP/USD is holding steady at around 2022 lows after PMI data painted a mixed picture. Services PMI came in better than expected at 52.5, down from 52.6. Expectations had been for services to grow at a slower pace of 52. Manufacturing, however, slumped harder than forecast to 46, down from 52.1 in July.
GBP/USD -0.01% at 1.1768
EUR/USD -0.19% at 0.9922
Oil rises from session lows.
Oil prices are rising as tight supply worries overshadow concerns that slowing global growth could hurt the demand outlook for oil.
Oil has risen over 1.5% following remarks from Saudi Arabia that it could cut oil output to support prices which have fallen sharply in recent weeks. Saudi Arabia cited the fall in US inventories as part of the evidence that production may need to be reined in.
Oil prices had surged to $147 per barrel earlier in the year and now trade at $90 per barrel as recession fears pulled the price lower. However, oil prices appear to have found a floor around this level.
Separately the revival of the Iran nuclear deal is reportedly making progress albeit slow. This certainly feels like it’s one step forward two steps back process. I doubt traders are holding their breath on the announcement of a deal.
WTI crude trades +1.85% at $91.95
Brent trades +1.42% at $97.42
Looking ahead
14:45 US composite PMI
15:00 US new home sales
15:00 Eurozone consumer confidence
US futures
Dow futures -0.05% at 33055
S&P futures -0.03% at 4133
Nasdaq futures -0.01% at 12895
In Europe
FTSE -0.63% at 7479
Dax -0.12% at 13206
Euro Stoxx -0.19% at 3650
Learn more about trading indices
PMIs expected to be mixed
US stocks are pointed to a muted open after booking steep losses in the previous session and as investors look ahead to the release of PMI data later today.
Stocks sold off sharply yesterday, led lower by the Nasdaq, as the market priced in expectations that the Fed would keep hiking interest rates aggressively. Hopes that the Fed could hint towards a dovish pivot are looking increasingly unlikely at this point. Inflation is still over 4 times higher than the target 2% level and the Fed simply can’t risk it becoming entrenched.
That is not to say that stocks can’t still push higher following Jackson Hole, but the pre-requisite is that Jerome Powell dials back slightly on the hawkish rhetoric, or at least just reiterates the July Fed meeting position.
Looking ahead US PMI data is expected to show that services PMI rose to 49 in August, up from 47 in July. Meanwhile manufacturing PMI is expected to ease to 51.5, down from 52.2. The level 50 separates expansion from contraction.
In corporate news:
Zoom is falling sharply pre-market after reporting EPS of $1.05 on revenue of $1.10 billion, ahead of forecasts of $0.92 on revenue of $1.12 billion. However, guidance for the current quarter was below expectations with EPS forecast at $0.83 down vs. forecasts of $0.93 and revenue is seen at $1.095 billion below the $1.16 billion forecast.
Where next for the Dow Jones?
The Dow Jones rebound from the 2022 low ran into resistance at 34200 and is heading southwards. The price trades below the multi-month falling trendline, which combined with the bearish crossover on the MACD keeps sellers hopeful of further losses. Sellers need to break below 33000 round number to head towards 32260 the February low. On the flip side, buyers would look for a move over 33460 the June high to bring 34200 back into focus.

FX markets – USD steadies, EUR falls
The USD is holding steady after strong gains in the previous session. The USD rallied over 0.75% as investors ramped up hawkish Fed bets ahead of the Jackson Hole Symposium later today.
EUR/USD closed below parity yesterday for the first time in 2 decades and continues to trade at 20-year lows after business activity contracted again in August. The composite PMI fell to 49.2, down from 49.9 in July. The energy crisis and rising inflation mean a recession is more likely than not.
GBP/USD is holding steady at around 2022 lows after PMI data painted a mixed picture. Services PMI came in better than expected at 52.5, down from 52.6. Expectations had been for services to grow at a slower pace of 52. Manufacturing, however, slumped harder than forecast to 46, down from 52.1 in July.
GBP/USD -0.01% at 1.1768
EUR/USD -0.19% at 0.9922
Oil rises from session lows.
Oil prices are rising as tight supply worries overshadow concerns that slowing global growth could hurt the demand outlook for oil.
Oil has risen over 1.5% following remarks from Saudi Arabia that it could cut oil output to support prices which have fallen sharply in recent weeks. Saudi Arabia cited the fall in US inventories as part of the evidence that production may need to be reined in.
Oil prices had surged to $147 per barrel earlier in the year and now trade at $90 per barrel as recession fears pulled the price lower. However, oil prices appear to have found a floor around this level.
Separately the revival of the Iran nuclear deal is reportedly making progress albeit slow. This certainly feels like it’s one step forward two steps back process. I doubt traders are holding their breath on the announcement of a deal.
WTI crude trades +1.85% at $91.95
Brent trades +1.42% at $97.42
Learn more about trading oil here.
Looking ahead
14:45 US composite PMI
15:00 US new home sales
15:00 Eurozone consumer confidence
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.